


- Computershare qualified its American Depositary Receipts and ASX listed ordinary shares to trade on the OTCQX Best Market under tickers CMSQY and CMSQF, upgrading from the Pink Limited Market to simplify U.S. trading access.
- The move to OTCQX increases Computershare’s visibility with U.S. investors and aligns with its focus on issuer services, digital capability and governance standards across its core registry and corporate trust activities.
- We will now assess how Computershare’s shift to the OTCQX Best Market could influence its issuer services focused investment narrative.
Scan how Computershare's registry shift and OTCQX move compares with other high quality transfer agents and financial infrastructure stocks screened as list of solid balance sheet and fundamentals (12 results).
Computershare Investment Narrative Recap
To own Computershare, you need to be comfortable with a fairly concentrated services group that leans on issuer services, corporate trust and employee plans, and carries meaningful exposure to interest rate driven margin income. The short term swing factor still sits in how margin income and transaction volumes evolve. The OTCQX move and the OD6 Metals registry loss look immaterial at group level.
The bigger risk remains execution on digitisation and AI projects while defending share in core mandates as smaller registries compete more aggressively. Any stumble in delivering efficiencies or retaining key clients could pressure net margins, especially now that Computershare no longer has U.S. Mortgage Services as an additional profit stream.
The OD6 Metals decision to shift its share registry from Computershare to Xcend from 12 October 2026 is the most relevant recent announcement here. It underlines that even small registry contracts are contestable. For an investor, it is a reminder to watch client retention and win rates alongside headline revenue and EPS figures.
On its own, OD6 Metals is a very small piece of Computershare’s A$3.3b revenue base, so the financial hit looks limited. The more interesting angle is execution risk. Management is pushing digital capability and governance standards as key selling points. If that message translates into higher renewal rates and new mandates, it supports the core catalyst of better quality earnings from issuer and trust services.
Computershare's narrative projects $3.5b revenue and $887.9m earnings by 2029. This assumes 2.6% yearly revenue growth and an earnings increase of about 44% from $618.7m today.
Uncover why Computershare's fair value aligns with its current price.
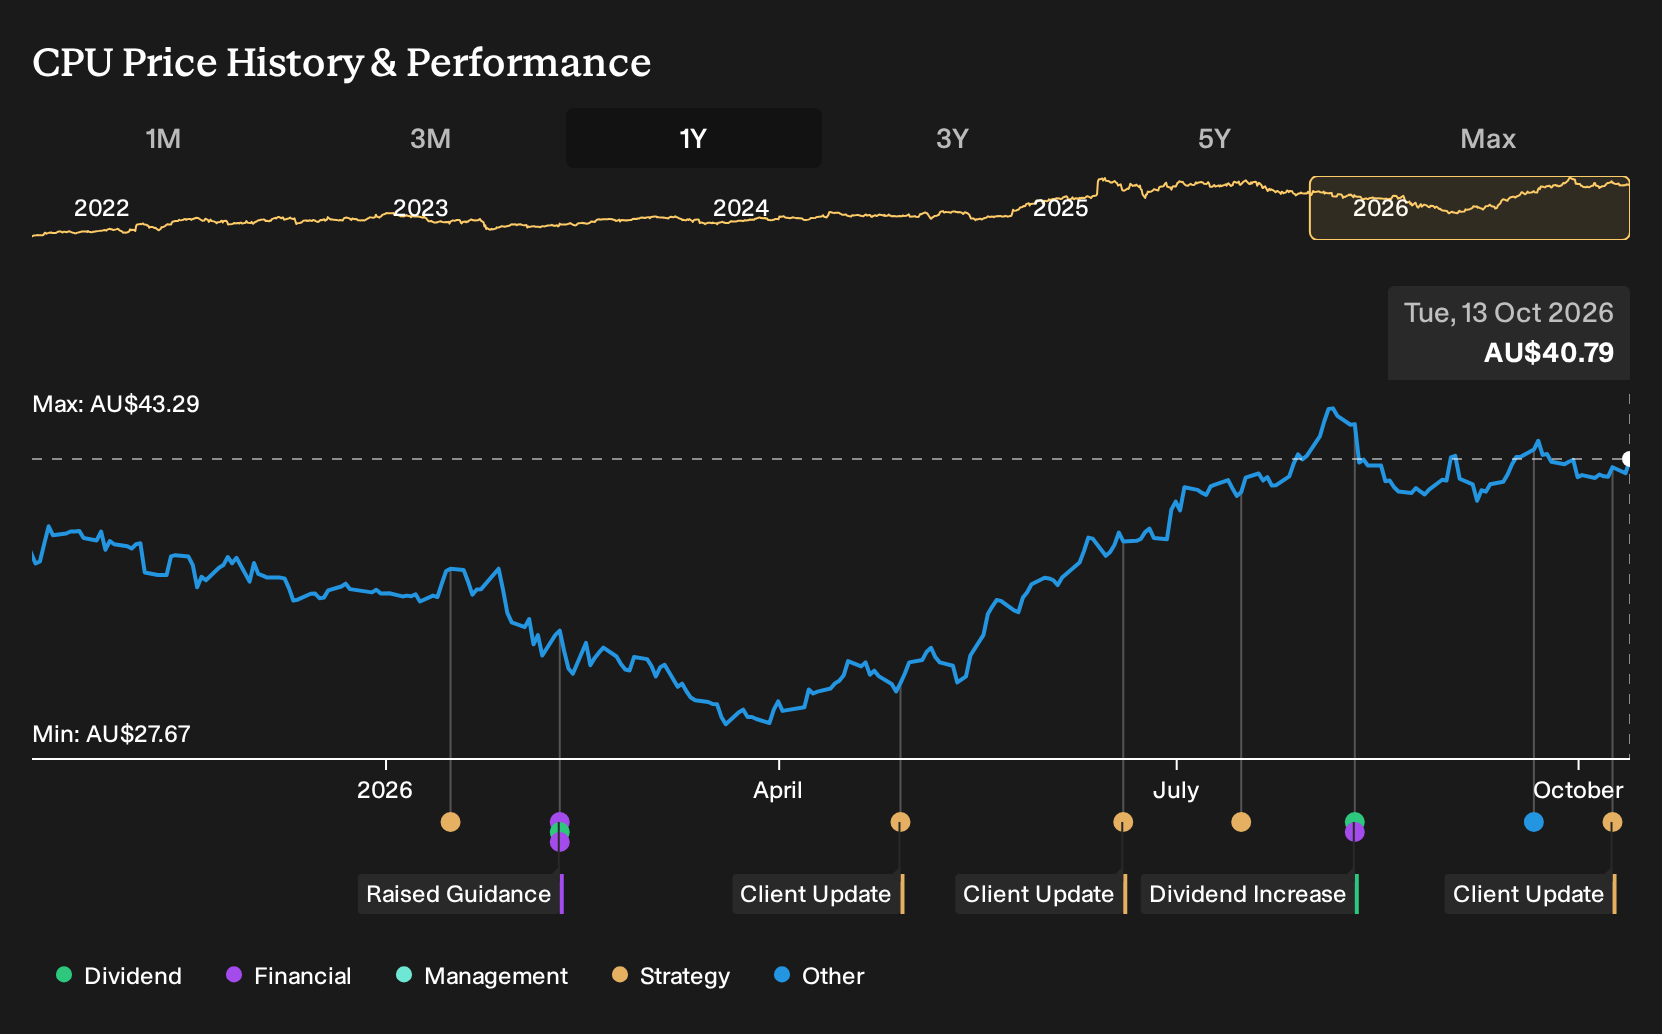
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster between A$39.74 and A$51.99, so you are looking at a wide spread of opinions on Computershare. Before the OD6 registry shift and OTCQX move, these private forecasts leaned on growth assumptions. Treat them as starting points and compare several contrasting views.
Explore 2 other Computershare fair value estimates, including one that suggests potential upside of up to 27% from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Computershare research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Computershare. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Computershare's overall financial health at a glance.
Looking for more Computershare style investment ideas?
If you want to put Computershare in context and round out your watchlist, use the Simply Wall St Screener to line it up against other businesses with different strengths and risk profiles.
- For investors who care most about financial resilience, start with a 6 resilient stocks with low risk scores that aim to keep business risk scores in check while still offering equity upside.
- If steady income is your priority, compare Computershare with a set of 5 dividend fortresses that focus on higher yields and balance sheet support for those payouts.
- To widen the opportunity set beyond well known tickers, scan a 15 high quality undiscovered gems that pair solid fundamentals with lighter market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com