


Umios (TSE:1333) has just put real money behind its pet food ambitions, committing roughly ¥11.4b for a 51% stake in Pet World International through a new joint venture with Wah Kong.
Recent trading has been softer, with Umios recording a 30 day share price return of down 5.98% and a 90 day move of down 9.23%. However, the 1 year total shareholder return of 10.97% and 3 year total shareholder return of 62.55% point to momentum that has built over a longer horizon as investors weigh deals like the Wah Kong joint venture against near term price weakness.
Scan how Umios compares to other potential compounders in the sector by reviewing our curated list of 74 high quality undiscovered gems with solid fundamentals and room for growth narratives.
Umios now owns a controlling stake in a pet food platform that looks commercially strong on paper. The real issue is whether the current share price already reflects that quality or still leaves a margin of safety.
Preferred P/E of 9.4x: Is it justified for Umios?
On simple earnings maths, Umios screens as inexpensive. A P/E of 9.4x at a last close of ¥1,195.5 sits well below the peer average and points to the market attaching a low earnings multiple to a group that has still delivered a 62.55% total return over three years.
The P/E ratio compares Umios' share price with its earnings per share. For a food and processing group with mature operations, P/E is a quick way to see how much investors are paying for each unit of profit compared with similar businesses on the Tokyo market.
Umios trades on a P/E of 9.4x while the broader JP market sits at 13.8x. Both the peer group on 15.7x and the JP Food industry on 16.3x command clearly higher earnings multiples. This suggests the market is pricing Umios' recent 17.7% earnings decline and 1.7% net margin into the stock more harshly than its five year earnings growth rate of 9.2% a year.
That discount is material. Compared with peers at 15.7x and the industry at 16.3x, Umios' 9.4x P/E points to the market assigning a meaningfully lower value to its profit stream than to other listed food companies on the same exchange.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 9.4x (UNDERVALUED).
Still, the recent declines in Umios' share price and the reported 17.7% earnings drop could pressure sentiment if the pet food bet takes time to deliver.
Find out about the key risks to this Umios narrative.
Another View: What Umios Looks Like On Cash Flows
The earnings multiple paints Umios as cheap. The SWS DCF model tells a very different story. At ¥1,195.5, the share price sits well above an estimated future cash flow value of ¥358.19, which points to the stock looking expensive on this framework. Which lens do you trust more when cash and profits disagree?
Look into how the SWS DCF model arrives at its fair value.
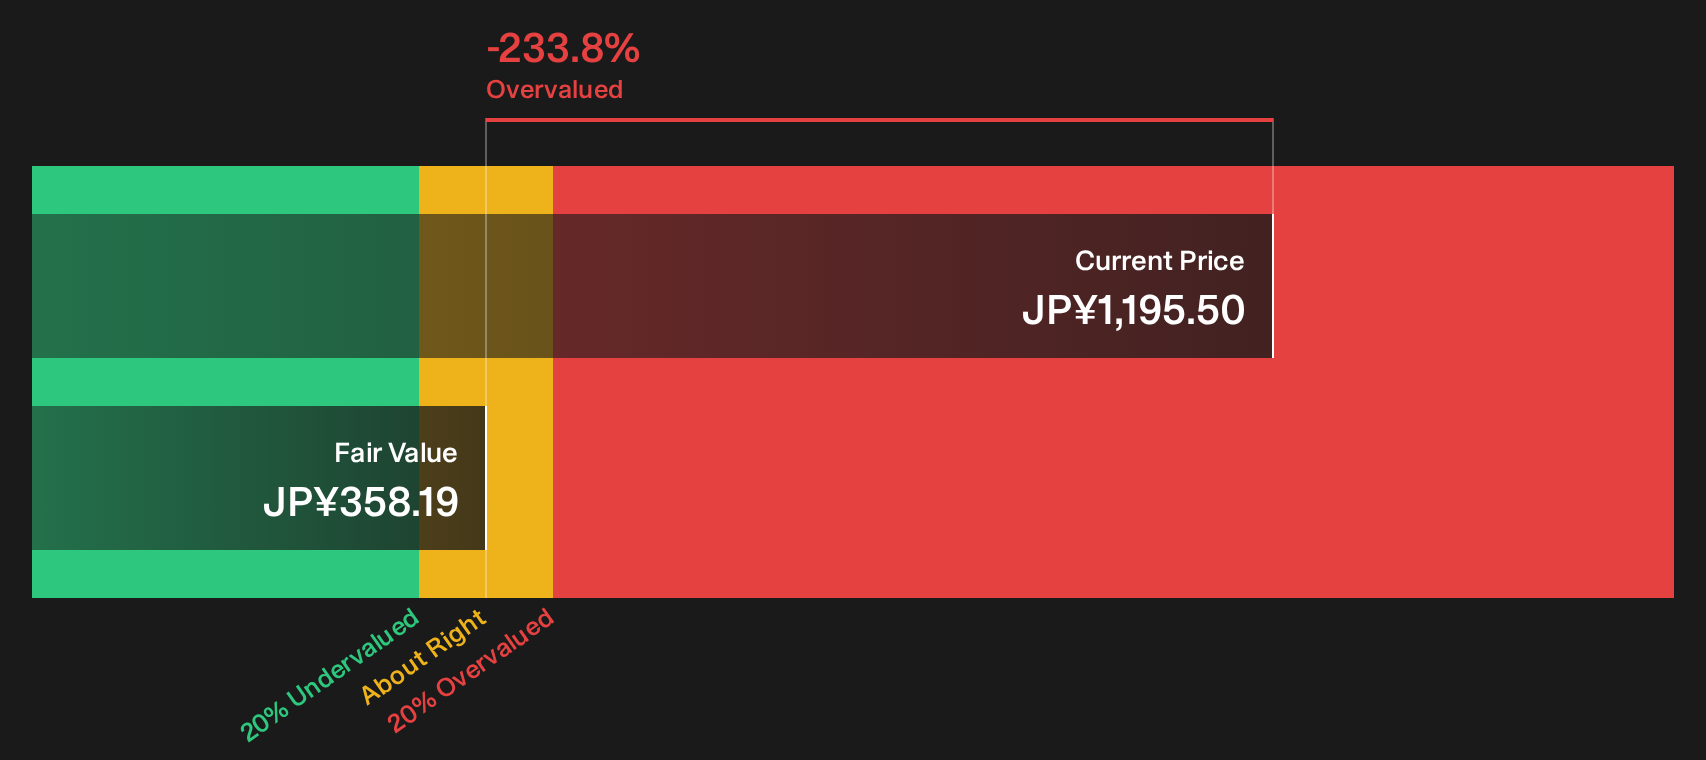
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Umios for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around Umios leave you torn, act quickly and stress test the numbers yourself, paying close attention to the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Umios?
Do not stop your research with Umios. Fresh opportunities often sit in plain sight when you compare businesses with different strengths, risk levels, and cash profiles.
- Target potential mispricings by scanning companies that appear overlooked on quality and valuation using the 13 high quality undervalued stocks.
- Seek reliable cash returns by reviewing income focused opportunities screened as 27 dividend fortresses.
- Adjust portfolio risk by focusing on resilient businesses filtered through the 24 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com