


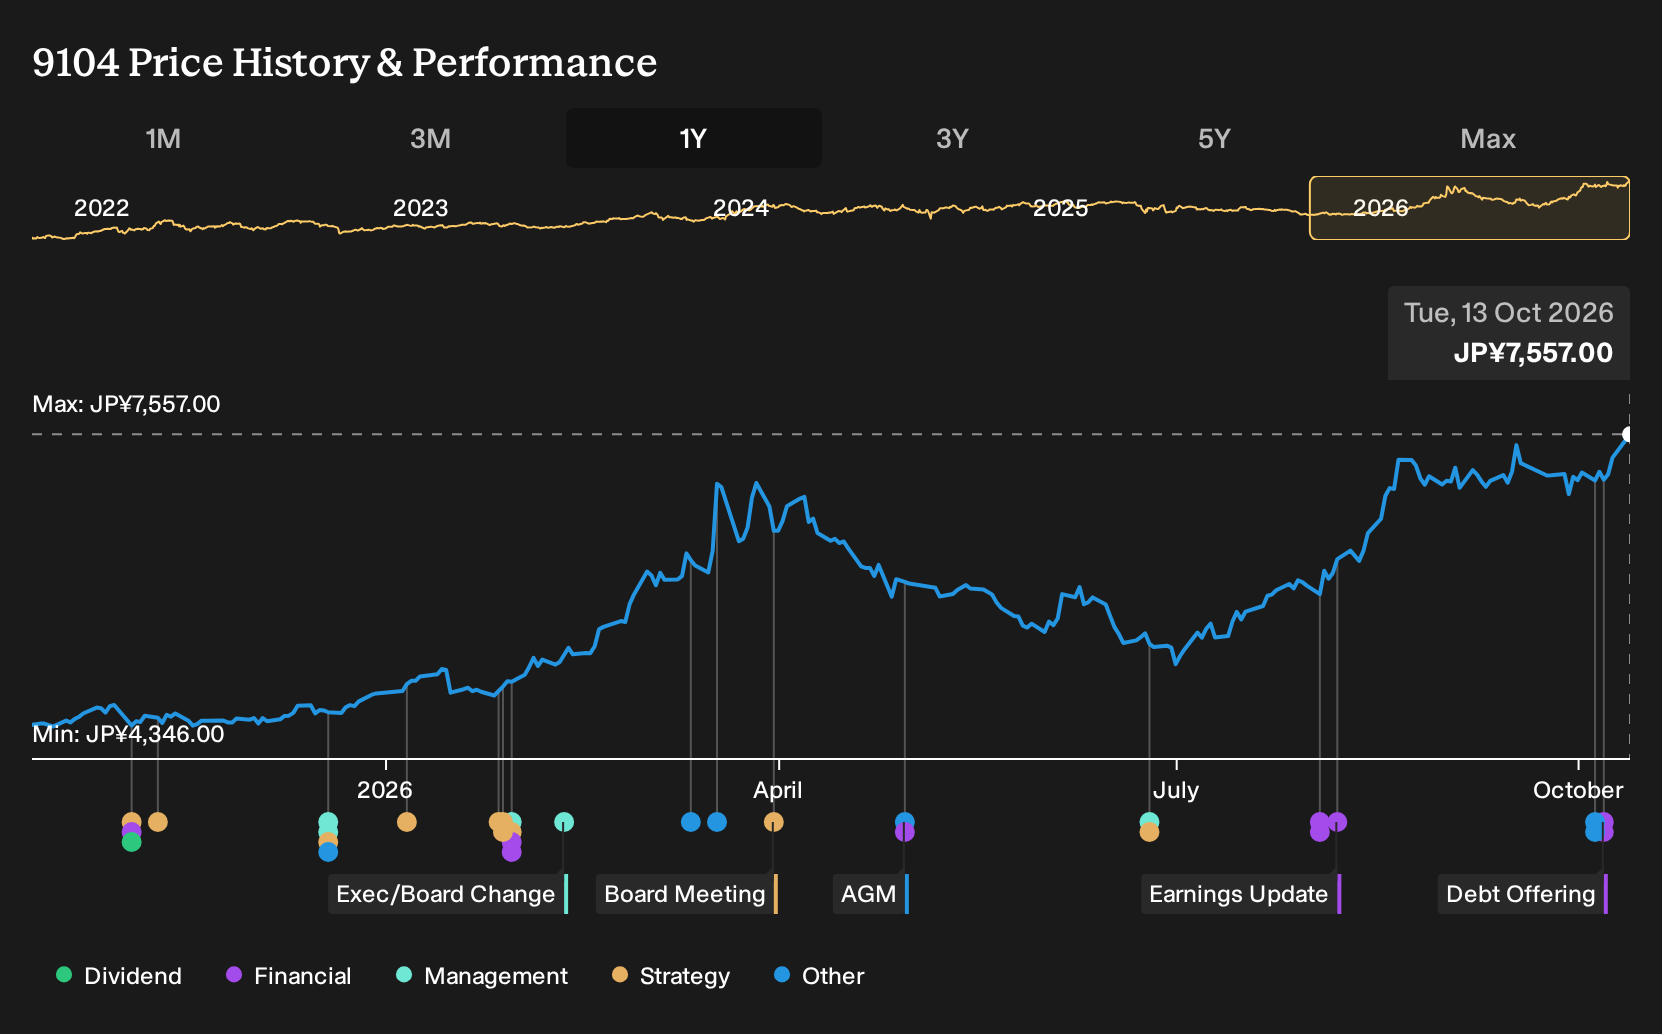
If you had only seen the headline that JERA hired Mitsui O.S.K. Lines to supply four ammonia carriers for Japan’s Blue Point Project, you might have filed it away as one more contract in the decarbonization story. Investors who held Mitsui O.S.K. Lines over the past year are up 78.0%, including dividends. If you were deciding back on 13 October 2025, what did you really need to believe about those early green-fuel bets and new carbon transport projects?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Mitsui O.S.K. Lines harder to judge, start where the gap is still open and scan 13 high quality undervalued stocks.
The Argument You Would Have Been Weighing On Mitsui O.S.K. Lines
The shares cost ¥4,346 at the start of the period. Anyone looking at Mitsui O.S.K. Lines then had to decide which story about its future felt more realistic, not which one was guaranteed.
The bullish case pinned Fair Value at ¥6,941. That view leaned on revenue rising 1.7% a year and profit margins settling at 13.4%, with a future P/E assumption of 10.3x.
The bearish script put Fair Value at ¥4,081. That side assumed revenue would decline 8.8% annually, margins would narrow to 9.6%, and the right future P/E was 11.8x.
What The Evidence Did To The Mitsui O.S.K. Lines Story
The most direct test of the Mitsui O.S.K. Lines thesis came from operations. Revenue moved to ¥730,987m in Q1 2027 from ¥432,704m a year earlier and net income also rose. Net margin shifted from 12.2% to 8.4%, so the profitability leg of the bullish case stayed unproven. Overall, the evidence cut both ways.
The key lesson is simple. When a thesis leans on margin resilience, do not just watch sales or headline profit. Track net margin against each new contract or project to see whether growth is arriving on the terms you priced in.
What Mitsui O.S.K. Lines' Price Already Assumes
Mitsui O.S.K. Lines now trades at ¥7,557. The selected Narrative argues that its Fair Value sits below that level, largely because decarbonization spending, tighter rules, and freight market pressure are all treated as long running cost and margin headwinds.
Anyone paying today’s price is effectively assuming that greener fleets, gas projects, and vehicle transport growth can support earnings despite those headwinds. The question is how the Narrative’s expectation of shrinking margins and higher funding costs lines up with that belief.
"The ongoing global shift toward carbon neutrality and increasingly strict environmental regulations are set to significantly raise compliance costs and require Mitsui O.S.K. Lines to allocate substantial capital for fleet modernization, which will strain free cash flow, limit reinvestment capacity, and compress net margins over the next decade."
The price and this Narrative do not agree. → Uncover what this Narrative says Mitsui O.S.K. Lines is actually worth
Beyond Mitsui O.S.K. Lines' Cargo
Mitsui O.S.K. Lines pulls attention toward cleaner fuels and complex routes. Your next question is what keeps bulk materials moving alongside that shift.
Dry cargo still has to cross oceans, whatever happens to ammonia projects or gas terminals. Another operator concentrates on hauling iron ore, grains and minerals efficiently.
This operator leans on fuel saving upgrades and younger vessels to manage voyage costs. That approach may help cushion earnings when freight cycles turn rough.
It treats cash from operations as something to send straight back to holders. The open issue is how steady that cash engine can remain when dry bulk demand wobbles.
One Narrative has already put a figure on it. → Uncover the company trading 13% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com