


- Republic Services expanded its Forward Landfill compost facility in California, adding processing space and upgraded infrastructure to handle more food and yard waste while supporting the state’s climate targets and local agriculture.
- The upgraded site, backed by a US$5.1 million CalRecycle grant and integrated with renewable energy projects, deepens Republic Services’ organics footprint alongside its growing statewide network of 17 organics facilities.
- Next, the focus shifts to how this stronger organics platform and raised full year guidance could reshape Republic Services’ investment narrative.
Republic Services Investment Narrative Recap
To own Republic Services, you need to be comfortable with a waste and recycling operator that relies on pricing power, landfill assets and steady earnings rather than rapid expansion. The bigger near term swing factor is execution on efficiency and sustainability projects that management already highlighted when it raised 2026 revenue, EBITDA and free cash flow guidance.
The Forward Landfill compost expansion supports that story but probably does not move the needle by itself. In the short term, the key catalyst is whether higher guidance proves achievable over the next few quarters. The biggest risk remains pressure on volumes, contracts and labor at a time when the group also carries a high level of debt.
The most relevant recent development alongside the compost news is the upgraded 2026 outlook following a quarter where Republic Services reported adjusted earnings and revenue that exceeded prior figures. That higher bar puts more attention on how well acquisitions, recycling commodity pricing and organics projects translate into cash generation rather than just headline revenue.
For you as an investor, the compost build out and the pending San Bernardino Sustainability Park connect directly to that execution test. They expand the organics platform and support California climate rules, yet they also require capital in a business already funding acquisitions and shareholder payouts. The thesis now leans on management running these projects efficiently without amplifying debt related risk.
Republic Services' current earnings are about US$2.2b and analysts forecast consensus earnings of US$2.7b by 2029. This implies an earnings increase of roughly US$0.5b alongside expected revenue of US$19.5b and an assumed 5.0% yearly revenue growth rate.
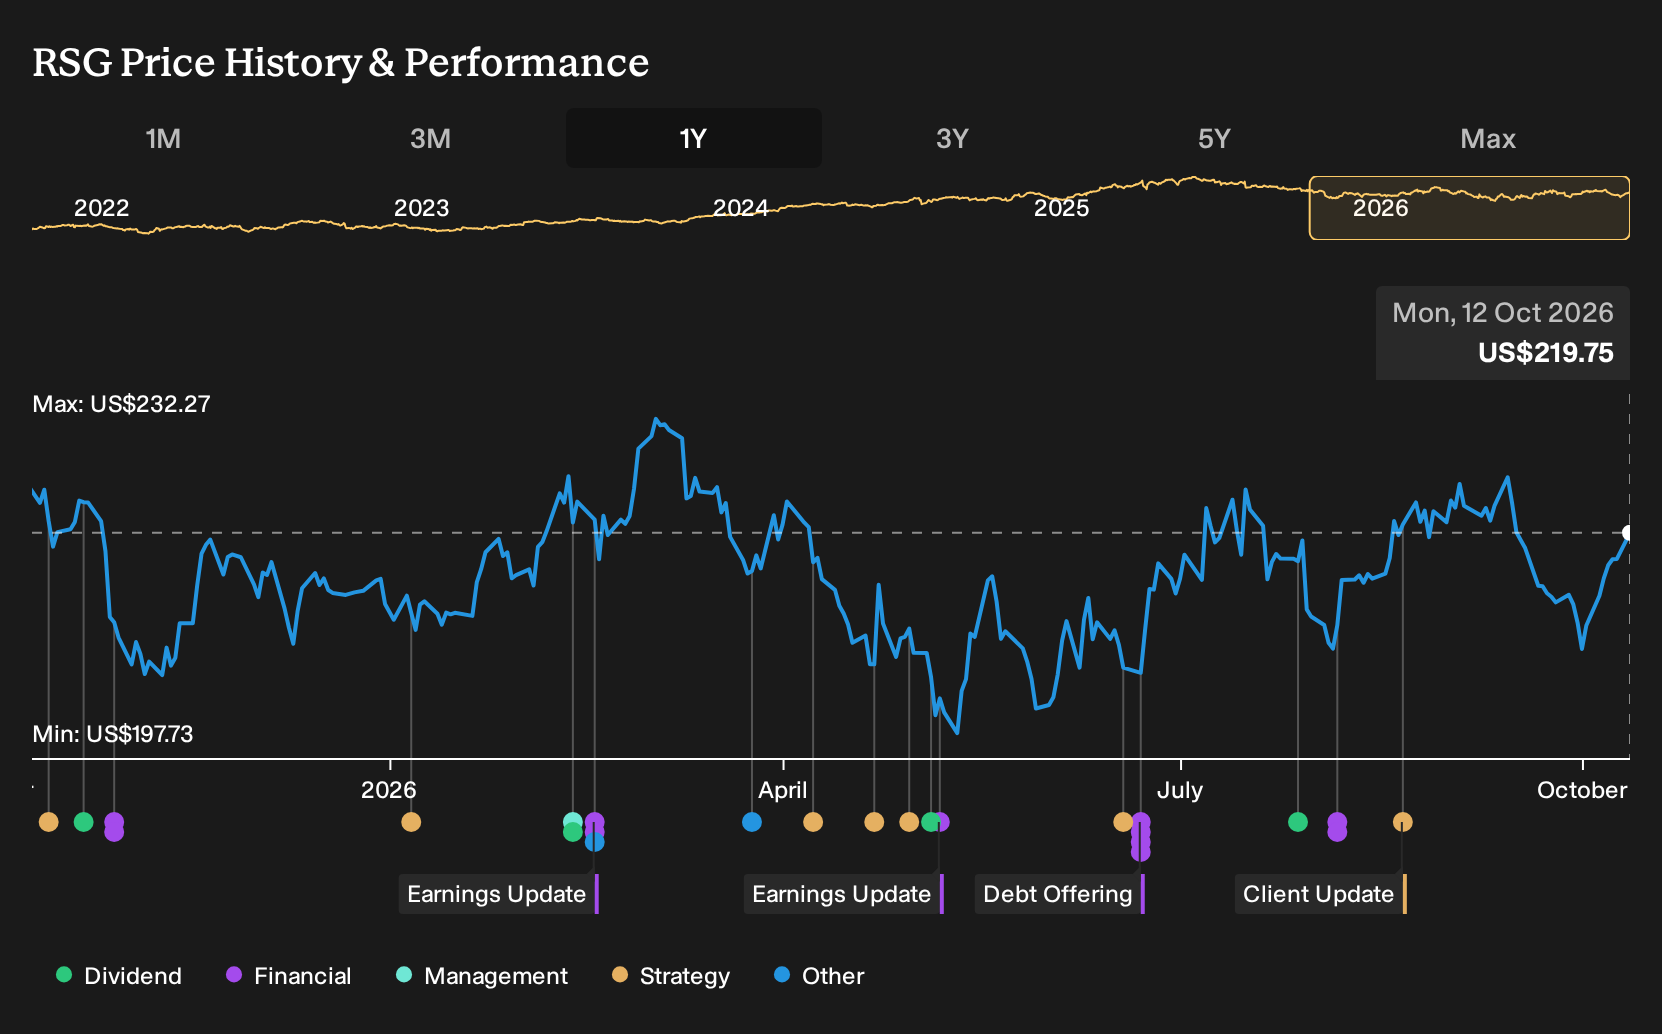
Uncover how Republic Services' fair value indicates a 12% potential upside to its current price before sentiment shifts and the gap compresses.
Exploring Other Perspectives
The Simply Wall St Community has only three fair value views on Republic Services, yet they already span a tight band from about US$244.50 to just under US$298. That small sample still hints at very different return expectations. When you overlay that with organic volume pressure, labor disputes and upcoming earnings, you should expect opinions to diverge further and it may be helpful to explore several alternative viewpoints before deciding how this story fits your own portfolio.
Explore 2 other Republic Services fair value estimates, including one that suggests as much as 36% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own independent view.
- A great starting point for your Republic Services research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Republic Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Republic Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond Republic Services?
Once you have a handle on Republic Services and its waste and recycling profile, it can be helpful to compare it with other listed companies that pair resilient balance sheets with different earnings drivers. The Simply Wall St Screener is built for that kind of side by side work.
- If you want a shortlist of resilient businesses with cleaner finances, start with our 31 resilient stocks with low risk scores that already screen well on stability and risk metrics.
- For investors hunting for a mix of financial strength and potential mispricing, the 29 high quality undervalued stocks can surface companies where quality metrics and valuation checks line up more attractively.
- Those who prefer to focus on less crowded opportunities can scan the 20 high quality undiscovered gems and see which solid operators are flying under most radars.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com