


Lululemon Athletica (LULU) has undertaken to shake up the senior leadership team, which seems to be happening at a critical time for the athletic apparel firm. Indeed, shares have declined more than 54% so far this year, and there were declines in revenue and comparable sales in the last quarter. With this, Lululemon has decided to create two new senior positions aimed at focusing more attention on product development and operational execution.
Maggie Gauger, who served as president and CEO of Athleta, will take the position of president and chief product officer starting Oct. 26. Joseph Godsey, who previously held the position of chief growth officer at Walmart Canada, will serve as the company’s chief operating officer on the same date. Gauger will be responsible for such departments as design, merchandising, footwear, and product innovation, while Godsey will oversee all operational issues like sourcing, production, fulfillment, planning, and others.
Such changes are seemingly quite timely since Lululemon attempts to address the problems with its products when the momentum in the Americas business is lacking.
About Lululemon Stock
Headquartered in Vancouver, Canada, Lululemon Athletica is a world-known athletic apparel company offering products like technical clothing, footwear, and accessories in such fields as yoga, running, and training. Lululemon’s current market capitalization stands at about $11 billion.
The share price, which stands now at $94.48, declined 54% year-to-date (YTD) and trades almost 58% below its 52-week high of $225.98. This is a huge difference in comparison with the general market environment. For comparison, the S&P 500 Index ($SPX) increased roughly 14% this year, thus Lululemon underperformed its benchmark by almost 68 percentage points.
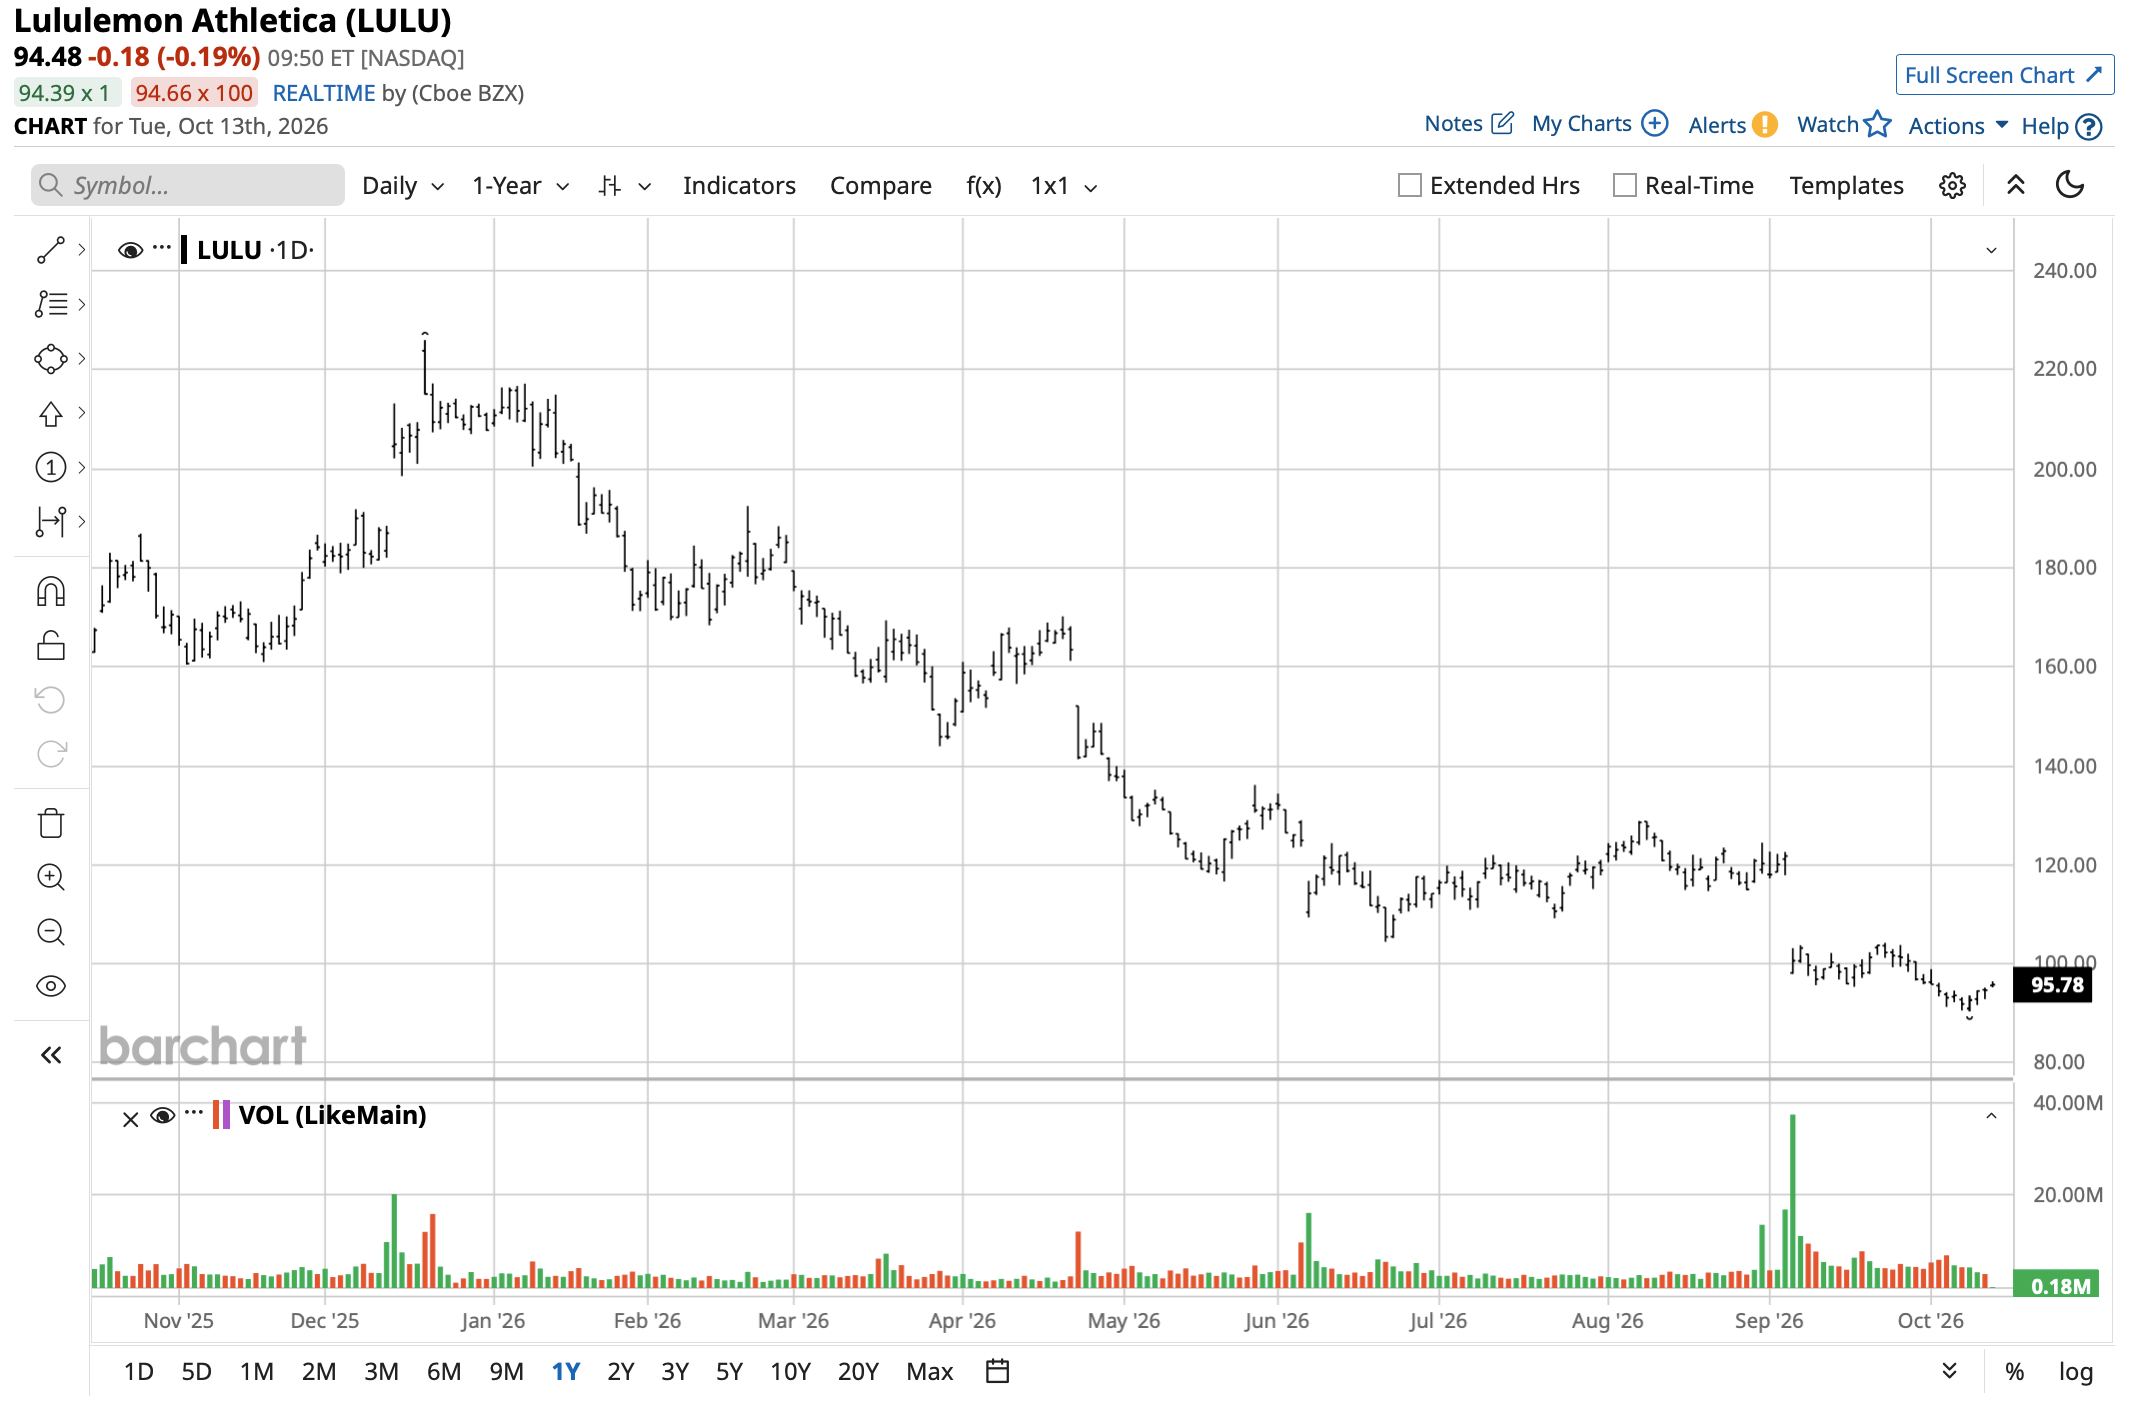
This decline has resulted in re-evaluation of the company. Shares of Lululemon are trading at roughly 9.7 times forward earnings and 0.99 times sales. These are very far from multiples, which could have been expected from such a premium growth story. In my opinion, the current valuation takes into account quite a lot of negativity, but that does not necessarily mean that Lululemon shares became cheap. The company must prove that the declining comparable sales can stabilize to make the current multiple quite attractive.
Lululemon Reports Lower Revenue but Beats on Earnings
The results of Lululemon's fiscal Q2 illustrate why the changes in the company’s senior leadership are quite relevant. Revenue decreased 4% year-over-year (YoY) to $2.4 billion, falling short of the expected $2.46 billion according to Wall Street consensus. There was the fall in global comparable sales by 9%, Americas’ revenue was down 8%, and Americas' comparable sales declined by 12%. Meanwhile, international revenue rose 4%.
There are some possibilities to monitor LULU's valuation, price performance, and technical indicators through the Barchart quote overview.
EPS was reported at $2.92, which is considerably better than the $1.79 consensus estimate but lower than $3.10 YoY. However, there is an important thing here. Lululemon received $134.5 million of tariff refunds along with interest income in the quarter, adding $0.86 to EPS. Gross margin increased 200 basis points to 60.5%, but the underlying margin without the 560-basis-point increase from the mentioned refund would have looked significantly weaker.
Management has also lowered its guidance. For the upcoming Q3, Lululemon expects revenues in the range of $2.29 billion to $2.32 billion, which is a 10% to 11% decline, while EPS range is between $0.93 and $0.98. For fiscal year 2026, management predicts revenues of $10.35 billion to $10.50 billion, which implies a decline of 5% to 7%, and EPS of $9.48 to $9.73.
Therefore, it looks like the current change in the company’s senior leadership is more than only cosmetic. Maggie Gauger’s new position unites design, merchandising, footwear, innovation, and materials science, while Joseph Godsey will be responsible for almost all operational chains from sourcing through fulfillment. Moreover, Lululemon looks for new chief brand, communications, and technology officers, while CFO Meghan Frank will temporarily oversee global brand and technology functions.
The company has not confirmed its next earnings release date yet; therefore, the suggested estimated date cannot be considered as scheduled.
What Do Analysts Think About LULU Stock?
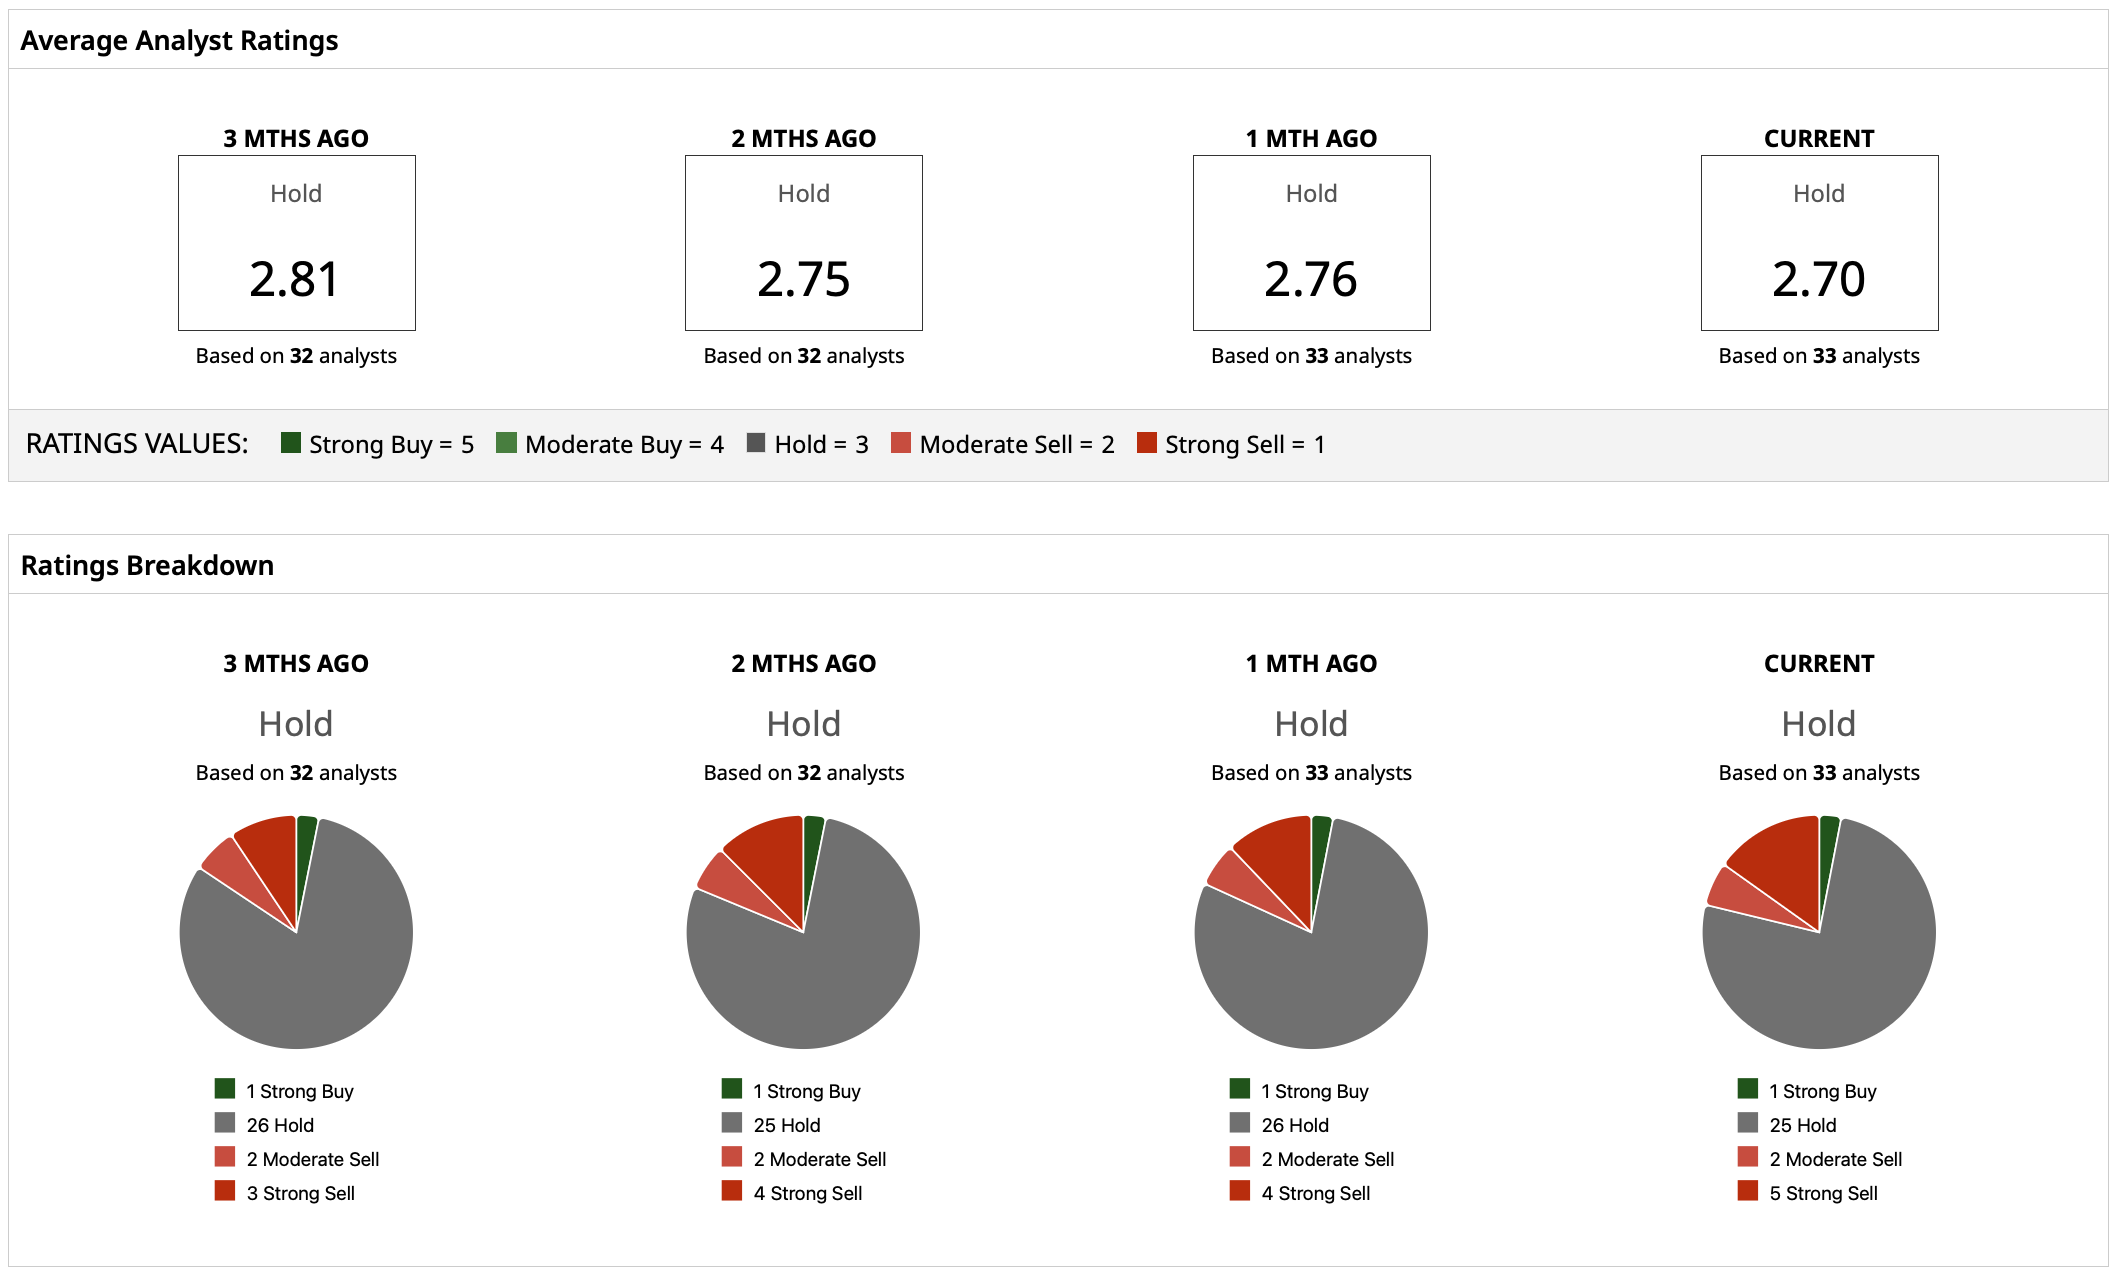
Street's attitude towards LULU stock appears to be quite cautious. LULU earns a “Hold” rating consensus based on 32 analysts versus the same “Hold” consensus three months ago. The underlying score declined from 2.81 three months ago to 2.70 presently, which means that the sentiment among analysts has actually become somewhat more bearish as the stock price falls. The high target price of analysts is $175, the mean target price is $100.96, and the low target price is $44. Thus, the mean target price of $100.96 implies the upside potential of approximately 6.9% from the current price of $94.48.
On the date of publication, Yiannis Zourmpanos did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.