


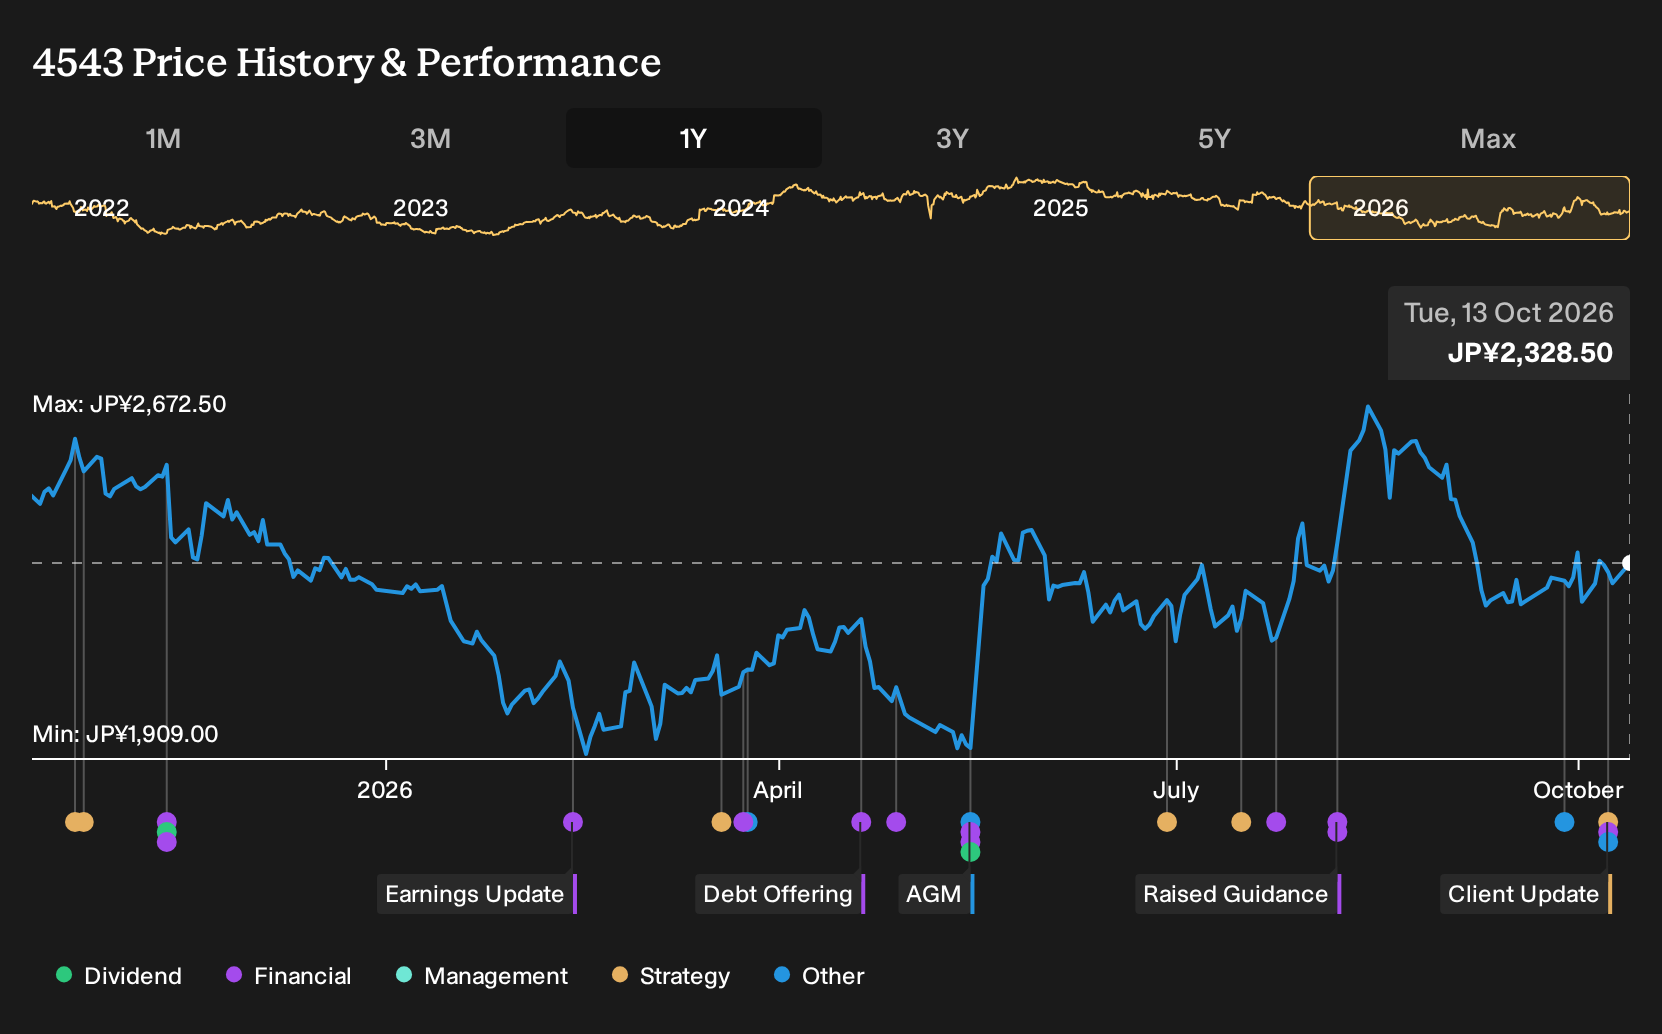
- Terumo Corporation announced in October 2026 that it will mutually terminate its source plasma collection supply agreement with CSL Plasma and has lowered full year 2027 guidance, now projecting revenue of ¥1,229,500 million, operating profit of ¥160,000 million and profit attributable to owners of parent of ¥120,000 million.
- The transition away from CSL Plasma is expected to carry an estimated US$610 million, or about ¥97.5 billion, financial impact, largely from non cash impairment on plasma related assets plus restructuring and transition costs that reshape Terumo’s Blood and Cell Technologies economics.
- Next, the focus shifts to how Terumo’s revised earnings guidance after the CSL Plasma termination could reshape its longer term investment narrative.
Terumo Investment Narrative Recap
To own Terumo, you need to believe its core cardiac, vascular, and medical care operations can keep doing the heavy lifting while Blood and Cell Technologies is reset. The lowered FY 2027 guidance points to a tougher near term earnings profile, with operating profit now projected at ¥160,000 million and EPS at ¥81.35.
The key short term swing factor is whether demand and pricing in core product lines can offset the CSL Plasma transition drag. The main risk is that tariffs, China pricing pressure, and restructuring related costs could combine to squeeze margins at the same time, leaving less room for execution missteps.
The most relevant update is Terumo’s revised FY 2027 outlook that incorporates the CSL Plasma exit. Management now guides to revenue of ¥1,229,500 million, operating profit of ¥160,000 million and profit attributable to owners of parent of ¥120,000 million, compared with earlier, higher profit targets.
This step effectively brings forward the financial impact from impairment, transition losses and restructuring into a defined window. For you as an investor, the key consideration is whether Terumo can expand higher margin consumables and procedure driven products sufficiently to absorb this reset while managing tariff, China VBP and FX headwinds.
What Terumo’s Long Term Forecasts Are Really Asking You To Underwrite
Terumo’s post CSL reset leaves you weighing near term friction against what analysts see as a cleaner earnings profile by the late 2020s. The consensus view sketches out a company leaning on steady procedure volumes, richer product mix and firmer margins rather than a single blockbuster driver.
Analysts currently assume Terumo’s top line can expand at about 6.8% a year over the next three years. Profitability is modeled to rise from a 13.9% margin today to 15.2% in three years, which effectively bakes in better pricing, more high margin consumables and some cost discipline. On earnings, the street is working off current profit of ¥164.5 billion and a central forecast of ¥218.9 billion by 2029, with the more optimistic end of the range at ¥242.3 billion.
Those numbers matter because they sit underneath the analyst price targets you often see quoted for Terumo. The consensus assumes that by 2029 the business will be generating about ¥1.4438 trillion in revenue and ¥218.9 billion in earnings. On those earnings, the stock would trade on a P/E of 24.4x, compared with 20.7x today and versus 16.2x for the wider JP medical equipment group.
In practical terms, the forecast path from ¥164.5 billion in profit today to ¥218.9 billion in 2029 implies an earnings increase of about ¥54.4 billion over that stretch. That is the step up analysts are effectively asking you to sign off on, layered on top of 6.8% annualised revenue growth and a richer margin profile.
Terumo's narrative projects ¥1.4438 trillion revenue and ¥218.9 billion earnings by 2029. This rests on revenue growing about 6.8% per year and an earnings increase of roughly ¥54.4 billion from current earnings of ¥164.5 billion.
Uncover why Terumo's fair value indicates a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You might see the CSL Plasma exit as a setback, yet the most optimistic Terumo analysts were leaning on CDMO expansion as a key upside catalyst. Before this news, they were sketching about ¥1,564.6b in 2029 revenue and ¥242.1b in earnings. Those pre shock views could shift, so compare them with your own expectations.
Explore another Terumo fair value estimate, including one that suggests potential upside of as much as 34% from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Terumo research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Terumo. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Terumo's overall financial health at a glance.
Looking for more investment ideas beyond Terumo?
Once you have a view on Terumo, it can help to line it up against other opportunities that fit different goals, whether you care most about value, resilience, or untapped potential.
- If you want a margin of safety and quality together, scan a curated set of 13 high quality undervalued stocks that pair stronger fundamentals with more modest pricing.
- For investors who put financial strength first, filter for companies on the list of solid balance sheet and fundamentals (21 results) and focus on businesses with sturdier capital structures.
- When you are hunting for future leaders before the crowd arrives, sort through the 74 high quality undiscovered gems and see which stories deserve a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com