


HSBC says a new competitive threat from a free-to-use creative software could make it challenging for Adobe (ADBE) shares to stage a meaningful comeback in 2027. Analyst Stephen Bersey downgraded ADBE this morning to “Hold” and lowered his price objective to $267, which nonetheless signals potential upside of about 12% from here.
Adobe stock has been an underperformer in 2026, currently down about 30% versus the start of this year.
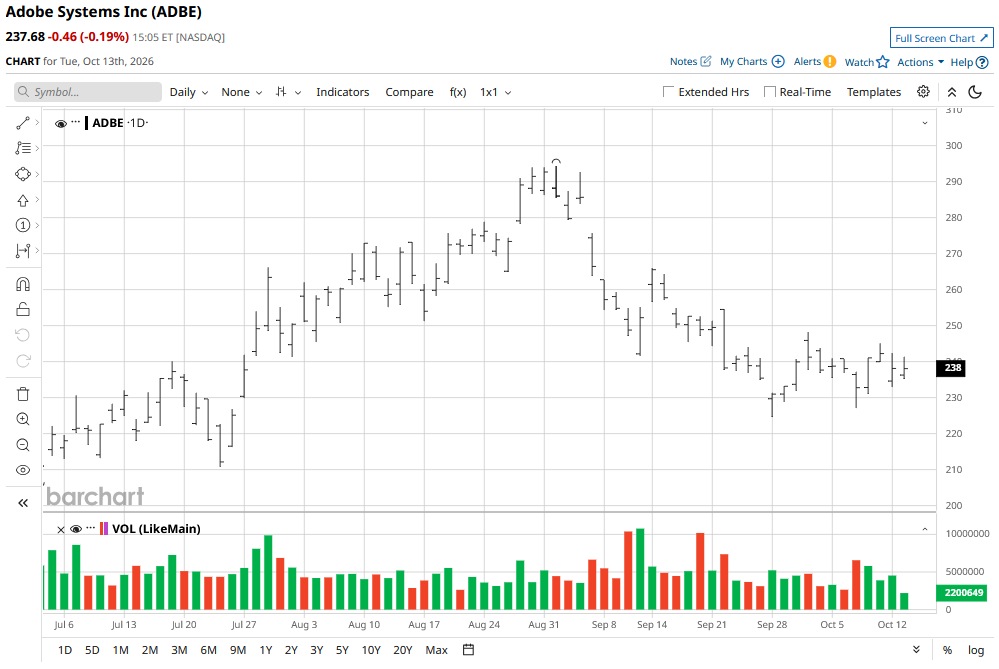
What Made HSBC Downgrade Adobe Stock
Bersey’s concerns follow reports that ArtCraft has released open-source alternatives to Adobe’s Creative Cloud applications. Its lineup spans tools corresponding to Photoshop, Illustrator, Premiere, Lightroom, Acrobat, After Effects, and InDesign.
According to the HSBC analyst, ArtCraft hopes to achieve “100% feature parity” within a month, a stated ambition rather than an established achievement. Bersey nevertheless lowered his earnings estimates to account for the possibility that some amateur users could leave Adobe.
The commercial risk for ADBE shares is rather straightforward; customers with modest creative needs may become harder to retain if a free alternative can handle enough of their everyday tasks.
What ArtCraft Really Means for ADBE Shares
Crucially, HSBC’s caution comes with qualifications. Bersey distinguished artificial intelligence (AI) assisted programming, where humans review the work, from largely autonomous coding with minimal oversight.
The analyst flagged security, legal, maintenance, and long-term viability concerns surrounding such projects, and advised against downloading ArtCraft.
For now, he expects ArtCraft’s appeal to concentrate among users drawn to free software and open-source enthusiasts. That limits the immediate competitive implications, but does not eliminate the headline risks for Adobe shares.
The investment concern goes beyond whether ArtCraft can replace professional workflows today: even an unproven challenger could reinforce doubts about ADBE's ability to keep customers paying as AI makes competing tools easier to build, the HSBC analyst concluded.
How Wall Street Recommends Playing Adobe
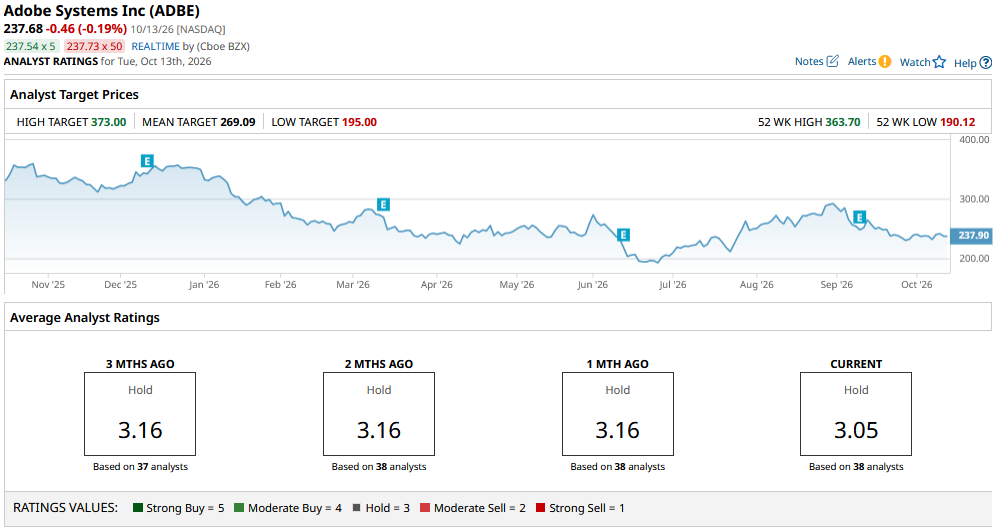
Other Wall Street firms aren’t particularly bullish on ADBE stock for the remainder of 2026 either.
The consensus rating on Adobe sits at “Hold” only, with the mean price target of $269 signaling potential upside of about 13% from current levels.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.