


- Emirates NBD recently introduced what it calls the UAE's first bank-led AI Travel Assistant, built with Visa and powered by Tripadvisor's travel content and cardholder perks, and made it available free to users without requiring a bank account or login.
- The partnership plugs Tripadvisor's review corpus and recommendations into a bank and payments ecosystem, which could extend the platform's reach into everyday customer journeys rather than just traditional trip planning touchpoints.
- We will now look at how this Emirates NBD AI Travel Assistant partnership might influence Tripadvisor's evolving experiences and AI investment narrative.
Scan how Tripadvisor fits into the AI travel shift alongside a curated 38 profitable AI stocks that aren't just burning cash that already pair real products with meaningful earnings power.
Tripadvisor Investment Narrative Recap
To own Tripadvisor, you need to believe the shift toward Experiences, Viator and AI trip planning can offset pressure in hotel meta and SEO heavy traffic. The Emirates NBD AI Travel Assistant fits that thesis, since it leans on Tripadvisor content inside a payments and banking channel, but on its own it does not change the near term picture.
The key swing factor in the short run remains whether Experiences can grow bookings and keep a roughly 10% adjusted EBITDA margin despite softer demand and higher cancellations that management has flagged. The biggest risk stays the same. Persistent SEO and AI overview headwinds could keep free traffic weak and force higher paid marketing, which would weigh on margins and earnings.
One of the more important recent moves around the Tripadvisor story has been the focus on Experiences, backed by US$4.7b of gross booking value in 2025 and a 10% adjusted EBITDA margin in that segment. The Emirates NBD partnership lines up with that, because it extends Tripadvisor content into a high intent environment where users are planning and paying for trips.
The same Experiences engine also leans heavily on repeat users, who now drive most of that gross booking value and form the fastest growing cohort. That is where AI travel assistants, app usage and rewards programs matter most. Execution risk sits in maintaining user trust as AI products and search summaries change how people find reviews, while still lifting unit economics and keeping acquisition costs in check.
Tripadvisor's current analyst framework points to revenues of US$1.7b and earnings of US$106.5 million by 2029, built on an assumed 2.3% yearly revenue decline and an earnings move from a loss of US$1.5 million today to that forecast profit level, which is an increase of about US$108 million.
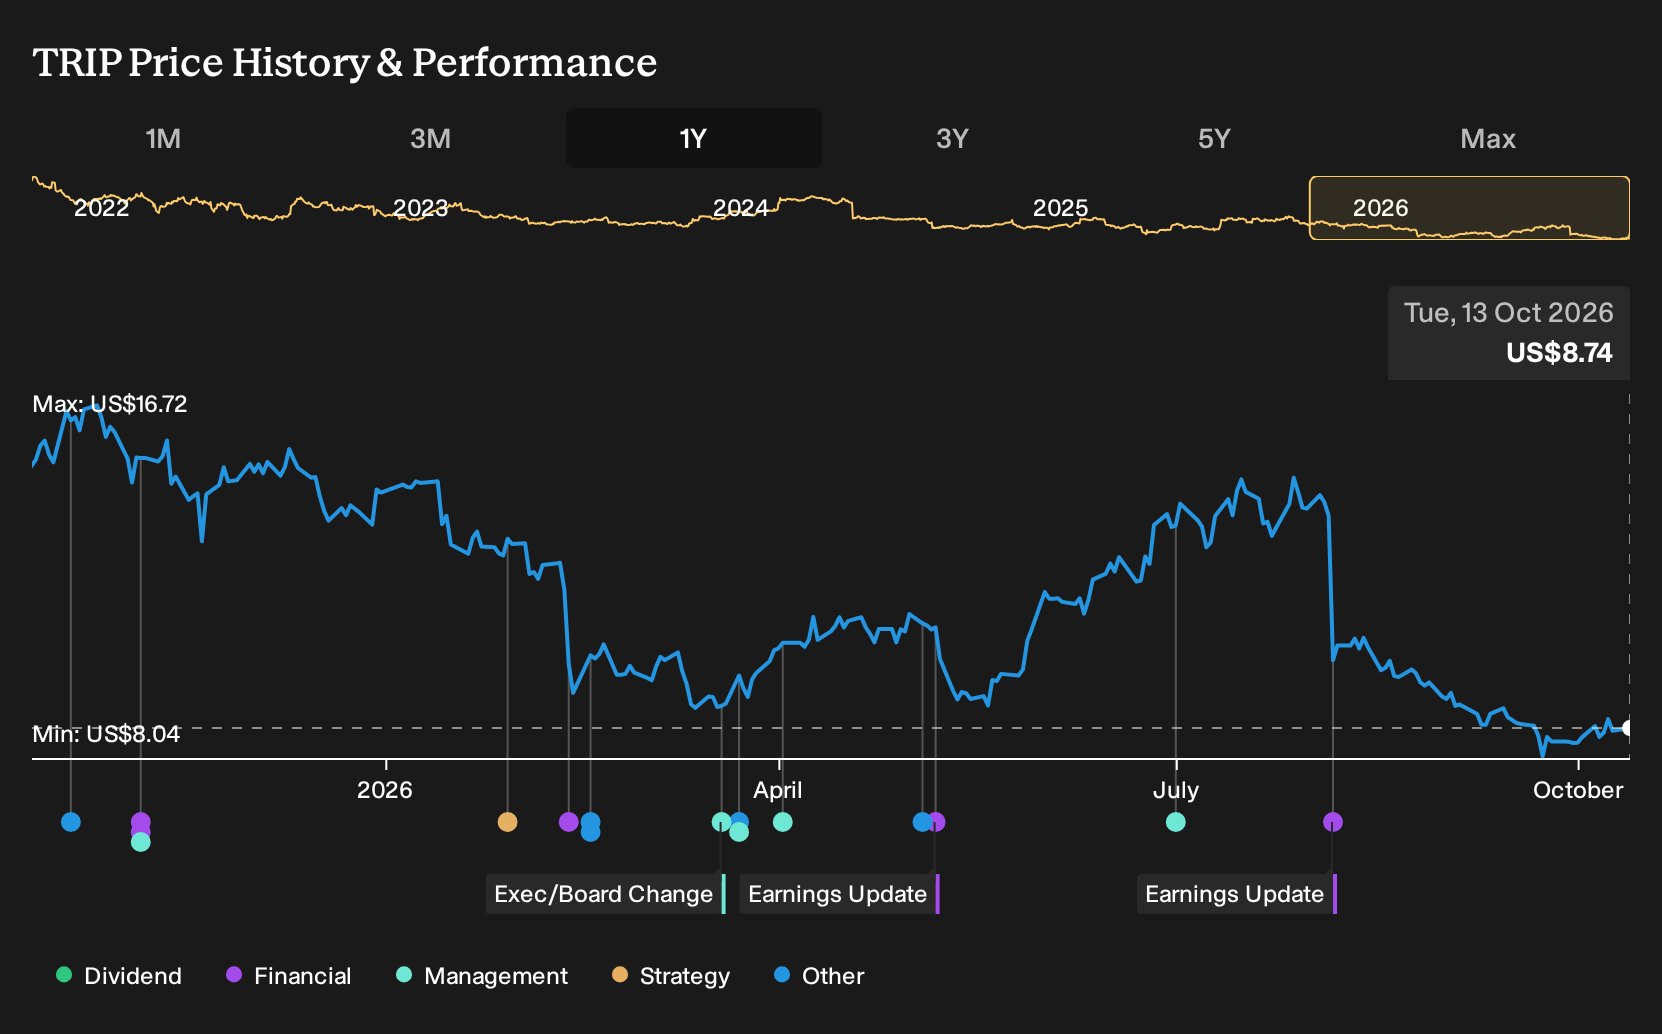
Uncover why Tripadvisor's fair value indicates a 57% potential upside to its current price, a gap that could narrow quickly in the view of some investors.
Exploring Other Perspectives
For Tripadvisor, the bullish twist centers on AI driven traffic rather than just Experiences mix. The most optimistic analysts were already penciling in about US$1.8b of revenue and US$187.4 million in earnings by 2029, compared with consensus nearer US$1.7b and US$106.5 million before this Emirates NBD AI Travel Assistant even arrived. You can treat this new partnership as a prompt to compare those very different narratives and decide which assumptions feel closer to your own view.
Explore 3 other Tripadvisor fair value estimates, including one that suggests as much as 221% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Tripadvisor research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Tripadvisor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tripadvisor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Tripadvisor?
If the Tripadvisor story has you thinking about what else might fit your portfolio, the Simply Wall St Screener can help you line up other opportunities that match your risk and return preferences.
- For investors who want resilient balance sheets and cleaner fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can help you focus on financial strength first.
- If you care most about stability and a smoother ride, filter for companies with steadier risk profiles by checking out a 31 resilient stocks with low risk scores tailored to that goal.
- For readers hunting for less crowded ideas with stronger fundamentals, scan a 20 high quality undiscovered gems and see which businesses deserve a spot on your watchlist.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com