


Amid the backdrop of fluctuating oil prices and geopolitical tensions impacting global markets, Asian equities have presented a diverse landscape for investors. As small-cap indices like the Russell 2000 experience mixed performance, discerning investors may find opportunities in lesser-known stocks that demonstrate resilience and potential for growth in this dynamic environment.
Top 10 Undiscovered Gems With Strong Fundamentals In Asia
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Ad-Sol Nissin | NA | 7.22% | 15.60% | ★★★★★★ |
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Yahagi ConstructionLtd | 19.18% | 12.68% | 22.27% | ★★★★★★ |
| SPRIX | 13.12% | 6.95% | -5.71% | ★★★★★★ |
| Xiamen King Long Motor Group | 93.39% | 11.34% | 66.65% | ★★★★★☆ |
| Delijia Transmission Technology (Jiangsu)Ltd | 7.09% | 14.57% | 15.98% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Shengda ResourcesLtd | 57.58% | 8.61% | 9.90% | ★★★☆☆☆ |
| HANA Micron | 137.37% | 21.15% | 26.62% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Sichuan New Energy Power (SZSE:000155)
Simply Wall St Value Rating: ★★★★★☆
Overview: Sichuan New Energy Power Company Limited operates in China, focusing on wind power, photovoltaic power, and waste-to-energy power generation with a market capitalization of CN¥19.44 billion.
Operations: The company generates revenue primarily from wind power, photovoltaic power, and waste-to-energy power generation activities in China. It has a market capitalization of CN¥19.44 billion.
Sichuan New Energy Power, a promising player in the renewable energy sector, has shown impressive growth with earnings surging by 126% over the past year. This outpaces the broader industry trend of -5.5%. The company is trading at a good value, estimated to be 71.8% below its fair value compared to peers. Its net debt to equity ratio stands at a satisfactory 36.1%, reflecting sound financial health. Recent financials highlight robust sales of CNY 3,323 million and net income of CNY 706 million for H1 2026, alongside an approved interim dividend of CNY 0.26 per share for shareholders.
- Navigate through the intricacies of Sichuan New Energy Power with our comprehensive health report here.
Understand Sichuan New Energy Power's track record by examining our Past report.

ZYNP (SZSE:002448)
Simply Wall St Value Rating: ★★★★★★
Overview: ZYNP Corporation is involved in the research, development, manufacture, and sales of automotive components both in China and internationally, with a market capitalization of CN¥6.34 billion.
Operations: The company's primary revenue stream is from Auto Parts Manufacturing, generating CN¥3.91 billion. The net profit margin shows a notable trend at 4.5%.
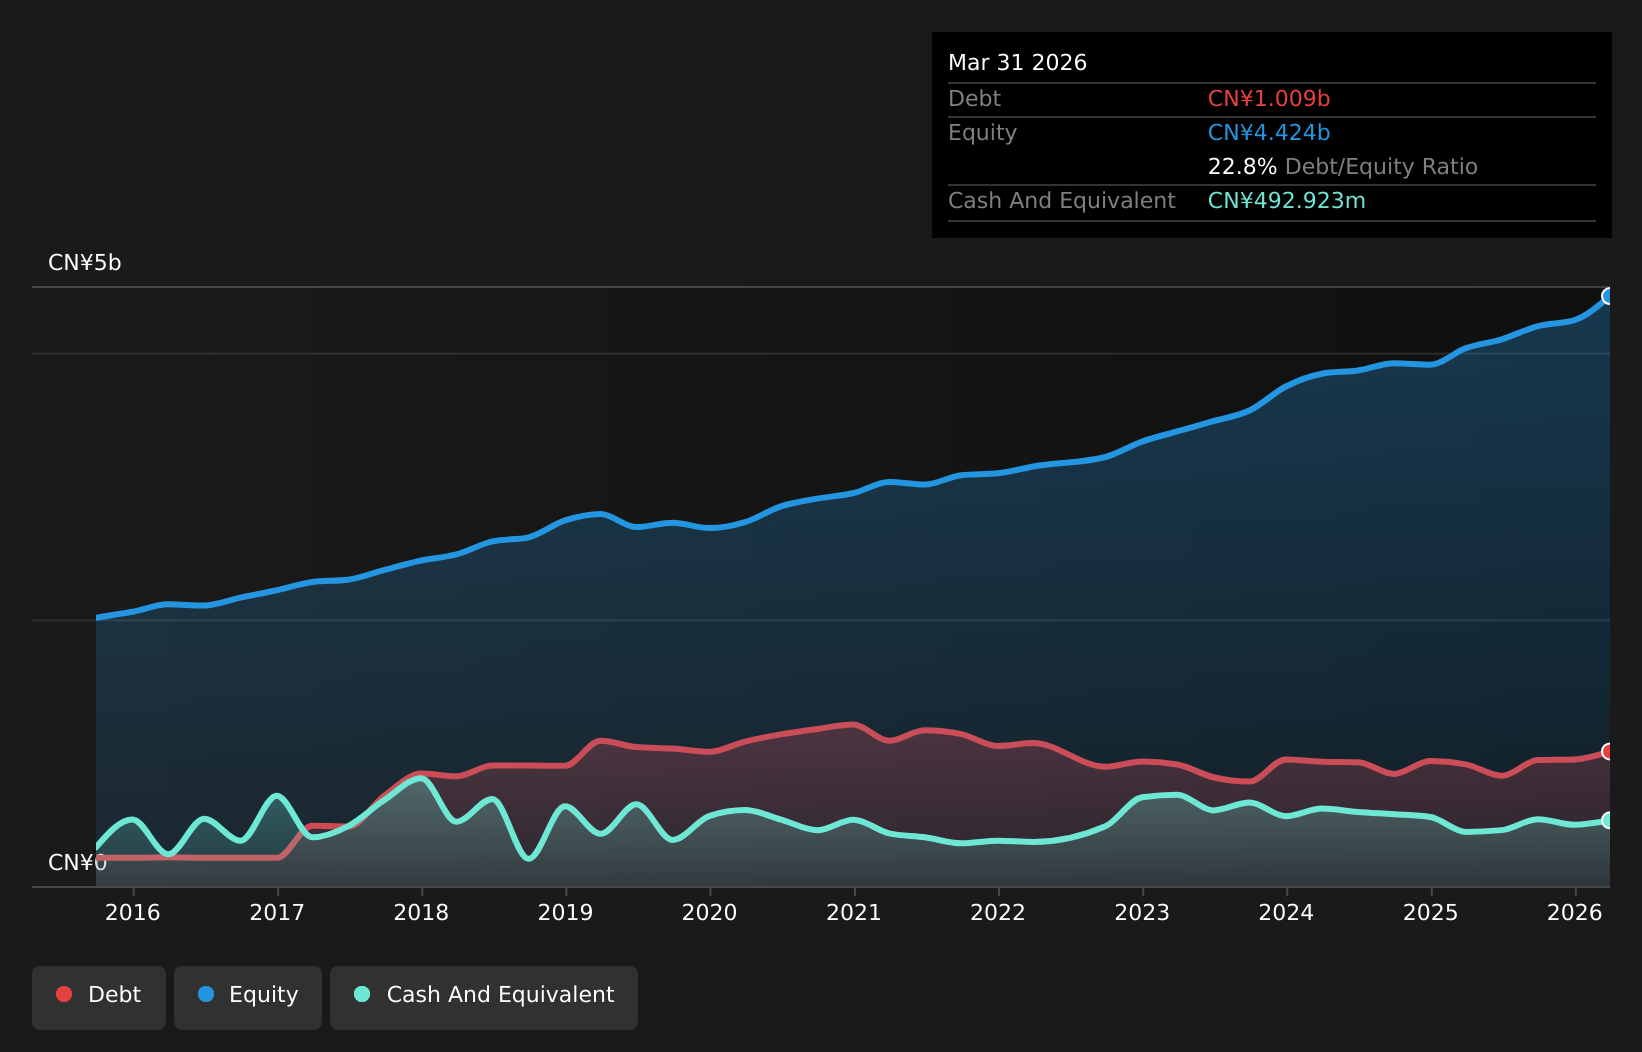
ZYNP, a promising player in the auto components sector, has shown impressive growth with earnings surging by 100.2% over the past year, outpacing the industry's modest 1.2%. The company is trading at a good value compared to its peers and is currently priced 26.6% below its estimated fair value. Financial health appears robust with a net debt to equity ratio of 9.5%, deemed satisfactory, and interest payments well covered by EBIT at an impressive 102.6 times coverage. Recent half-year results reveal sales climbing to CNY 2.40 billion from CNY 1.87 billion last year, alongside net income rising to CNY 346 million from CNY 234 million previously reported.
- Dive into the specifics of ZYNP here with our thorough health report.
Explore historical data to track ZYNP's performance over time in our Past section.
Chenming Electronic Tech (TWSE:3013)
Simply Wall St Value Rating: ★★★★★★
Overview: Chenming Electronic Tech. Corp., an OEM/ODM manufacturer, focuses on the research and development, manufacturing, and sale of computer and server cases, server chassis, mobile device components, and molds across Taiwan, China, the United States, and internationally with a market cap of NT$19.48 billion.
Operations: The company generates revenue primarily from the production and sales of computer and mobile device components, amounting to NT$11.67 billion.
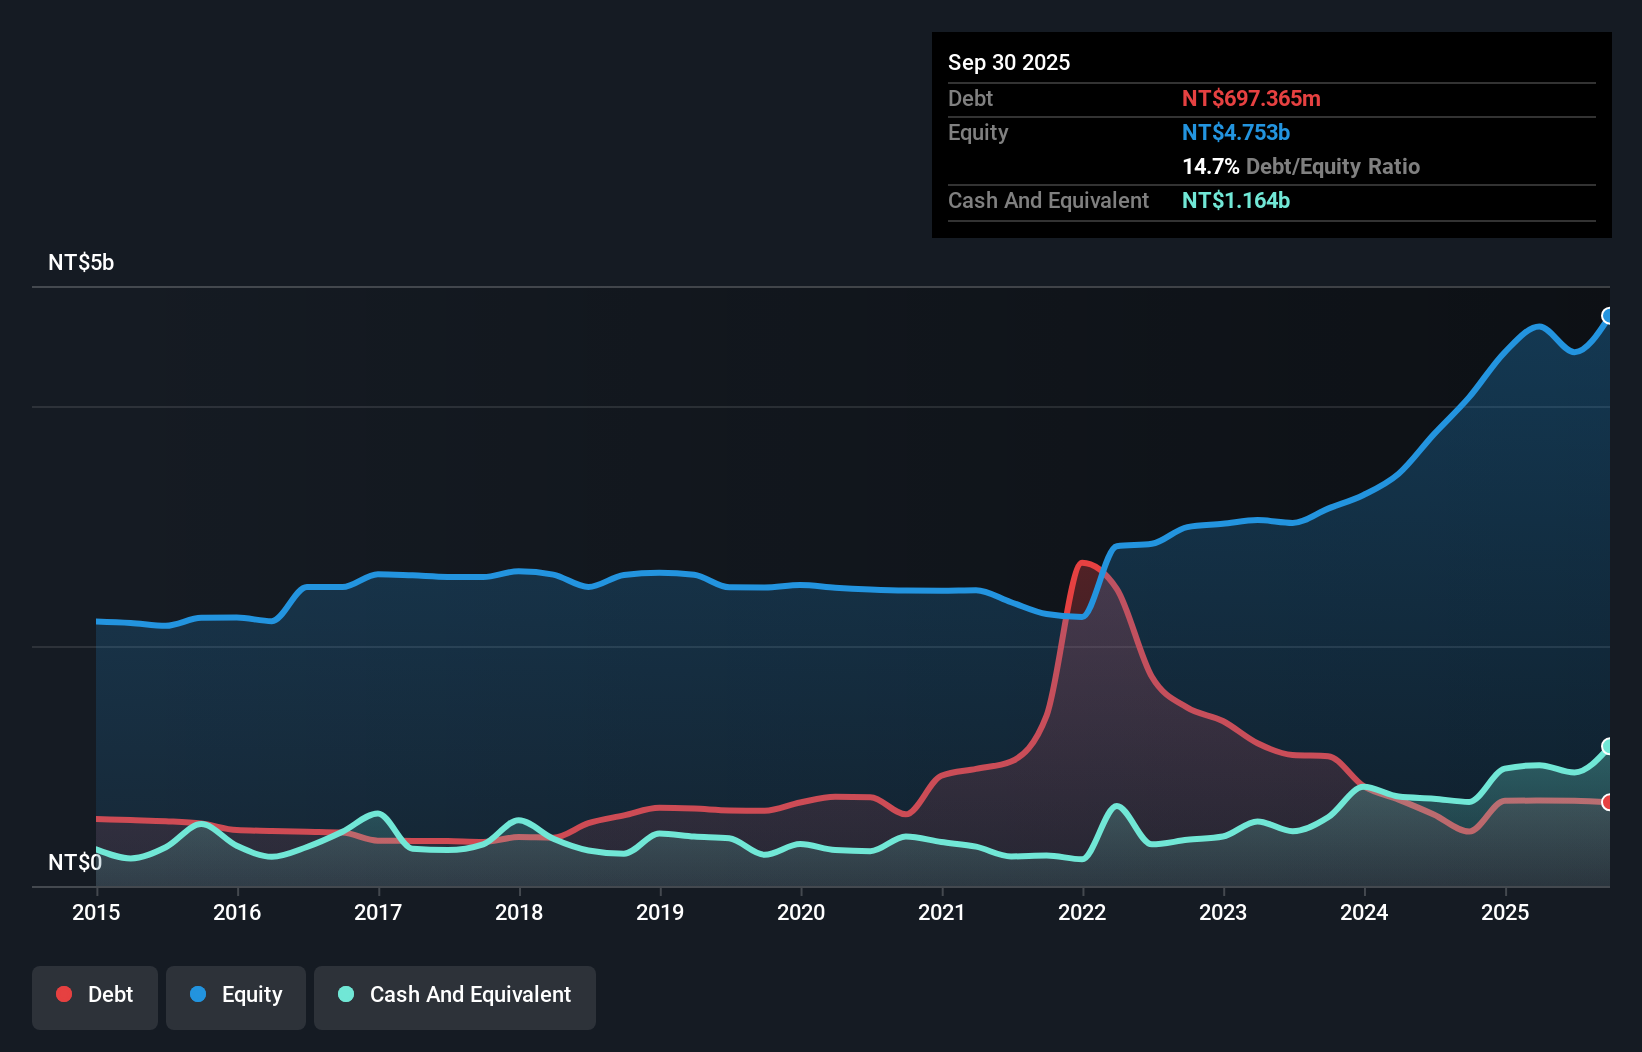
Chenming Electronic Tech, a notable player in the tech sector, has demonstrated robust financial performance. Its net income surged to TWD 289.63 million in Q2 2026 from TWD 111.66 million the previous year, reflecting strong earnings growth of 49.5% over the past year and outpacing industry averages. The company's debt to equity ratio improved significantly from 43.9% to just 13% over five years, indicating prudent financial management and a solid balance sheet with more cash than total debt. Trading at nearly 89% below its estimated fair value suggests potential for future appreciation despite its small market capitalization.
Turning Ideas Into Actions
- Click this link to deep-dive into the 116 companies within our Asian Undiscovered Gems With Strong Fundamentals screener.
- Shareholder in one or more of these companies? Ensure you're never caught off-guard by adding your portfolio in Simply Wall St for timely alerts on significant stock developments.
- Invest smarter with the free Simply Wall St app providing detailed insights into every stock market around the globe.
Want To Explore Some Alternatives?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com