


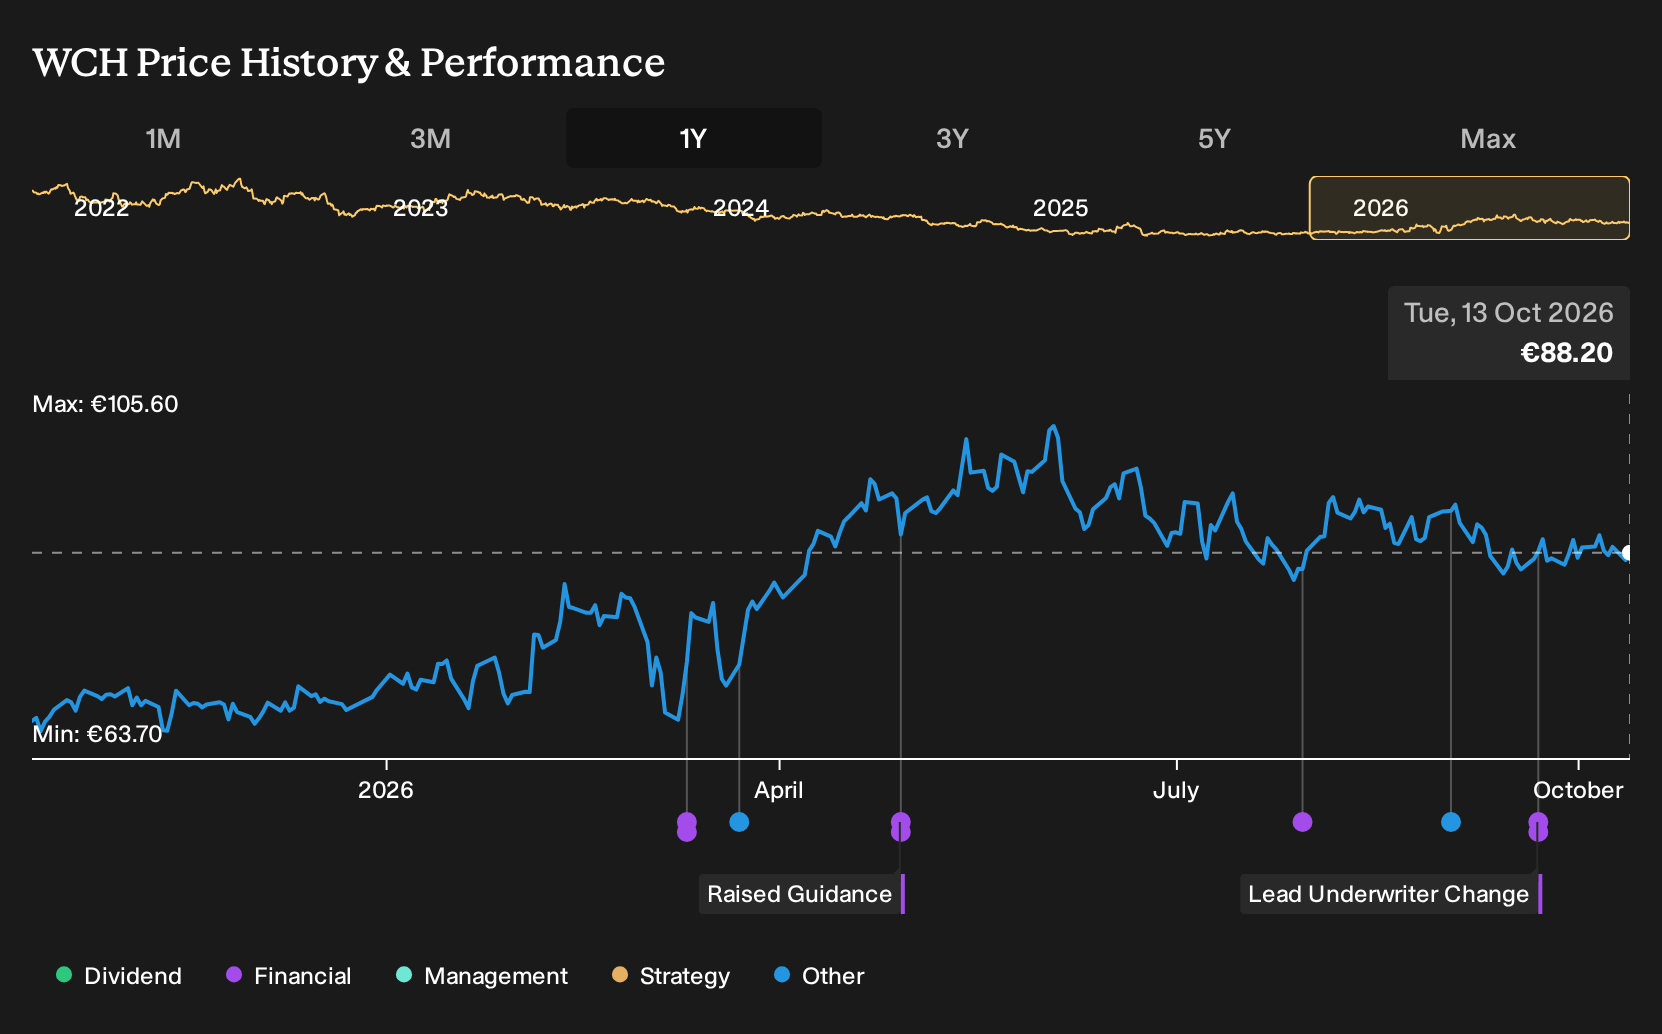
If you had seen Wacker Chemie in October 2025, with bulls pointing to polysilicon build outs and bears warning about emission costs and overcapacity, the choice probably did not feel easy. For Wacker Chemie shareholders, the return over the past year was 38.5%, including dividends. If you were weighing those conflicting narratives back then, which signals would have carried more weight than the noise around energy policy, capacity, and carbon costs?
If the move has made Wacker Chemie harder to judge, start where the gap is still open and scan 185 high quality undervalued stocks.
The Two Wacker Chemie Stories Investors Were Paying For
The shares cost €65.5 at the start of the period, and Wacker Chemie sat between two sharply different but credible stories.
On the optimistic side, the bullish view put Fair Value at €71.64, a rough guide to what that forecast implied the price could be worth, based on revenue growth of 3.1% and a future P/E of 13.6x supported by polysilicon and renewable energy spending.
The bearish narrative pointed to a Fair Value of €52, built on concerns that rising emission costs, global overcapacity and soft demand in key chemical segments would pressure margins and cash generation.
What The Results Changed For The Wacker Chemie Debate
The clearest new fact was Wacker Chemie’s swing in Q2 2026 from a net loss of €24.2 million a year earlier to net income of €340.8 million, with net margin moving from 1.7% in the red to 22.5%. That scale of profitability shift supported the bullish case that argued margins could improve, although cost and demand risks in the news kept the cautious perspective in focus. Overall, the evidence cut both ways.
The lesson is simple. When a thesis depends on better profitability, track net margin and absolute earnings against the original assumptions, not just revenue or headlines about new projects.
What Wacker Chemie’s Price Already Bakes In
Today Wacker Chemie trades at €88.2 after a 38.5% gain over the past year, while the selected Narrative’s Fair Value sits below the current price.
The Narrative argues that at this level you are paying for PACE and REFOCUS to lock in leaner costs, despite execution questions in biosolutions and ongoing energy and polysilicon pressures.
"The main thing that has to go right is that Wacker Chemie converts its PACE and REFOCUS programs into lasting cost savings and higher quality earnings, while keeping CapEx below depreciation to lift ROCE above 10%. The current valuation implies that Wacker Chemie already delivers its targeted structural EBITDA margin and ROCE improvements, despite ongoing overcapacity and demand headwinds in several key end markets."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Beyond Wacker Chemie’s Immediate Cycle
Looking one step away from Wacker Chemie raises a different raw material question. Polysilicon and specialty chemicals need capital, but so do metals enabling clean energy build outs.
Silver keeps appearing in electrification, from solar panels to power electronics and grid equipment.
One miner concentrates on finding and developing that metal, drilling new zones and expanding resources around existing shafts.
It combines exploration with operating producing sites, while also selling finished bullion directly to end buyers at a premium.
If clean energy demand remains focused on silver rich hardware, that mix of mining, expansion and direct sales could become more strategically important.
The argument comes with a number attached. → Uncover the silver company trading 46% below one Narrative's Fair Value
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com