


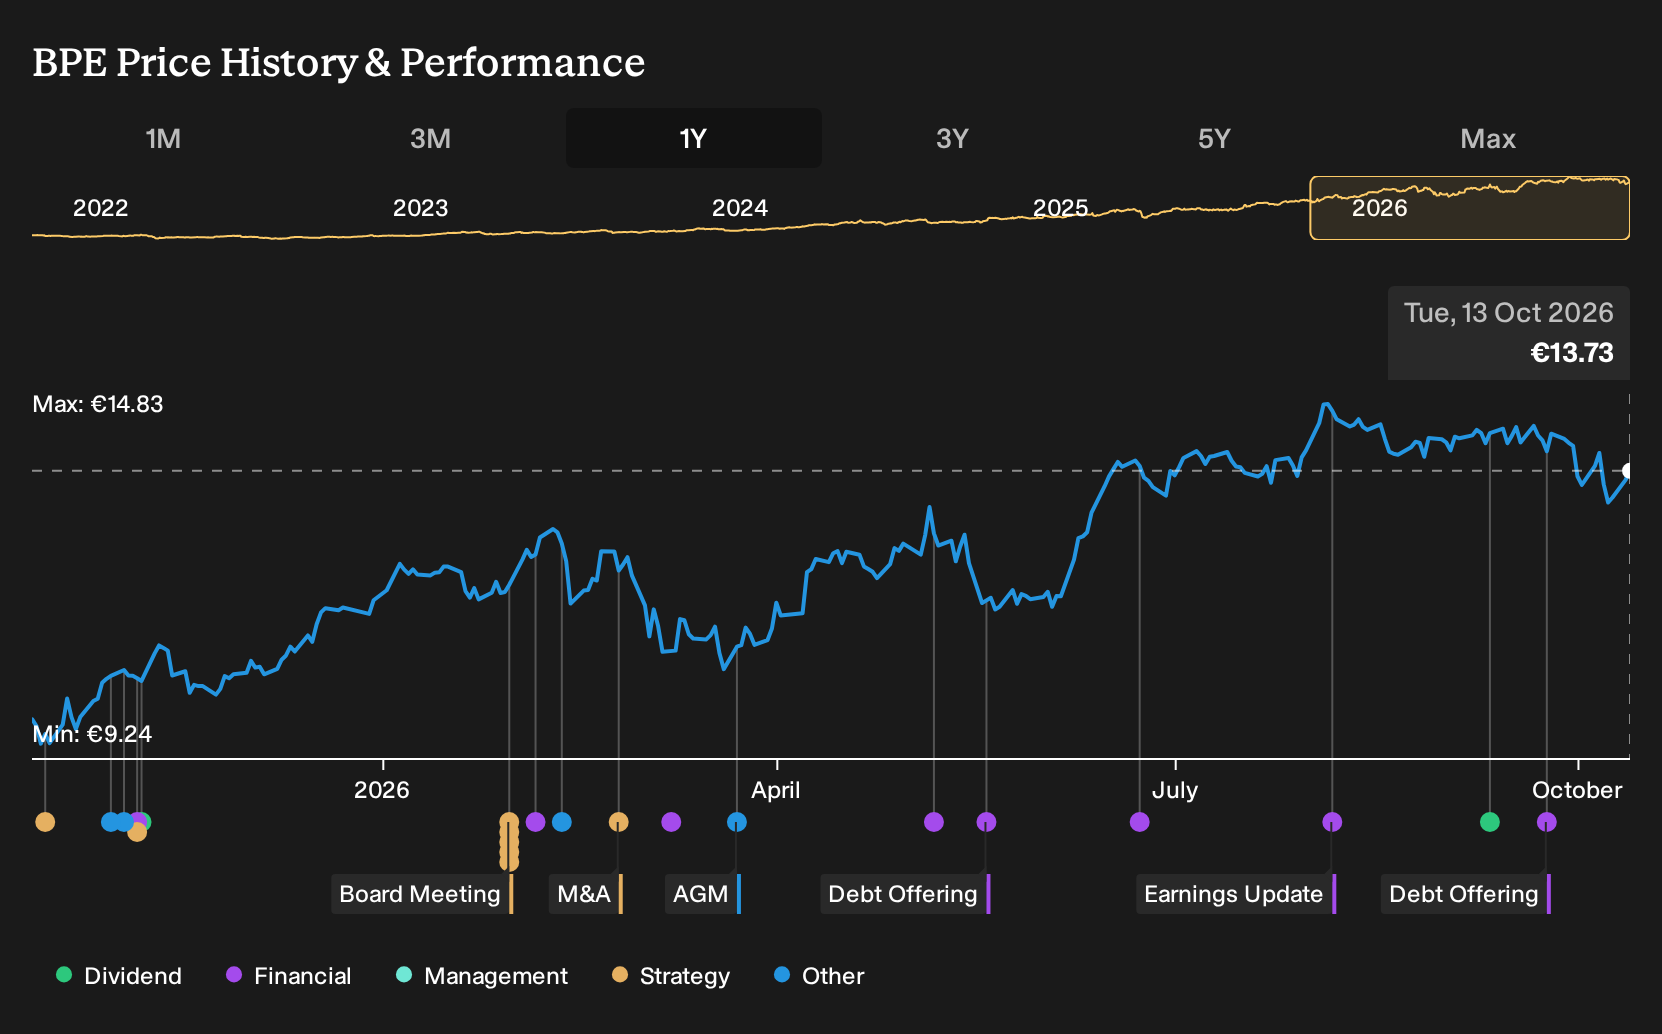
For BPER Banca shareholders, the return over the past year was 52.6%, including dividends. If you had been deciding on 13 October 2025 whether to buy, hold, or walk away, that outcome would now be hard to ignore. At the time, bulls were arguing that digital transformation, ESG lending, and the Sondrio integration could support expansion. Critics, on the other hand, flagged Italy concentration and merger risk. Which of those competing stories looked stronger based only on what was on record then?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind BPER Banca. Zero in on 185 high quality undervalued stocks for companies trading below our estimates.
The Two BPER Banca Stories Investors Had To Weigh
The shares cost €9.64 at the start of the period, and the debate around BPER Banca revolved around how far digital banking and ESG lending could shift its earnings profile.
The bullish Narrative put Fair Value at €10.57, assuming revenue growth of 11.9% a year and profit margins rising to 32.7% over roughly three years.
The bearish side set Fair Value at €7.55, working off a softer 5.4% revenue growth assumption and margin pressure toward 30.2% as integration and regulatory costs bit.
What The Results Changed For The BPER Banca Debate
The completion of the Banca Popolare di Sondrio merger and Q1 2026 profit of €549 million supported the bullish view that integration and fee income mattered for BPER Banca. Q2 2026 revenue of €1,951.676 million and net income of €758.056 million, with net margin rising to 38.8%, also leaned toward the optimistic margin story. ECB rate uncertainty cut the other way, so the evidence largely supported the optimistic case but not cleanly.
The key lesson is clear: when a thesis leans on integration and profitability, you track post deal revenue, absolute profit and net margin, and compare them to what management guided and what the Narrative assumed.
What BPER Banca’s Run Now Prices In
BPER Banca trades at €13.73, after a 52.6% gain over the past year, and the selected Narrative’s Fair Value sits above the current price rather than below it. That view leans heavily on faster profitability improvement and capital distribution than generic sector peers.
Instead of chasing the move, you would be judging whether BPER Banca can keep converting merger integration, digital banking, and ESG lending into stronger, fee-rich earnings that support more generous capital returns than consensus currently assumes.
"The doubling of new ESG lending volumes in a single quarter and strong push into wealth management, life insurance, and bancassurance products align BPER to benefit more than peers from the growing demand for sustainable finance and retirement solutions, providing a high-quality, fee-rich, and resilient income stream even as rates normalize."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 46% below our estimate - targets online bettors migrating from physical venues through proprietary gaming technology and marketing efficiency.
- Company 2 - 44% below our estimate - shifts mine plans toward higher grade ore bodies to lift output while lowering unit costs.
- Company 3 - 42% below our estimate - sells expert science and engineering opinions when regulators, courts, and boards confront complex technical failures.
Three companies from the same screener. Open the full list of 204 financially solid companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com