


Koninklijke KPN (ENXTAM:KPN) has reshaped its leadership bench, naming Wouter Stammeijer as incoming CFO and Vladimir Cibic as future CTO from 1 November 2026, alongside changes to the composition of the Supervisory Board.
Against this leadership reshuffle, Koninklijke KPN’s share price has eased in recent months, with a 30-day share price return down 4.5% and a 90-day share price return down 9.9%, while the 5-year total shareholder return of 79.2% reflects a stronger performance over a longer period for investors.
Scan how investors are reacting to leadership shifts like those at Koninklijke KPN’s by reviewing our handpicked 225 resilient stocks with low risk scores that aim to balance stability with potential upside.
Koninklijke KPN shares have slipped in the short term while longer term returns remain positive, and leadership is being refreshed at the top. Does that recent dip still offer an appealing risk reward for new buyers as valuation comes into focus next?
Most Popular Narrative: 15% Undervalued
On the latest close at €3.90, the leading valuation narrative puts Koninklijke KPN closer to €4.57 per share, which frames the recent share price softness as a gap between market pricing and that estimate.
The StoxEurope estimate for Royal KPN is €4,57 per share, as at 5 October 2026. The share price that day was €3,97. One number needs a range around it. Our three scenarios run from €3,44 to €5,41:
• Competition bites (€3,44): revenue grows 0,5 % a year and the operating margin slips to 22 %.
• The plan holds (€4,57): revenue grows 2 % a year and the margin stays at 24 %.
• Fibre pays off (€5,41): revenue grows 3 % a year and the margin rises to 25,5 %.
See why 1 investors see Koninklijke KPN as 15% undervalued.
Result: Fair Value of €4.57 (UNDERVALUED)
Still, the Koninklijke KPN story can be knocked off course if pricing pressure intensifies in Dutch telecom or if regulatory shifts raise long term costs.
Find out about the key risks to this Koninklijke KPN narrative.
Another View: Multiples Paint A Richer Price Tag
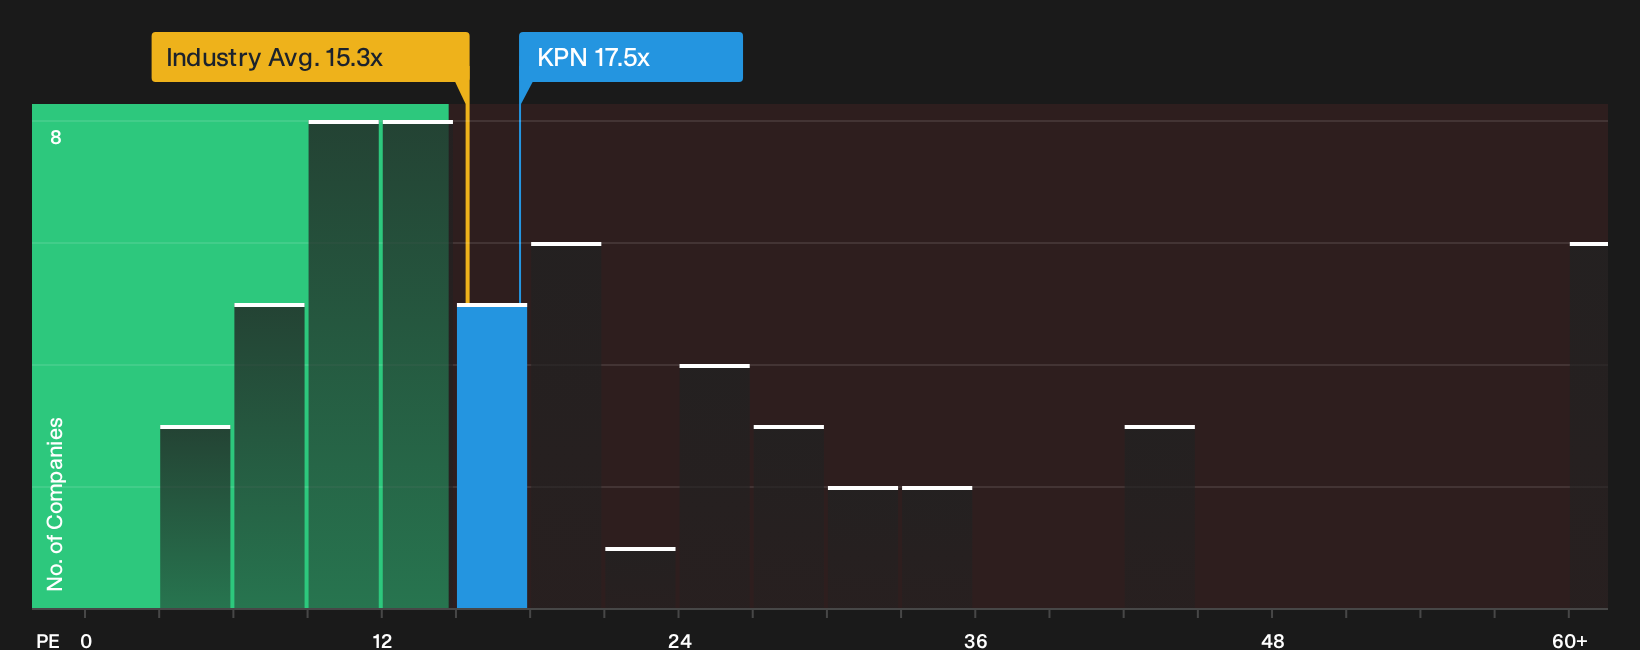
Look past the discounted cash flow work and a different picture of Koninklijke KPN appears. On a P/E of 17.5x, the shares trade above both the direct peer average at 16.9x and the wider European telecom group at 15.3x. This tilts the story toward valuation risk rather than a clear bargain.
These richer earnings multiples mean investors are already paying a premium for each euro of profit, even as revenue and earnings forecasts point to slower growth than the Dutch market. The question is simple: does that premium feel comfortable when other telecom stocks and the wider market are priced lower?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and risk can feel messy at first glance, so move fast, review the numbers independently, and weigh both sides of the Koninklijke KPN story using the 4 key rewards and 1 important warning sign.
Looking for more ideas beyond Koninklijke KPN?
If Koninklijke KPN has sharpened your focus on valuation and risk, keep that momentum and use screeners to uncover fresh opportunities that match your approach.
- Target potential mispricing by running through our high quality value candidates using the 185 high quality undervalued stocks.
- Strengthen your income tilt by reviewing companies with robust payouts via the 223 dividend fortresses.
- Prioritise resilience by filtering for financially sturdy businesses in the list of solid balance sheet and fundamentals (204 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com