


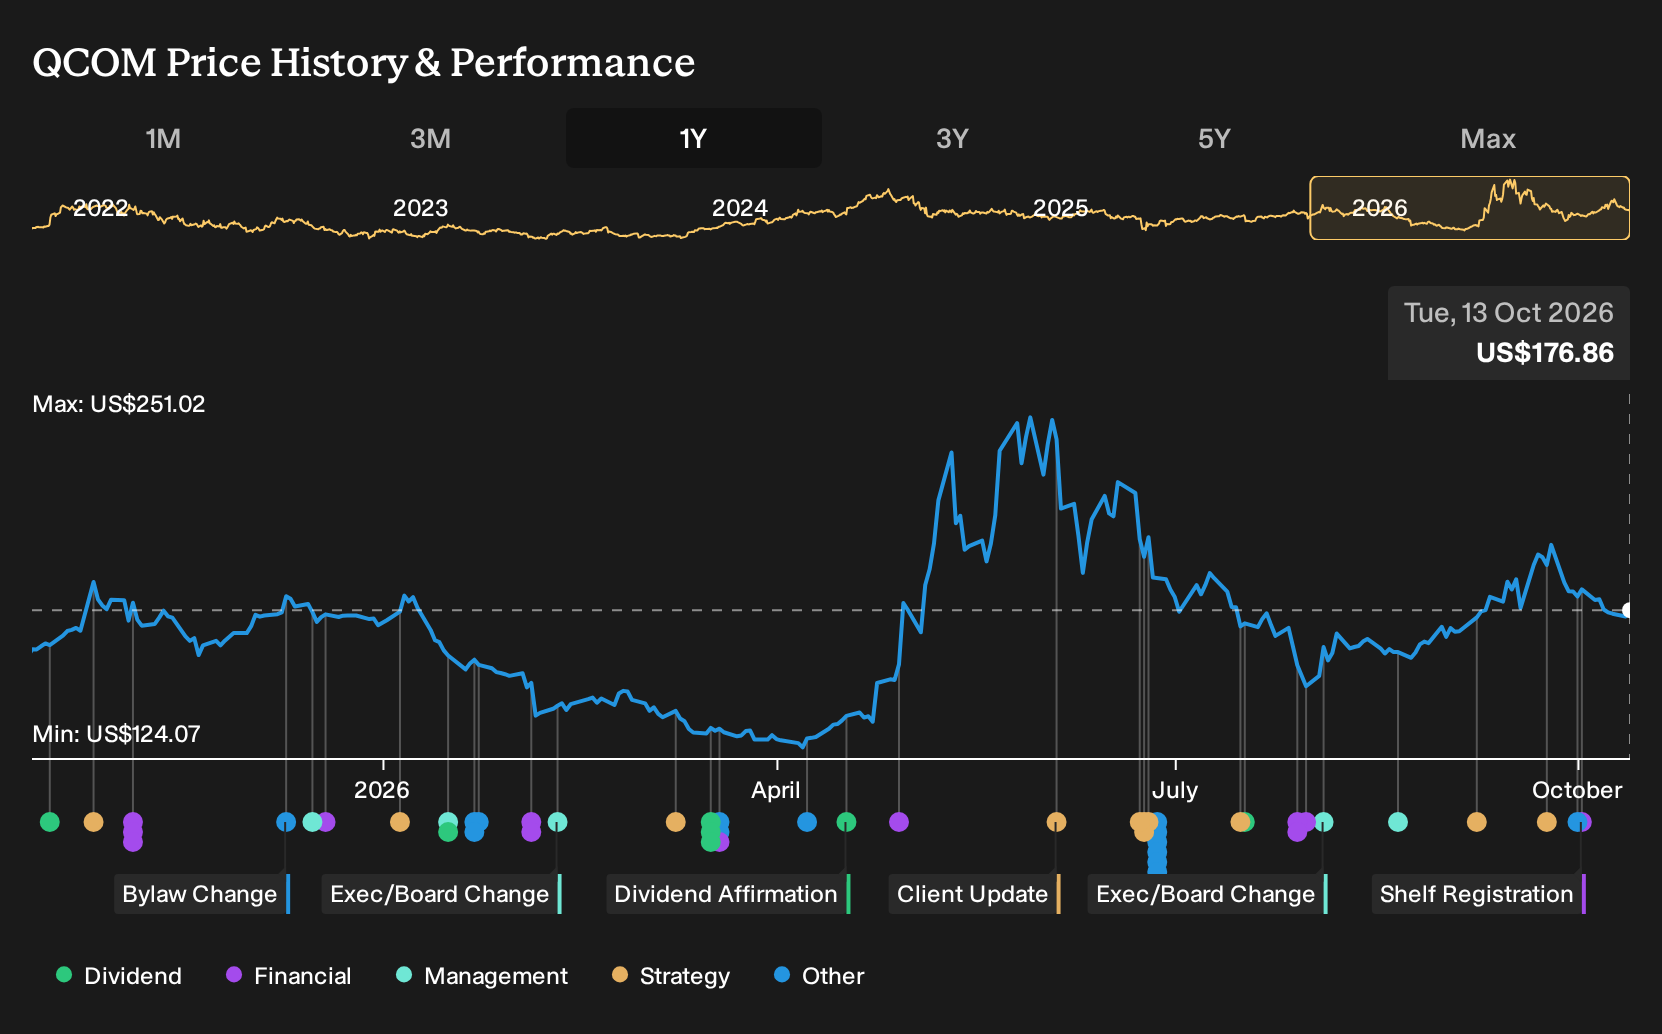
- In early October 2026, a federal jury in Delaware found that Arm Holdings breached its architectural license agreement with Qualcomm and intentionally interfered with Qualcomm’s business, supporting Qualcomm’s ability to continue developing custom Oryon CPU designs on Arm architecture.
- The ruling reduces legal uncertainty around Qualcomm’s semiconductor licensing model and chip roadmap. This is important for its push into data center, automotive and AI centric computing.
- We will now look at how Qualcomm’s broader investment narrative could be influenced by the Arm verdict that supports its custom CPUs.
See how QUALCOMM’s custom CPU win fits into the wider AI hardware race by comparing it with 92 AI infrastructure stocks that are powering the same build out in data centers and networks.
QUALCOMM Investment Narrative Recap
To own QUALCOMM, an investor needs to believe that handset dependence can gradually shrink while automotive, IoT, and AI data center chips grow into a larger share of the story. The short term swing factor is execution on AI centric products like Oryon CPUs and High Bandwidth Compute, plus early traction from the AWS custom silicon agreement.
The biggest operational risk still sits in handset cyclicality and the reduction of Apple related revenue, especially with earnings forecasts pointing to slight declines over the next three years. The new US$4.6b shelf registration is a tool. On its own it does not materially change the near term business catalyst or risk profile.
The most relevant new development around these catalysts is QUALCOMM’s US$4.6025b shelf registration for 25,000,000 common shares. A shelf gives the company flexibility to raise equity when conditions are attractive, whether to support AI data center ramps, 6G work, or broader diversification away from smartphones.
This financing option sits next to the firm’s large capital needs for data center programs, automotive pipelines, and AI capable connectivity products like Dragonwing based Wi Fi 8 gateways. If QUALCOMM chooses to issue stock under the shelf, investors would need to weigh potential dilution against the opportunity to fund execution on those long dated growth targets.
QUALCOMM’s current analyst narrative points to revenues of US$60.0b and earnings of US$11.5b by 2029, based on assumed yearly revenue growth of 10.8% and an earnings increase of about US$2.2b from US$9.3b today.
Discover why QUALCOMM's fair value indicates a 10% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses less on Qualcomm’s custom CPU win and more on margin pressure from lower priced data center deals. The most cautious analysts were working off about US$58.1b of 2029 revenue and US$11.8b of earnings, yet pairing that with a much lower 11.7x P/E. Those forecasts came before this verdict and shelf filing, so expectations may shift.
Explore 7 other QUALCOMM fair value estimates, including one that suggests it could be worth just $172.05.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your QUALCOMM research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for QUALCOMM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate QUALCOMM's overall financial health at a glance.
Looking for more QUALCOMM sized investment ideas?
If QUALCOMM has sharpened your interest in where to put fresh capital to work, it can help to scan for other businesses that line up with the portfolio role you want filled, whether that is value, resilience, or yield.
- For investors who want potential value with quality in mind, start by reviewing 32 high quality undervalued stocks that already combine stronger balance sheets with solid cash generation.
- If capital protection is front of mind, filter for stability first by running a 32 resilient stocks with low risk scores that screens for businesses with more resilient financial risk profiles.
- For those building an income focused portfolio, target reliability by using a 8 dividend fortresses that highlights higher yielding companies with the potential to support regular payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com