


Stagwell (STGW) has moved to refresh its leadership bench, appointing Alap Ghosh to run Stagwell Media in India and naming Jane Delworth president of MONO, as both units sharpen their global expansion plans.
Investors have been rewarding this leadership reshuffle, with Stagwell’s share price at $9.13 after a 1-day share price return of 3.05% and a 90-day share price return of 20.29%. The 1-year total shareholder return of 75.92% points to momentum that has built over a longer stretch.
Explore other marketing and media groups that demonstrate similar leadership-driven momentum by reviewing our handpicked 20 high quality undiscovered gems.
Stagwell now trades at a discount to both analyst targets and an internal fair value estimate after this leadership driven surge. Is that a bargain that reflects opportunity, or caution that fits the risks?
Most Popular Narrative: 6% Undervalued
Analysts following Stagwell see more upside than the current $9.13 share price implies, with their narrative pointing to a fair value of $9.71 and a discount rate of 8.21% anchoring that view.
Expansion and integration of proprietary digital and martech platforms (such as Code and Ink, and the "machine") are creating higher-margin, recurring revenue streams and improving operational efficiencies, which should drive net margin expansion.
Effective execution on tech-driven cost savings and operational synergies, including automation and back-office consolidation, is already resulting in improved free cash flow and lower leverage, which should boost earnings and support shareholder value via buybacks.
See why 6 investors see Stagwell as 6% undervalued.
Result: Fair Value of $9.71 (UNDERVALUED)
Still, Stagwell’s reliance on a small group of large tech clients, along with ongoing acquisition integration work, could quickly challenge the upbeat fair value story investors are leaning on.
Find out about the key risks to this Stagwell narrative.
Another Angle On Stagwell’s Valuation
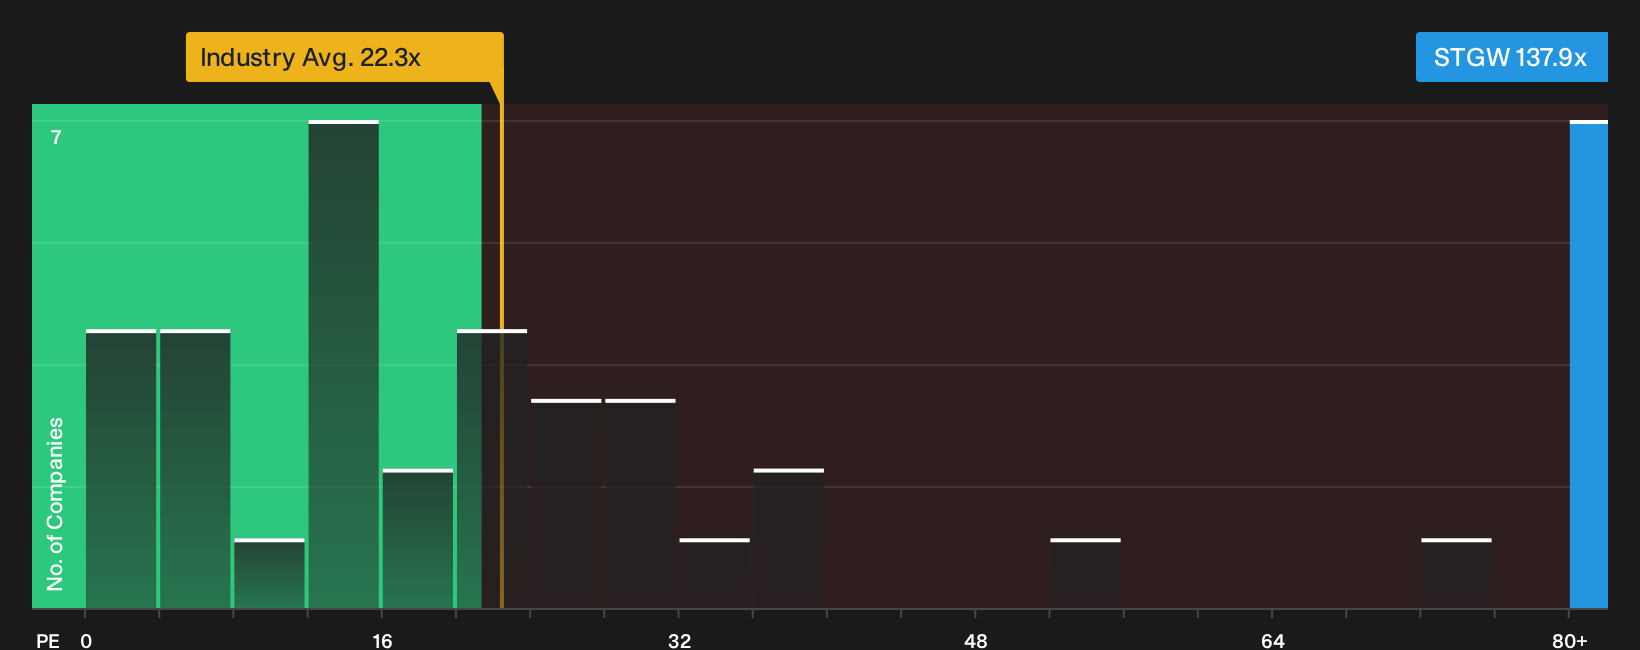
The first narrative leans on discounted cash flows to argue Stagwell looks undervalued, with a fair value estimate of $23.10 versus the current $9.13 share price. A different lens tells a tougher story. On a P/E of 137.9x, the stock trades well above the US Media industry on 22.3x and a fair ratio of 31.6x, which points to meaningful de-rating risk if expectations cool.
That kind of gap can matter a lot for returns, because even if earnings grow as forecast, a move back toward the industry or the fair ratio could offset part of the upside investors see in the DCF work.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Stagwell’s valuation story. If you want to move fast and form your own stance, start by weighing its 3 key rewards and 2 important warning signs.
Looking for more Stagwell sized investment ideas?
If Stagwell has your attention, do not stop here. Broader context across other companies can sharpen your judgment and highlight risks and opportunities sooner.
- Spot potential mispricings by scanning our 32 high quality undervalued stocks that combine solid fundamentals with prices that sit below implied worth on key metrics.
- Strengthen your downside protection by reviewing a 32 resilient stocks with low risk scores that screens for resilient balance sheets and steadier business profiles.
- Get ahead of the crowd by checking a 11 elite penny stocks with strong financials that focuses on smaller companies with stronger financials than their size suggests.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com