


Nutrien (TSX:NTR) is back in focus after the fertilizer producer decided to permanently idle its Trinidad Nitrogen operations at Point Lisas, citing prolonged natural gas issues and an initiative to improve free cash flow and returns.
Nutrien’s decision lands after a choppy stretch for the share price, with a 1-day share price return of 2.94% lifting the stock to CA$99.16. However, the 30-day share price return is down 8.86% while the 1-year total shareholder return sits at 25.8%, pointing to longer term momentum despite recent pressure.
Compare how Nutrien’s pivot away from Trinidad stacks up against other producers reshaping their footprint and free cash flow profiles with our hand picked list of solid balance sheet and fundamentals (8 results).
Nutrien trades below both analyst targets and an estimated intrinsic value, yet the market is clearly wary after the Trinidad exit. Is that discount a margin of safety or a warning label on the cash flow story?
Most Popular Narrative: 12% Undervalued
Nutrien’s most followed narrative pegs fair value at CA$112.78, which sits above the recent CA$99.16 close and frames the current discount around the mix and quality of future earnings rather than just near term fertilizer pricing.
Roughly US$1b of proceeds from divestments and non core asset sales since late 2024 gives Nutrien additional room to redirect capital into higher return potash, nitrogen and retail projects, which can lift future free cash flow and earnings relative to a steady state portfolio.
See why 6 investors see Nutrien as 12% undervalued.
Result: Fair Value of CA$112.78 (UNDERVALUED)
Still, the Nutrien story can break if weak phosphate margins persist or if any phosphate sale or restructuring ties up capital on low returns for an extended period.
Find out about the key risks to this Nutrien narrative.
Another View: Nutrien Through The P/E Lens
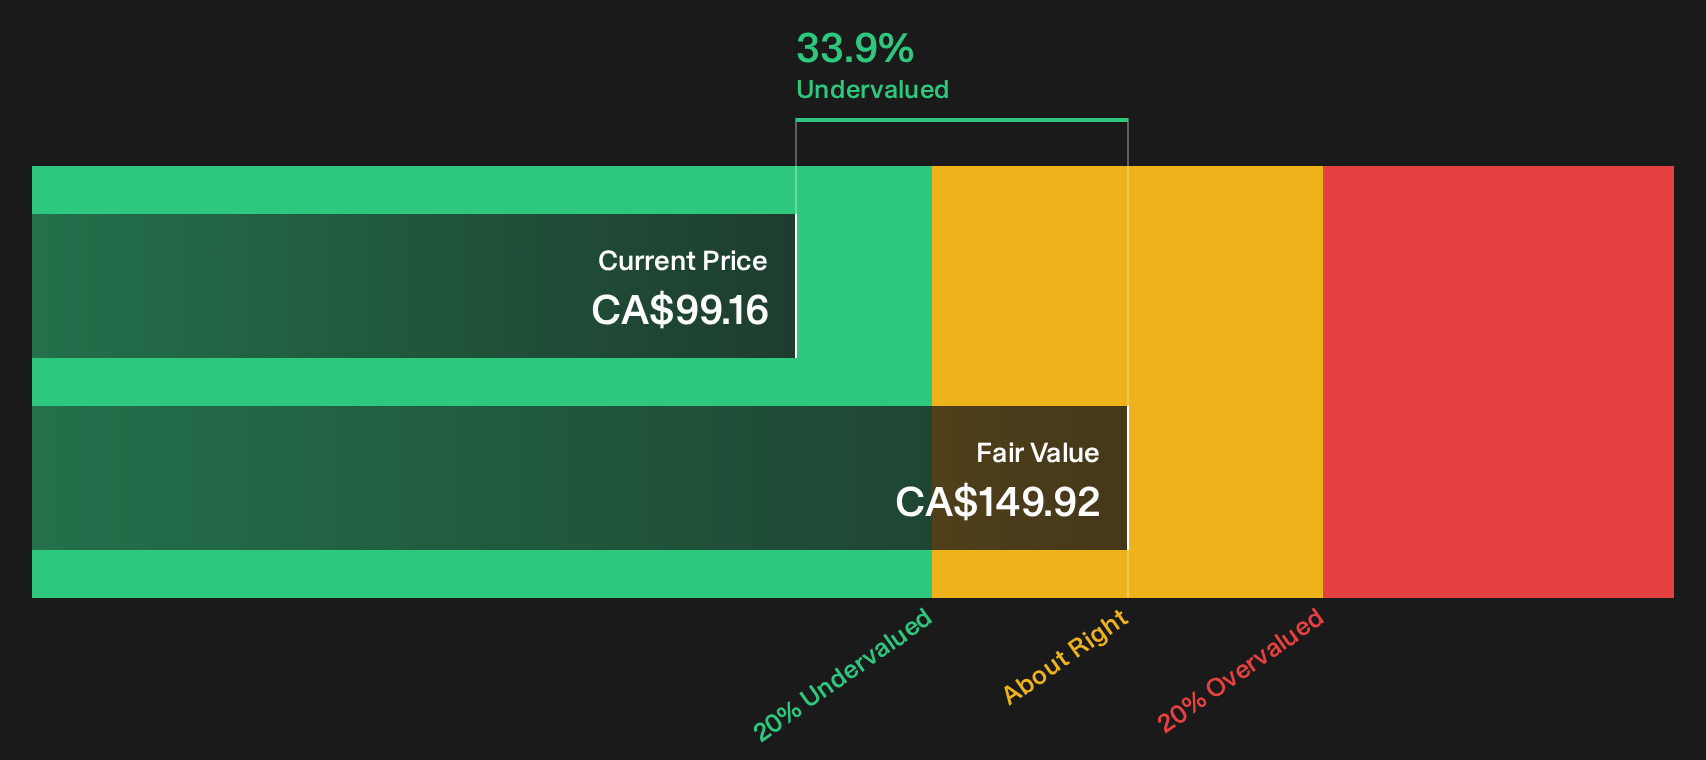
The DCF work suggests Nutrien trades at a steep discount to an estimated future cash flow value of CA$149.92, yet the earnings multiple tells a softer story. At 14x P/E, the stock is slightly above its own fair ratio of 13.7x but below the North American Chemicals average of 21x. Is that a pricing quirk, or a signal that cash flow assumptions might be generous?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed messages around Nutrien’s valuation and risk reward profile make this a moment to move fast on your own research and judgment. To weigh the trade off between concern and optimism using the full set of signals, take a focused look at the 2 key rewards and 2 important warning signs
Looking for more Nutrien-sized investment ideas?
Do not stop with Nutrien alone. Use the Simply Wall Street Screener to pressure test your thinking across other sectors, balance sheets, and return profiles before the best ideas get crowded.
- Strengthen your core holdings by focusing on quality and value through our carefully filtered 7 high quality undervalued stocks.
- Build a steadier income stream by zeroing in on companies we flag as 2 dividend fortresses.
- Sleep easier at night by concentrating on businesses screened as 8 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com