


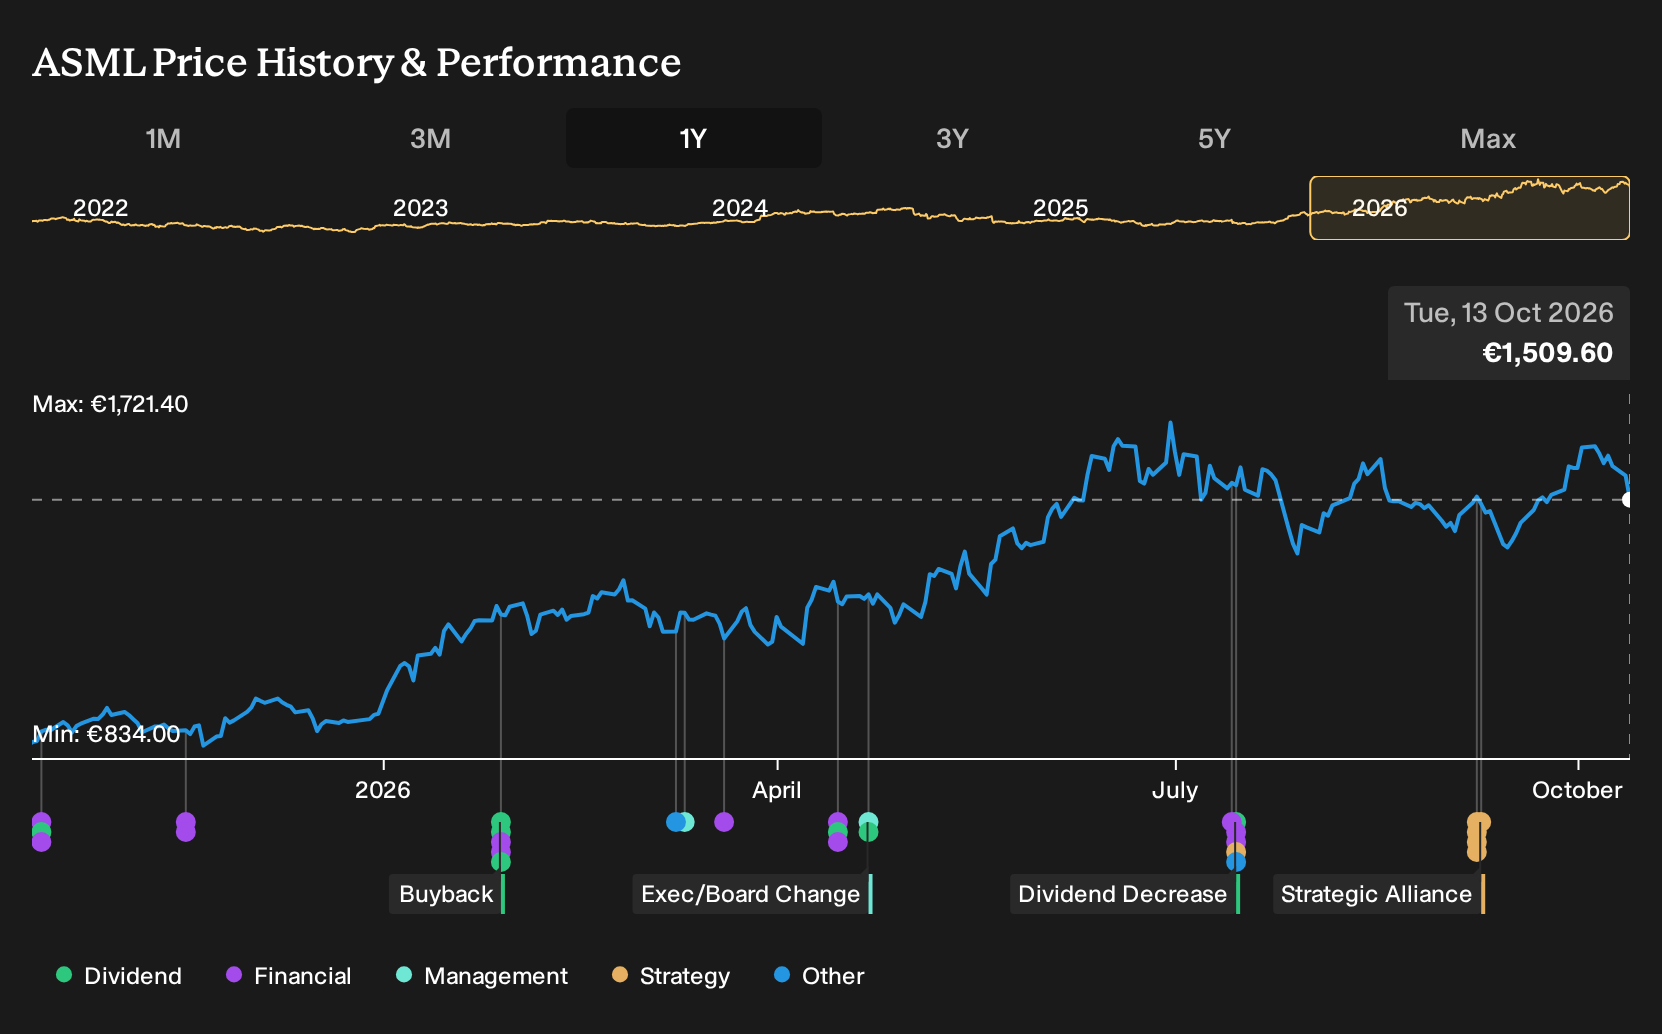
If you wanted a single proof point that AI capacity is now built tool by tool rather than chip by chip, ASML’s latest High NA EUV commitments from TSMC, Samsung, and Intel are a good place to start. Investors who held ASML over the past year are up 79.5%, including dividends. If that result depended on buying a near monopoly on critical kit, or on more optimistic forecasts than the bearish camp thought reasonable, what exactly had to be true back in October 2025?
ASML is not the only name tied to this theme. Zero in on 92 AI infrastructure stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On ASML
The shares cost €844 at the start of the period, so any view on ASML had to answer whether that price already captured years of EUV optimism or not.
The bullish Narrative pointed to a Fair Value of €950. That price reflected upbeat assumptions built on AI driven demand for EUV and High NA tools, together with a rapid ramp in ultra high margin service contracts tied to an expanding installed base.
The more cautious Narrative set Fair Value at €769 and treated 7.2% revenue growth and 30.4% profit margins as reasonable, while flagging export controls and customer concentration as real threats to ASML’s addressable market.
What The ASML Evidence Did To The Argument
Strong Q2 2026 results for ASML, with revenue moving from €7,691.7m to €9,326.5m and net income from €2,290.3m to €2,917.6m, plus a higher net margin at 31.3%, leaned toward the bullish case that AI related demand could support higher earnings power. Export control headlines and China related scrutiny still backed the more cautious view on geopolitical risk.
The lesson is clear: when a story rests on premium margins and scarce technology, you test it first against reported profitability and order dependent regions, not just headline growth or target prices.
What ASML’s One Year Run Already Prices In
ASML now trades at €1,510, after a 79.5% gain over the past year. The selected cautious Narrative views its Fair Value as sitting below that market price, while still describing an exceptionally strong competitive position and an attractive service engine.
Investors paying today’s level are effectively assuming that current AI driven demand, EUV intensity, and High NA adoption all hold up. The question the selected Narrative keeps coming back to is how much room remains if any part of that chain, from fab capex to China exposure, breaks.
"The problem is not ASML. The problem is the price investors are being asked to pay for it."
The price and this Narrative do not agree. → Uncover what this Narrative says ASML is actually worth
Where Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 34% below our estimate - targets higher membership and fee income from new gender focused club formats.
- Company 2 - 49% below our estimate - leans on retail and corporate lending into faster growing regional economies.
- Company 3 - 39% below our estimate - raises fee streams by recycling mature infrastructure assets into new managed funds.
Three companies from the same screener. Open every one of the 185 undervalued companies on it →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com