


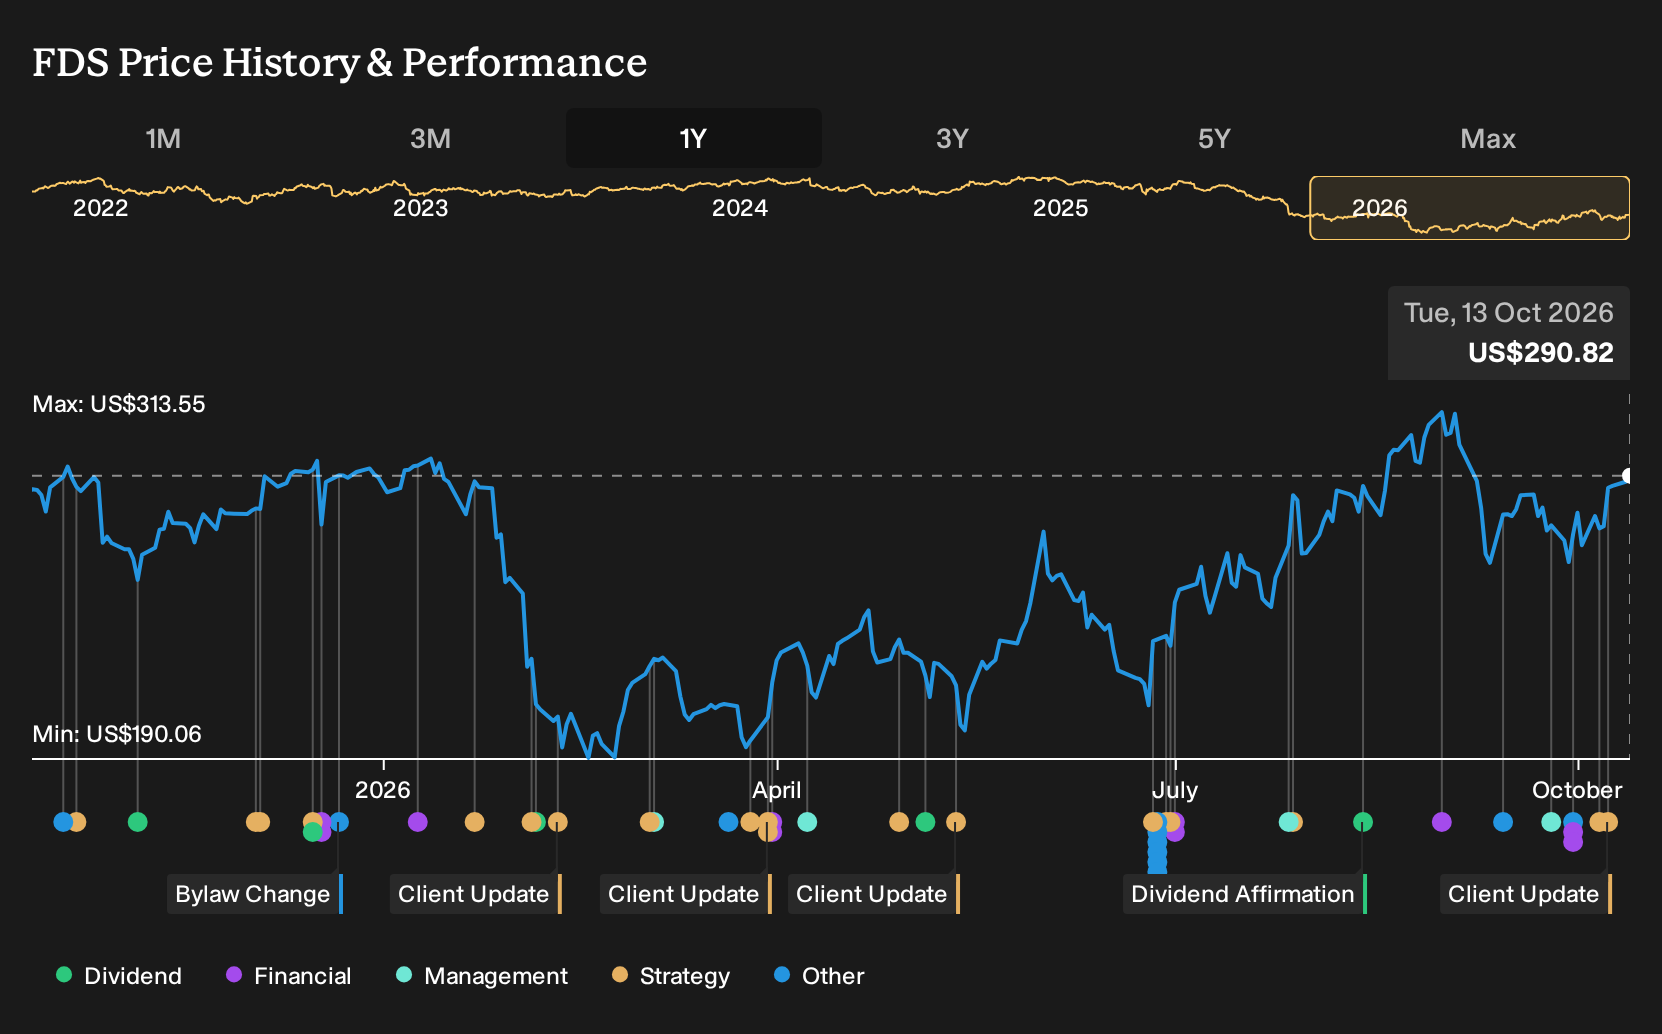
- FactSet Research Systems recently expanded its work with Scotia Wealth Management and SUBSCRIBE, deepening integration of its research platform into advisor and private fund workflows while also updating corporate bylaws and issuing fiscal 2027 revenue and earnings guidance.
- The twin partnerships highlight FactSet Research Systems' push to make its tools central to wealth and alternative investment processes, even as recent results show higher sales alongside lower net income and earnings per share compared with the prior year.
- We will now examine how FactSet Research Systems' broadened Scotia Wealth integration could reshape the investment narrative around its wealth platform.
Scan how FactSet Research Systems fits alongside other data and analytics providers by checking a curated set of 20 high quality undiscovered gems leading the buildout of modern investment infrastructure.
FactSet Research Systems Investment Narrative Recap
To stay with FactSet Research Systems, you need to believe its data and workflow platform can keep winning wallet share even while profit growth is uneven. The Scotia Wealth and SUBSCRIBE deals both feed that story by pushing FactSet deeper into day to day workflows. In the short term, the key swing factor is whether recent spending on technology and cloud starts to show up in better operating leverage.
The biggest near term risk still sits in client budgets and pricing power. Q4 and full year results showed higher revenue alongside lower net income and EPS, which keeps margin pressure front and center. The new fiscal 2027 guidance, including revenue and EPS ranges, now provides a clearer yardstick to judge execution against.
The expanded Scotia Wealth Management partnership looks most relevant for near term catalysts. It broadens FactSet Research Systems’ reach across advisors, investment professionals, and support staff, all working off a unified research and intelligence platform. That type of embedment can support asset based subscription metrics and cross sell of adjacent tools if users lean into the workflows.
There is risk that wealth managers facing tighter cost controls do not fully adopt or expand usage, which would limit the commercial payoff. Alongside that, the SUBSCRIBE integration into private fund onboarding and reporting ties into the same theme. Together, these announcements keep execution in wealth and alternatives as a key factor for whether the 2027 revenue and EPS guidance proves achievable.
FactSet Research Systems' current analyst script points to revenues of US$2.9b and earnings of US$707.0m by 2029, built on an assumed 5.6% yearly increase in sales and an earnings step up of about US$173.5m from US$533.5m today.
Uncover why FactSet Research Systems' fair value indicates a 5% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate take on FactSet Research Systems focuses less on new partnerships and more on margin strain from heavier cloud and AI spending. The most cautious analysts were penciling in about US$2.9b of revenue and roughly US$695.5m of earnings by 2029, and using a much lower P/E. Your view on these Scotia and SUBSCRIBE deals could shift that story.
Explore 5 other FactSet Research Systems fair value estimates, including one that suggests as much as 28% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your FactSet Research Systems research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FactSet Research Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FactSet Research Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond FactSet Research Systems?
Once you have a view on FactSet Research Systems, it can help to set that thesis against a wider set of opportunities so you are not relying on a single story.
- If you want potential mispricings with stronger fundamentals, scan a curated group of 32 high quality undervalued stocks that pair solid cash generation with more reasonable valuations.
- For steadier return potential and income focus, review a hand picked pool of 8 dividend fortresses that combine higher yields with more resilient payout profiles.
- When capital protection is a higher priority, assess a streamlined selection of 32 resilient stocks with low risk scores that screen well on balance sheet strength and business stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com