


Remitly Global (RELY) is back in focus after reporting strong quarterly profitability and rolling out the Remitly Global Card, a new product that reaches into cross border payments and digital asset services.
Recent price action reflects that renewed interest. Remitly Global’s share price has gained 8.05% over the past month and delivered a 79.73% year-to-date share price return, while the one-year total shareholder return of 55.19% sits against a weaker three-year record, which suggests momentum has picked up only more recently.
Scan alongside Remitly Global and see how other cross border and payments focused players stack up in our curated list of 32 high quality undervalued stocks.
For Remitly Global, that sharp rebound could signal investors are reassessing the underlying business rather than just chasing sentiment. The next step is to see whether the current price fairly reflects that shift in expectations.
Most Popular Narrative: 27% Undervalued
On the latest numbers, the narrative fair value of Remitly Global sits at $32.33 compared with a last close of $23.76. This frames the current debate around whether the recent rally has fully caught up with the story playing out in the background.
The strategic launch of stablecoin functionality and multicurrency wallets positions Remitly to capitalize on the accelerating adoption of digital financial services and rising global smartphone penetration. This should drive higher customer acquisition, improve retention, and diversify revenue streams. Agentic AI capabilities embedded in customer acquisition channels (e.g., WhatsApp) and support functions facilitate migration from offline to online remittances, unlock operational efficiencies, reduce cost to serve, and should widen net margins as digital adoption in emerging markets accelerates.
See why 39 investors see Remitly Global as 27% undervalued.
The most followed narrative on Remitly Global applies a discount rate of 7.3% and lands on a fair value estimate of $32.33, which is about 27% above the current share price. That view leans heavily on revenue growth assumptions of roughly 19% a year, paired with slimmer profit margins over time and a higher future P/E multiple than both the broader US market and the Diversified Financial peer group.
Analysts feeding into this framework are effectively saying the business may earn less on each dollar of sales in a few years, yet still command a richer valuation multiple because of its remittance footprint, product expansion and return on equity profile. For you as a shareholder or potential investor, the key question is whether those ingredients, plus the forecast 24.3% return on equity in three years, justify paying up for earnings that consensus expects to decline on average by 6.5% a year over the next three years.
Result: Fair Value of $32.33 (UNDERVALUED)
Still, the story breaks if fee pressure from aggressive fintech rivals or tougher rules on stablecoins and cross border transfers affect Remitly Global’s pricing power and costs.
Find out about the key risks to this Remitly Global narrative.
Another View: What Remitly Global’s P/E Is Really Saying
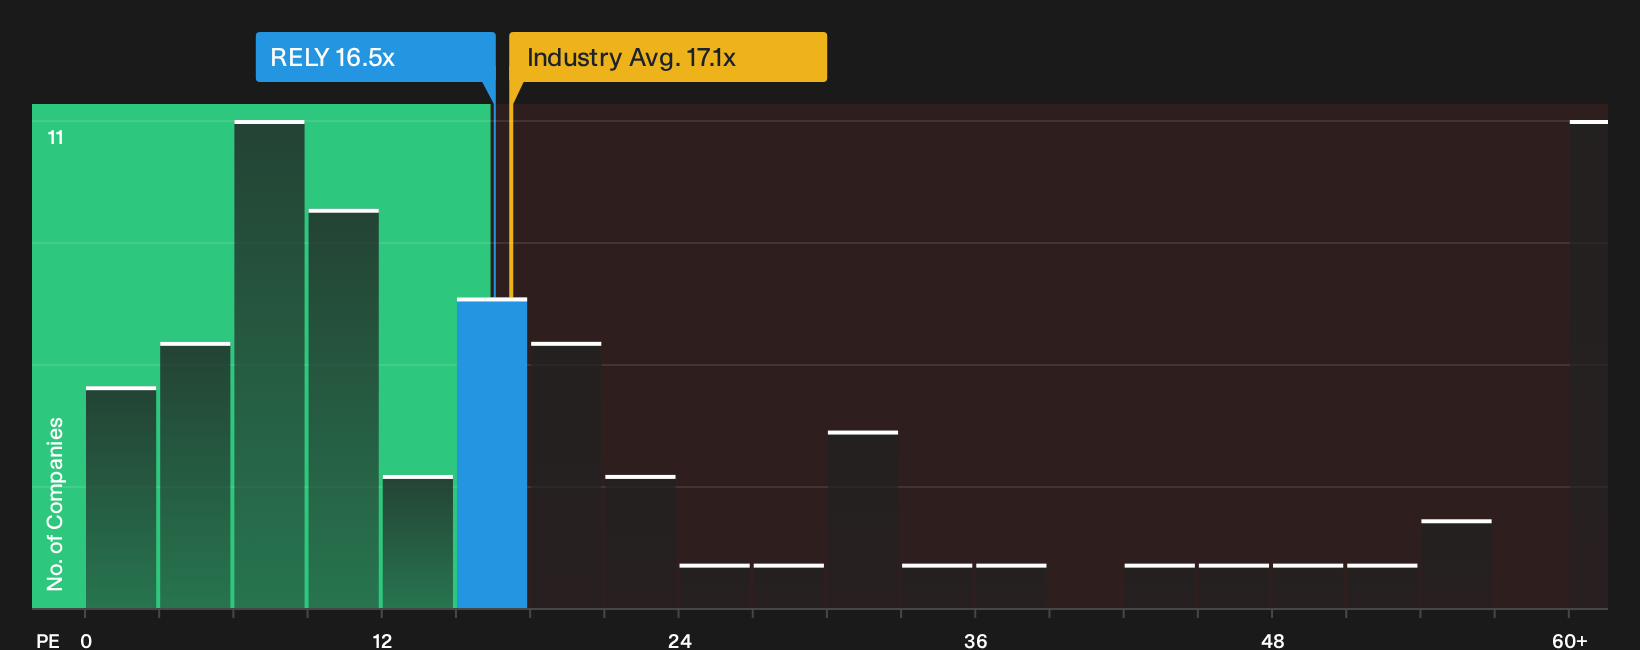
There is a catch in the Remitly Global story. On analyst forecasts it screens undervalued on fair value, yet today the P/E of 16.5x sits above a fair ratio of 11.4x, even though it is roughly in line with the US Diversified Financial industry at 17x and well below peers at 41x. That mix of relative value and fair ratio gap raises a simple question for you: is the market underestimating the business, or already paying up for the story?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed on the story so far or leaning one way already? Move quickly, pull up the full data set, and weigh both the upside drivers and the risk flags through our breakdown of 4 key rewards and 2 important warning signs
Looking for more investment ideas beyond Remitly Global?
Do not stop your research with Remitly Global. Broaden your watchlist now, compare different angles on quality and risk, and give yourself more options before the next move.
- Target higher yield potential by reviewing income candidates in the 8 dividend fortresses that pair strong payouts with robust fundamentals.
- Protect your downside first and scan for companies with resilient finances using the list of solid balance sheet and fundamentals (25 results).
- Get ahead of the crowd by checking the 20 high quality undiscovered gems that strong fundamentals already support, before wider attention follows.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com