


- Hyland announced in October 2026 that it joined the Jack Henry Fintech Integration Network, gaining direct access to Jack Henry resources to support OnBase integrations with SilverLake and Symitar Episys for document management and workflow automation.
- The move positions Jack Henry & Associates as a more connected hub for third party fintech tools, reducing integration friction for banks and credit unions that want content, workflows and core data aligned in a single operating environment.
- We will now look at how Jack Henry & Associates' investment narrative is shaped by tighter Hyland OnBase integration across its core platforms.
Scan how Jack Henry & Associates fits into a broader push for tightly integrated financial infrastructure by checking a curated set of 92 AI infrastructure stocks now shaping core banking workflows.
Jack Henry & Associates Investment Narrative Recap
To own Jack Henry & Associates, you need to believe that tighter integration wins with banks and credit unions, and that it can keep offsetting slow industry consolidation and price pressure. The Hyland Fintech Integration Network news supports that view operationally, because it aims to make Jack Henry’s core platforms more useful as clients push harder on workflow, compliance and content automation.
The key short term swing factor remains how consistently management converts that embedded position into hosted, public cloud and AI driven projects that sustain revenue in the mid single digit range and protect margins. The biggest risk stays the same: a shrinking pool of institutions and ongoing cost inflation could pressure earnings if win rates or pricing weaken.
The Hyland OnBase integration aligns neatly with Jack Henry’s push into hosted and public cloud platforms. Roughly 79% of core customers are already in the private cloud, and about 100 institutions are running the cloud native Jack Henry platform. Easier document and workflow connectivity can make those conversions more attractive and may support stickier, higher value contracts.
This announcement also ties into newer offerings in SMB banking, treasury and real time payments, where products like Tap2Local and Rapid Transfers depend on clean access to core data and governed workflows. If execution on these connected services stays disciplined, the Hyland link can act as an enabler for those catalysts, while not removing core risks around client consolidation or potential margin pressure.
Jack Henry & Associates' narrative projects US$3.1b revenue and US$610.5m earnings by 2029. This aligns with analysts assuming 6.6% yearly revenue growth and an earnings increase of about US$107.7m from US$502.8m today.
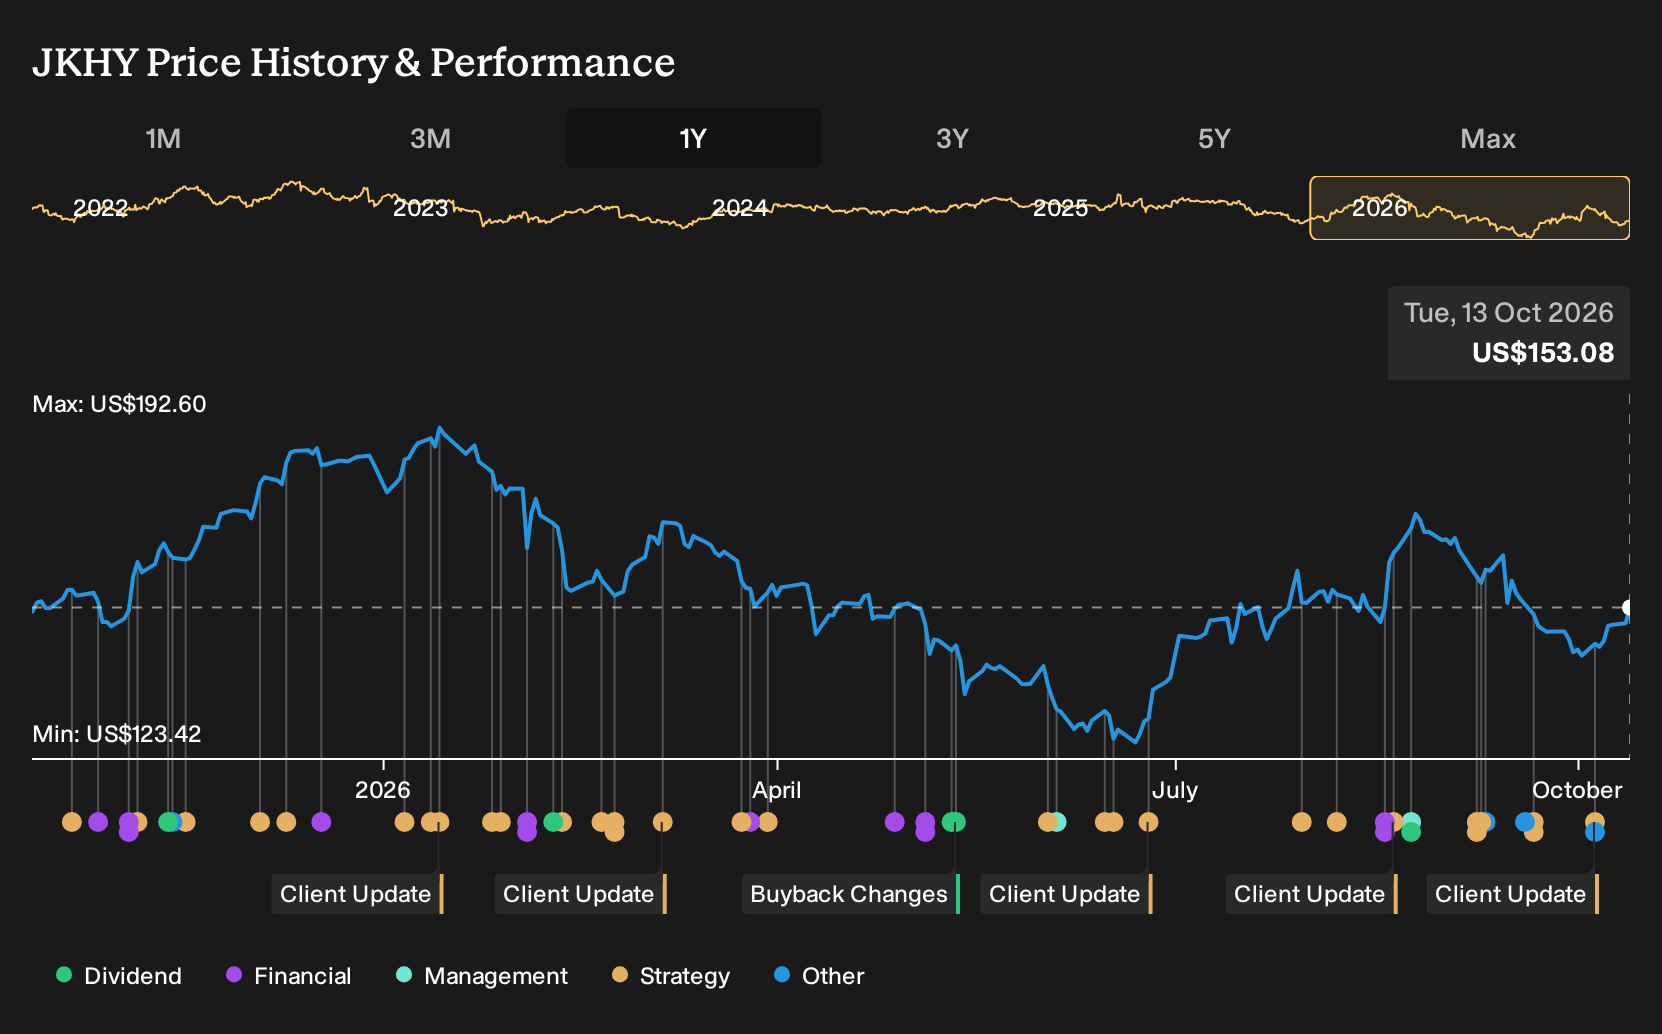
Uncover why Jack Henry & Associates' fair value indicates a 24% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about US$163.69 and US$206.60 per share, with no single consensus anchor. That spread shows how differently private investors can assess Jack Henry & Associates as they weigh cloud adoption, AI driven efficiency and the risk of ongoing bank consolidation. You should expect opinions to vary, and it is worth exploring several alternative viewpoints before forming a view.
Explore 3 other Jack Henry & Associates fair value estimates, including one that suggests it could be worth just $163.69.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jack Henry & Associates research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Jack Henry & Associates. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jack Henry & Associates' overall financial health at a glance.
Looking for more investment ideas beyond Jack Henry & Associates?
Once you have a view on Jack Henry & Associates, it can help to compare it with a few different types of opportunities side by side in the Simply Wall St Screener.
- If capital preservation is a priority, start with a shortlist of 32 resilient stocks with low risk scores that may offer a smoother ride through market swings.
- For those focused on quality and valuation, scan a curated 20 high quality undiscovered gems that combine solid fundamentals with limited market attention.
- Income first investors can zero in on a targeted 8 dividend fortresses that filters for higher yields supported by underlying business metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com