


As European markets experience volatility due to renewed Middle East tensions, a hawkish European Central Bank stance, and mixed economic indicators, investors are increasingly focusing on companies with strong fundamentals. In this environment, growth companies with high insider ownership can offer a compelling proposition, as insider confidence often signals alignment with shareholder interests and potential resilience in uncertain times.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| Kuros Biosciences (SWX:KURN) | 23.7% | 65.8% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Egetis Therapeutics (OM:EGTX) | 18.4% | 49.5% |
| CTT Systems (OM:CTT) | 17.4% | 55.3% |
| Clavister Holding AB (publ.) (OM:CLAV) | 19.4% | 41.1% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.3% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 30.2% |
We're going to check out a few of the best picks from our screener tool.
Atea (OB:ATEA)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Atea ASA offers IT infrastructure and related solutions to businesses and public sector organizations across the Nordic countries and Baltic regions, with a market cap of NOK18.21 billion.
Operations: The company's revenue segments include NOK10.16 billion from Norway, NOK15.52 billion from Sweden, NOK8.65 billion from Denmark, NOK3.58 billion from Finland, and NOK2.15 billion from the Baltics, with an additional contribution of NOK13.69 billion from Group Shared Services.
Insider Ownership: 28.6%
Atea's recent performance highlights its growth potential, with earnings up 54.2% over the past year and a forecasted annual earnings growth of 6.96%, outpacing the Norwegian market. Despite trading at a significant discount to its estimated fair value, revenue is projected to grow at a modest 5% annually. Recent financials show improved sales and net income for both quarterly and semi-annual periods, indicating robust operational progress despite slower anticipated revenue expansion compared to high-growth benchmarks.
- Navigate through the intricacies of Atea with our comprehensive analyst estimates report here.
- Upon reviewing our latest valuation report, Atea's share price might be too pessimistic.
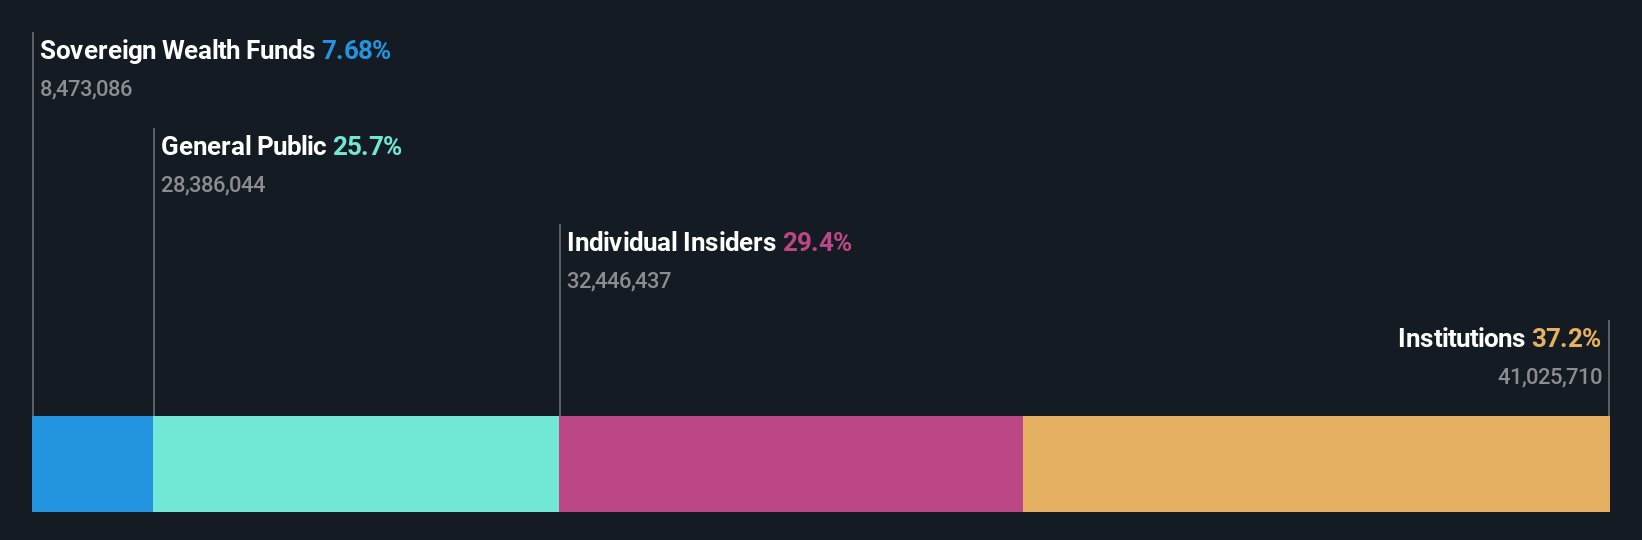
Avanza Bank Holding (OM:AZA)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Avanza Bank Holding AB (publ) operates in Sweden, offering a range of savings, pension, and mortgage products with a market cap of SEK60.01 billion.
Operations: Avanza Bank Holding AB generates revenue primarily from its commercial operations, amounting to SEK5.38 billion.
Insider Ownership: 13.1%
Avanza Bank Holding shows promising growth potential, with recent earnings results reflecting a net income increase to SEK 785 million for Q2 2026. The company's earnings are forecasted to grow at 8.84% annually, surpassing the Swedish market average. Despite trading at a significant discount to its estimated fair value, revenue growth is projected at 6.9% per year. Insider transactions have been more purchases than sales recently but not in substantial volumes, indicating cautious optimism among insiders.
- Unlock comprehensive insights into our analysis of Avanza Bank Holding stock in this growth report.
- The analysis detailed in our Avanza Bank Holding valuation report hints at an deflated share price compared to its estimated value.

Hexatronic Group (OM:HTRO)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Hexatronic Group AB (publ) and its subsidiaries develop, manufacture, market, and sell fiber communication solutions in Sweden, the United States, Germany, the United Kingdom, and internationally with a market cap of SEK9.42 billion.
Operations: Hexatronic Group AB generates revenue from three main segments: Fiber Solutions (SEK4.73 billion), Data Center (SEK1.68 billion), and Harsh Environment (SEK1.27 billion).
Insider Ownership: 10.3%
Hexatronic Group's expected annual earnings growth of 38.9% significantly outpaces the Swedish market, despite a forecasted low return on equity of 13%. Revenue is projected to grow at 9.3% annually, faster than the declining Swedish market. Recent executive changes indicate strategic shifts, with Pernilla Lindén transitioning to President Fiber Solutions. Despite volatile share prices and reduced profit margins from last year, Hexatronic trades at a notable discount to its fair value with insider purchases outweighing sales recently.
- Get an in-depth perspective on Hexatronic Group's performance by reading our analyst estimates report here.
- In light of our recent valuation report, it seems possible that Hexatronic Group is trading behind its estimated value.
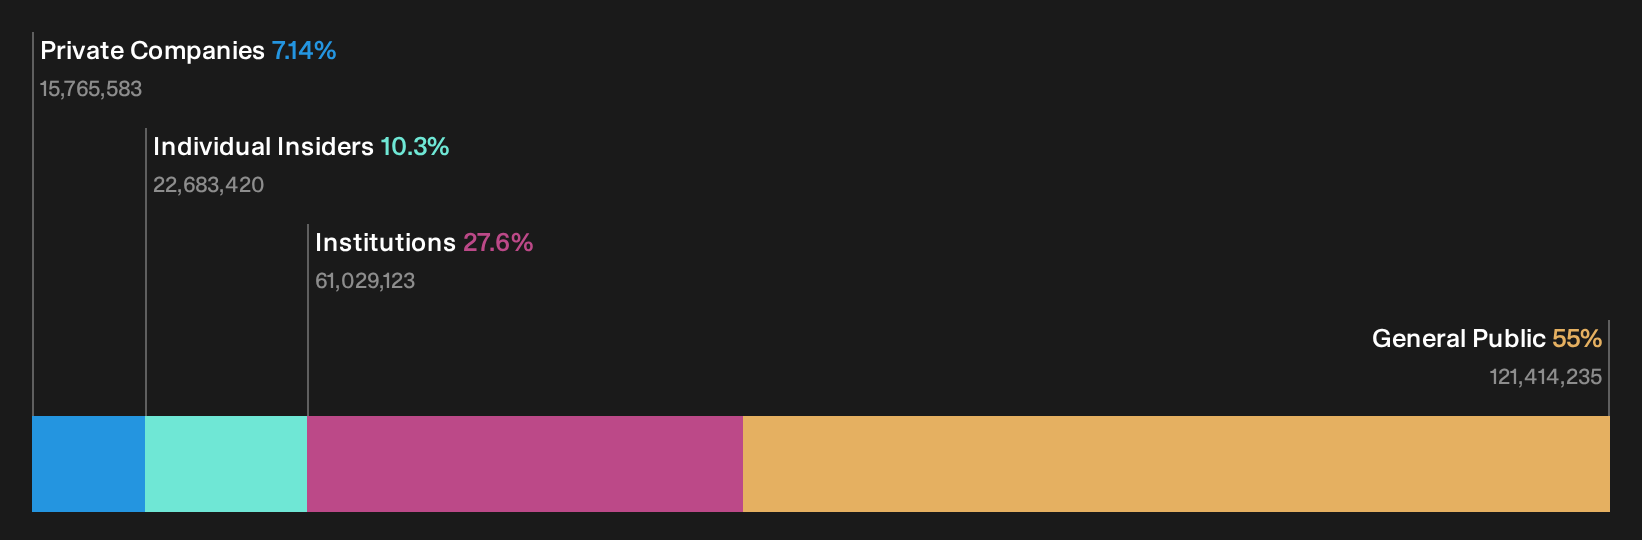
Seize The Opportunity
- Embark on your investment journey to our 201 Fast Growing European Companies With High Insider Ownership selection here.
- Curious About Other Options? Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com