


The European market has experienced volatility recently, influenced by Middle East tensions and mixed economic indicators, with the pan-European STOXX Europe 600 Index ending the week nearly flat. Amid this uncertain environment, identifying undervalued stocks can be a strategic move for investors seeking potential opportunities in equities that may not yet reflect their intrinsic value.
Top 10 Undervalued Stocks Based On Cash Flows In Europe
| Name | Current Price | Fair Value (Est) | Discount (Est) |
| XTB (WSE:XTB) | PLN135.84 | PLN267.26 | 49.2% |
| Valmet Oyj (HLSE:VALMT) | €26.66 | €53.04 | 49.7% |
| Sentia (OB:SNTIA) | NOK79.60 | NOK155.46 | 48.8% |
| PORR (WBAG:POS) | €30.65 | €60.56 | 49.4% |
| Orthex Oyj (HLSE:ORTHEX) | €4.50 | €8.89 | 49.4% |
| Lindab International (OM:LIAB) | SEK126.30 | SEK250.80 | 49.6% |
| Koninklijke BAM Groep (ENXTAM:BAMNB) | €11.53 | €22.82 | 49.5% |
| ING Groep (ENXTAM:INGA) | €30.10 | €59.67 | 49.6% |
| DWS Group GmbH KGaA (XTRA:DWS) | €66.75 | €127.56 | 47.7% |
| Apator (WSE:APT) | PLN24.80 | PLN49.38 | 49.8% |
Let's uncover some gems from our specialized screener.
UniCredit (BIT:UCG)
Overview: UniCredit S.p.A. is a commercial banking provider operating in Italy, Germany, Central Europe, and Eastern Europe with a market cap of €115.37 billion.
Operations: The company's revenue is primarily derived from Italy (€10.74 billion), Germany (€5.23 billion), Central and Eastern Europe excluding Austria (€4.69 billion), Austria (€2.58 billion), and Russia (€1.03 billion).
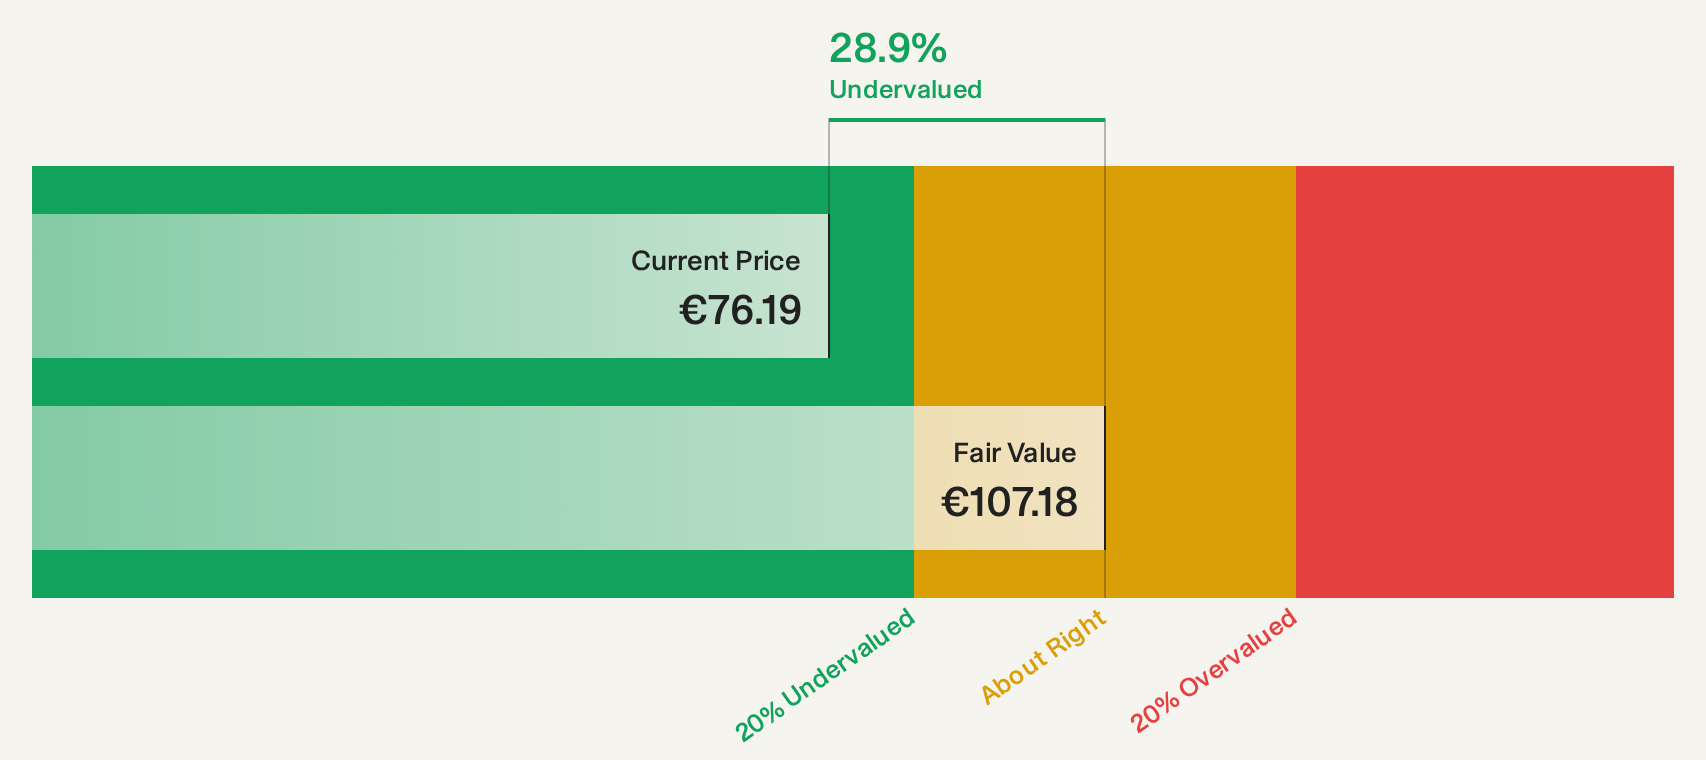
Estimated Discount To Fair Value: 26.2%
UniCredit appears undervalued, trading 26.2% below its estimated fair value, with a market price of €77 against a future cash flow value of €104.4. Despite slower forecasted earnings growth (8%) compared to the Italian market (10%), recent M&A discussions, including potential mergers with Commerzbank and Banco BPM, could unlock capital savings and synergies worth billions. However, UniCredit's high level of bad loans (2.2%) remains a concern amidst these strategic moves.
- Upon reviewing our latest growth report, UniCredit's projected financial performance appears quite optimistic.
- Dive into the specifics of UniCredit here with our thorough financial health report.
ING Groep (ENXTAM:INGA)
Overview: ING Groep N.V. offers a range of banking products and services across the Netherlands, Belgium, Germany, other parts of Europe, and internationally, with a market cap of €85.58 billion.
Operations: The company's revenue is primarily derived from Wholesale Banking (€6.65 billion), Retail Banking Netherlands (€5.20 billion), Retail Banking Other (€4.83 billion), Retail Banking Germany (€2.93 billion), and Retail Banking Belgium (€2.58 billion).
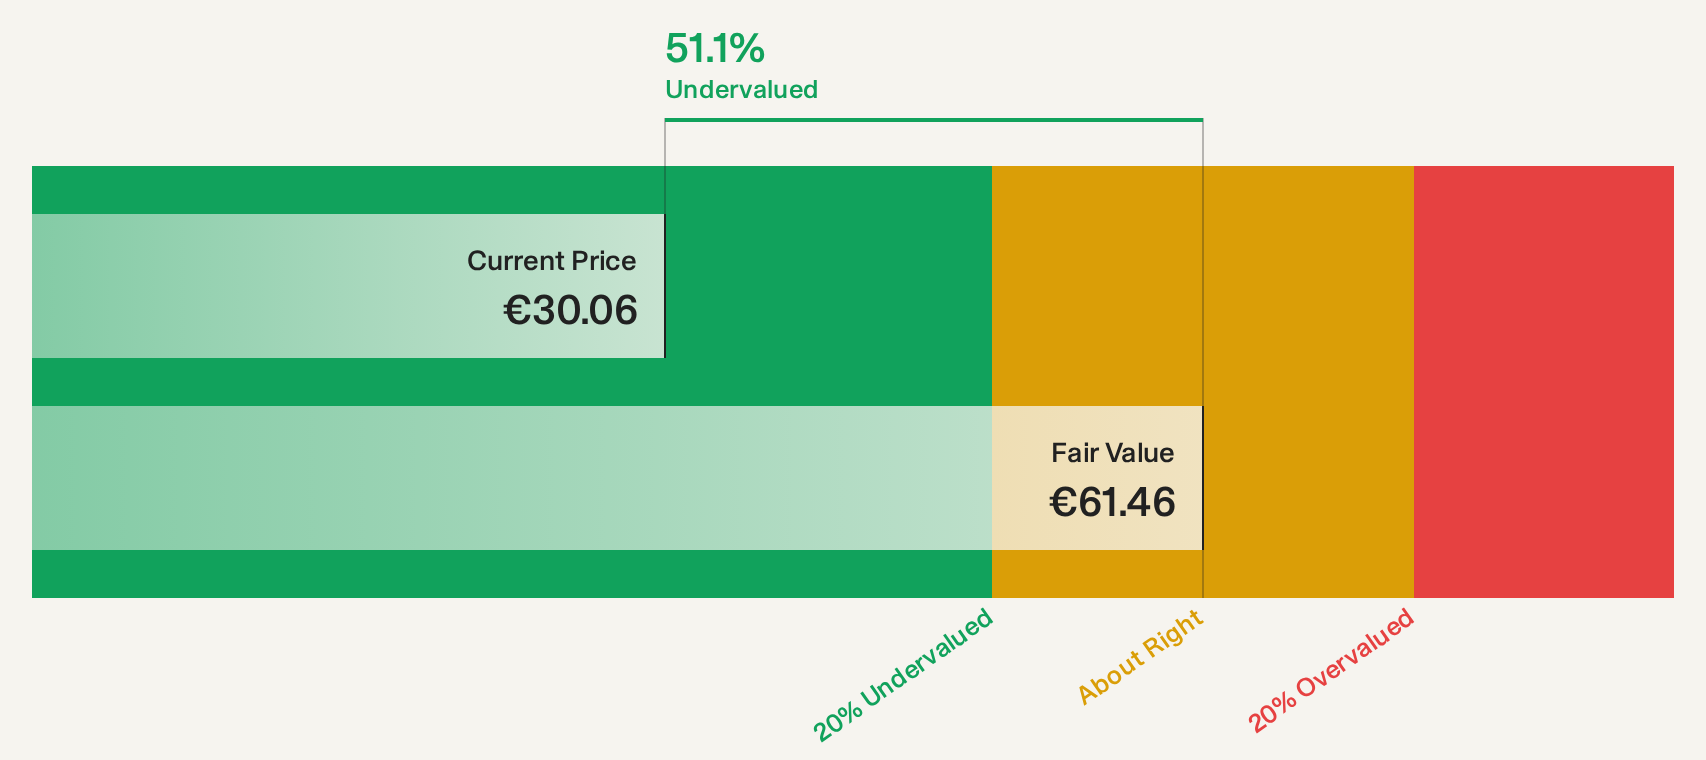
Estimated Discount To Fair Value: 49.6%
ING Groep is trading at 49.6% below its fair value estimate of €59.67, with a current price of €30.1, suggesting significant undervaluation based on discounted cash flow analysis. Despite a low bad loan allowance (42%) and slower forecasted earnings growth (2% annually), ING's recent dividend increase and upgraded earnings guidance for 2026-2027 highlight potential financial resilience. The company's strategic debt redemption could also enhance its balance sheet strength amidst these valuation metrics.
- In light of our recent growth report, it seems possible that ING Groep's financial performance will exceed current levels.
- Click here to discover the nuances of ING Groep with our detailed financial health report.
Huuuge (WSE:HUG)
Overview: Huuuge, Inc. is a developer and publisher of free-to-play mobile games with operations in North America, Europe, the Asia Pacific, and internationally; it has a market cap of PLN1.01 billion.
Operations: The company's revenue primarily comes from its online mobile games segment, which generated $221.84 million.
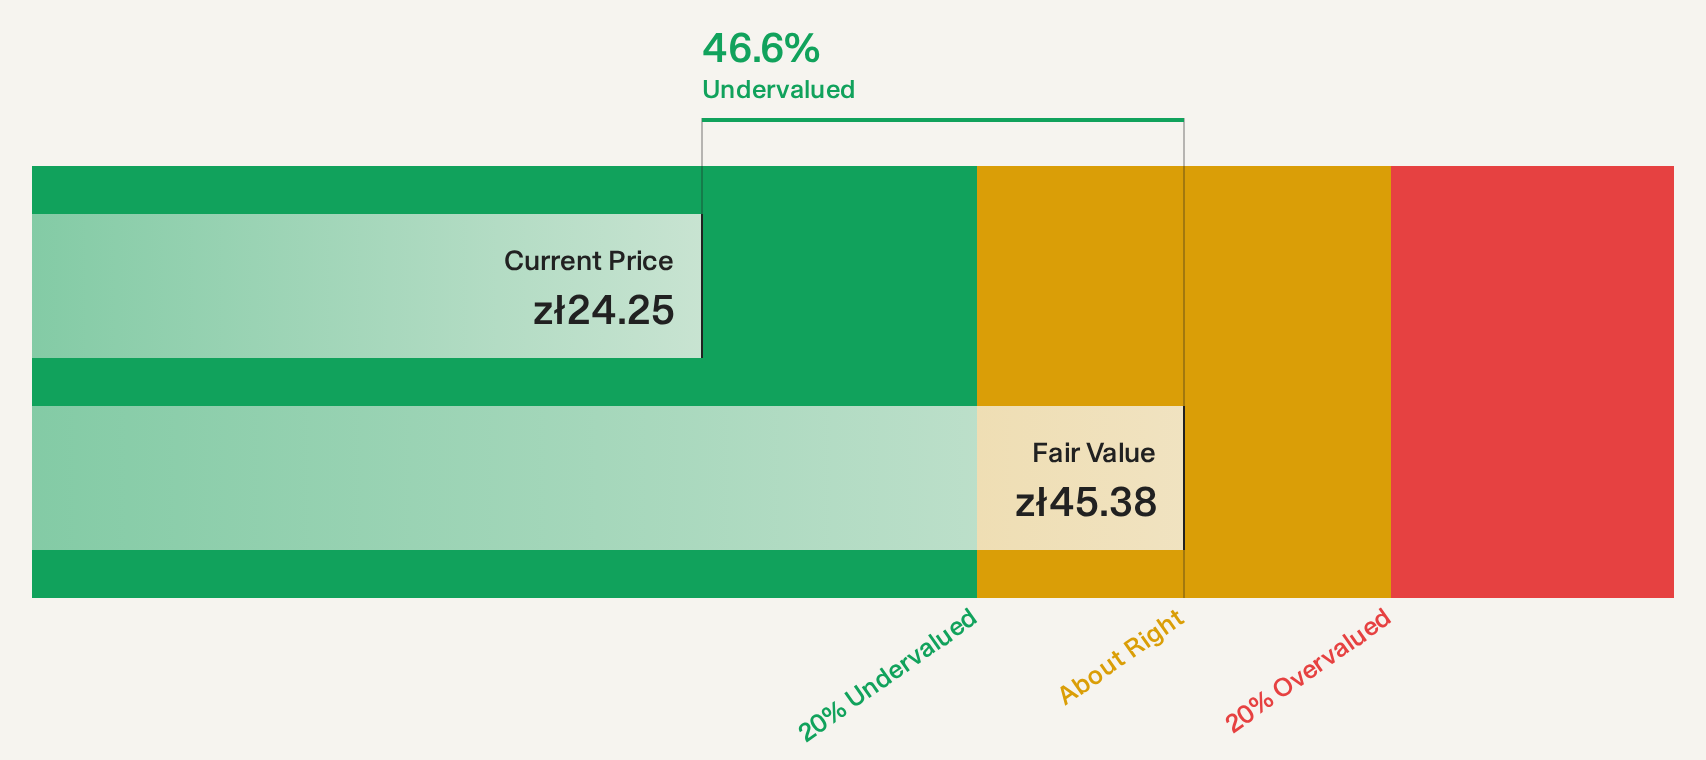
Estimated Discount To Fair Value: 46.5%
Huuuge, Inc. is trading at a significant discount to its estimated fair value of PLN45.64, with a current price of PLN24.4, highlighting potential undervaluation based on cash flows. Despite forecasts indicating a decline in earnings and revenue over the next three years (-15.7% and -4.3% per year respectively), Huuuge's recent share repurchase program for $120 million could enhance shareholder value by reducing outstanding shares and potentially improving return metrics like Return on Equity, forecasted at 39%.
- The analysis detailed in our Huuuge growth report hints at robust future financial performance.
- Click here and access our complete balance sheet health report to understand the dynamics of Huuuge.
Seize The Opportunity
- Reveal the 65 hidden gems among our Undervalued European Stocks Based On Cash Flows screener with a single click here.
- Have you diversified into these companies? Leverage the power of Simply Wall St's portfolio to keep a close eye on market movements affecting your investments.
- Maximize your investment potential with Simply Wall St, the comprehensive app that offers global market insights for free.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Diversify your portfolio with solid dividend payers offering reliable income streams to weather potential market turbulence.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com