


Big fines at Bank of America have thrown bank compliance back into the spotlight, and the reaction in BAC after-hours trading shows how quickly regulatory risk can hit share prices. When large lenders face rising AML and sanctions costs, specialist advisers that help fix those issues can see very different fortunes. This article walks through three US professional services firms serving large banks that are closely exposed to this story.
The three stocks below are just a sample of the opportunity set, and the full screen surfaced 16 more US professional services firms tied to big-bank compliance and remediation themes that are not covered in this article.
If you want to identify and analyze the highest conviction ideas first, head straight to the US Professional Services Firms Serving Large Banks screener.
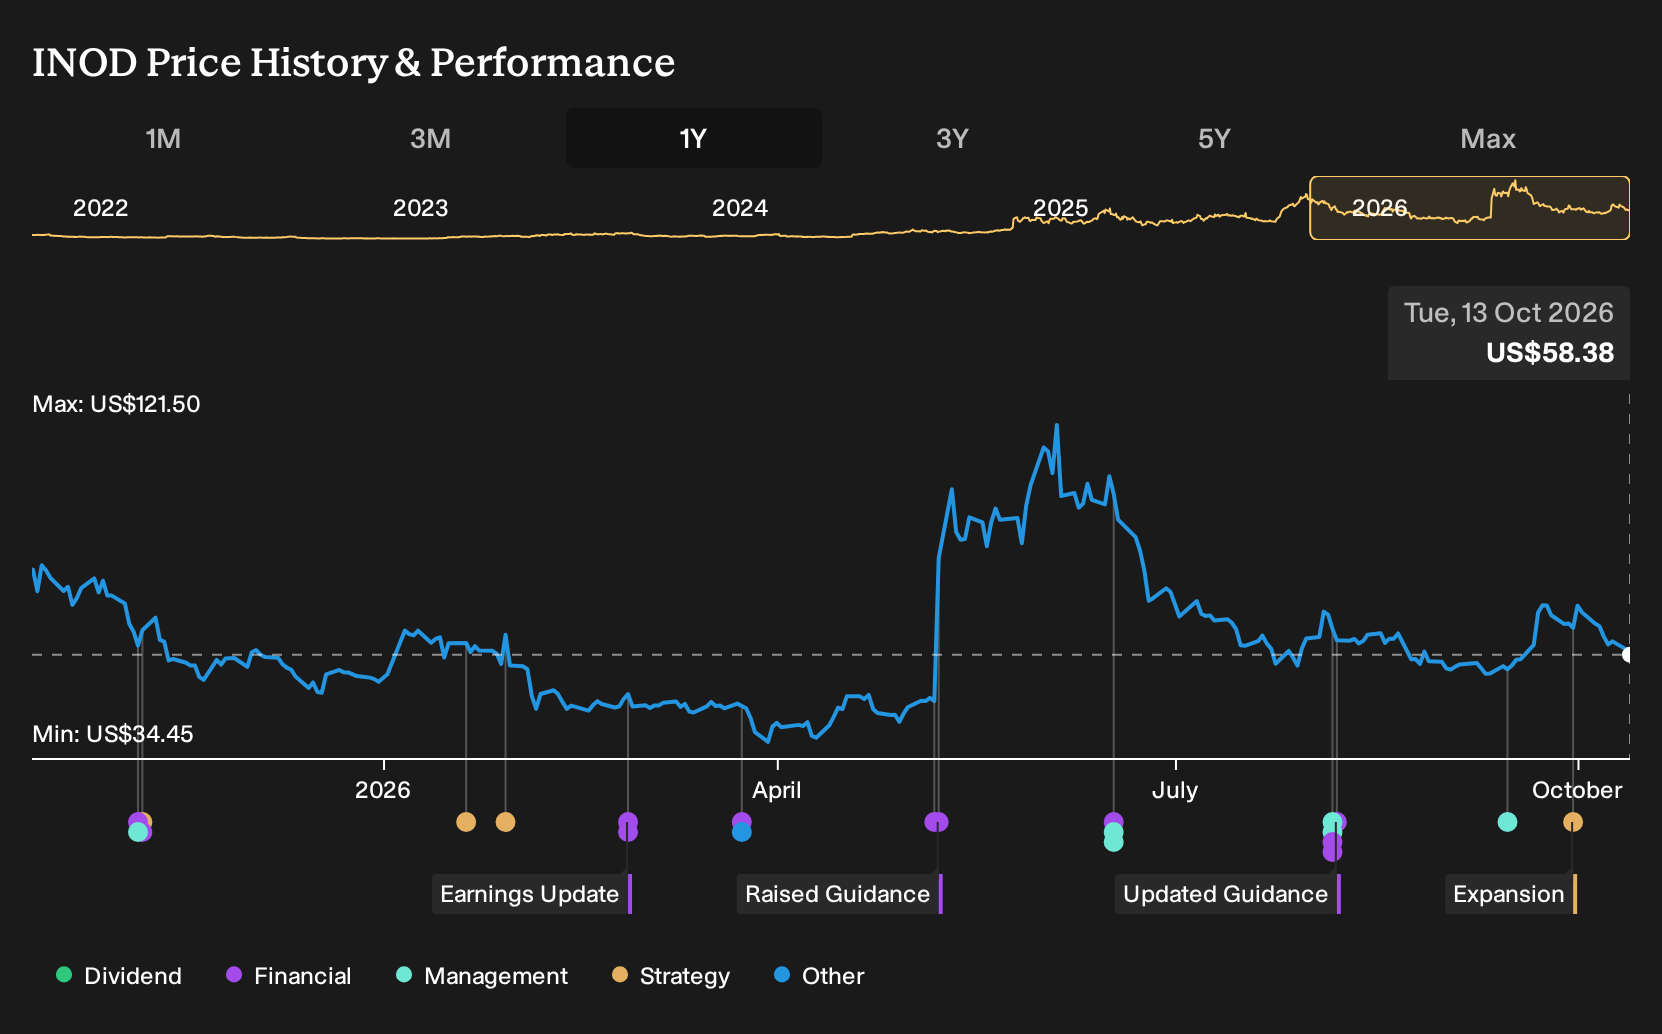
Innodata (INOD)
Overview: Innodata is a data engineering and AI services firm that builds and runs data pipelines, platforms, and tools for banks, insurers, healthcare, media, and technology clients worldwide.
Operations: Innodata generates most of its revenue in the United States at about US$273.7 million, with smaller contributions from Canada, the United Kingdom, the Netherlands, and other European countries totaling roughly US$43.4 million.
Market Cap: US$2.1b
Innodata matters for this banks-and-compliance screen because its AI data engineering work underpins exactly the kind of large, complex data projects regulators are now forcing big lenders to prioritize.
"Surging AI infrastructure spending and related capex by hyperscalers is creating a larger pool of long-term work for Innodata in model training, evaluation, and trust and safety services."
What happens to Innodata’s premium story if a single pressure point quietly shifts how much of that high-value work actually sticks?
That pressure point is exactly where the full narrative for Innodata shows how Innodata’s bank work, AI infrastructure demand, and compliance budgets could be quietly decoupling from the headline story.
TaskUs (TASK)
Overview: TaskUs delivers outsourced digital customer experience, AI data services, and trust and safety operations that large banks can tap for compliance heavy back-office workflows.
Operations: TaskUs generates about US$1.23b in Direct Marketing revenue, with key delivery hubs in the Philippines, India, the United States, and the Rest of World.
Market Cap: US$733 million
TaskUs matters for this screener because its outsourced operations and AI driven services line up neatly with the kind of remediation and monitoring work big lenders are now under pressure to scale without ballooning in house fixed costs.
"TaskUs is investing heavily in AI services and technologies, including Agentic AI and generative AI services, and management now points to seven consecutive quarters of more than 25% AI Services growth and an expected re acceleration above 30% in Q4 2026 as evidence that this segment is becoming a larger contributor to revenue."
What happens to TaskUs’s margins if a single unresolved pressure point quietly shifts where the most complex, compliance heavy workflows end up?
That unresolved pressure point is exactly where the full narrative for TaskUs shows whether accelerating AI services growth is masking risk or setting TaskUs up for a stronger mix shift.

Robert Half (RHI)
Overview: Robert Half provides talent solutions and consulting services that help banks and large enterprises resource finance, technology, and risk projects.
Operations: Robert Half generates most of its revenue from Contract Talent Solutions at about US$3.4b, with Protiviti contributing roughly US$1.9b.
Market Cap: US$3.5b
Robert Half matters for this screen because Protiviti’s consulting bench and the group’s staffing reach give large banks flexible capacity for complex regulatory remediation and process change work when internal teams are already stretched.
"As businesses continue investing in digitization and business transformation, including technology modernization, AI readiness, ERP upgrades and cybersecurity, the demand for skilled technology and finance talent at Robert Half is expected to support higher placement volumes and future revenue growth."
What happens to Robert Half’s earnings power if one less visible shift in enforcement intensity quietly rewrites the mix of that high value work?
That quieter shift in enforcement is exactly where the full narrative for Robert Half shows whether Robert Half’s regulatory work is quietly accelerating or masking deeper mix risk.

Seeking Alternatives Before The Crowd
Fresh ideas tend to move first and slower portfolios can get left behind. Use this moment while it matters, while prices still look relatively quiet, and consider positioning early.
- Identify potential steady compounders before they attract wider attention by running the list of solid balance sheet and fundamentals (25 results) and focusing your watchlist on businesses with financial resilience.
- Look for early breakout potential in overlooked miners by scanning the 36 elite gold producer stocks and concentrating on producers that may be more sensitive to gold price movements.
- Monitor infrastructure themes linked to AI data centers by checking the 43 power grid technology and infrastructure stocks and focusing on utilities and equipment suppliers involved in that backbone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com