


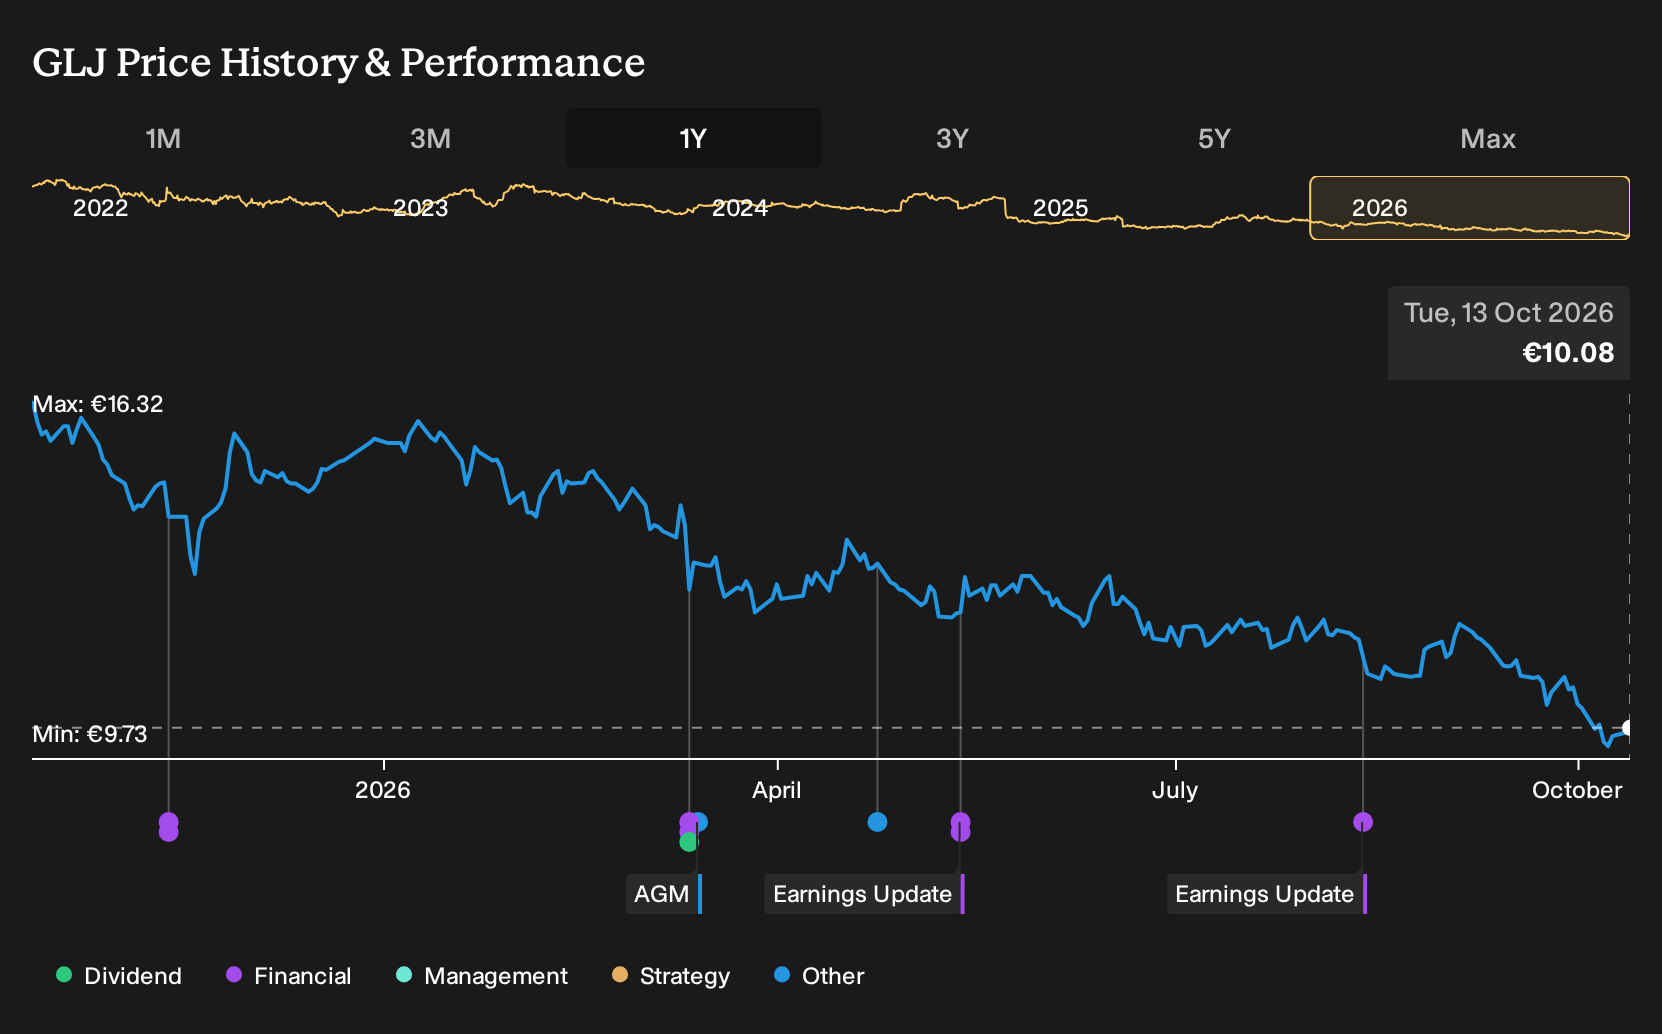
Grenke’s latest quarterly update on 13 August 2026 showed revenue of €181.809 million and net income of €15.981 million, with the net margin slipping to 8.8%. Holding Grenke over the past year would have meant a 34.8% loss, including dividends. If you had committed fresh capital in October 2025, that is the outcome you would be assessing today. What did that drop indicate about digitization, green leasing, and SME demand?
If the move has made Grenke harder to judge, start where the gap is still open and scan 185 high quality undervalued stocks.
The Two Stories Grenke Investors Were Choosing Between
The shares cost €16.32 at the start of the period, and anyone looking at Grenke then had to choose between two very different stories about its future.
The bullish view saw a Fair Value of €30, a notional target based on the idea that digitalization and automation would lift margins as AI reduced headcount needs and green leasing volumes climbed. Supporters of this case also assumed revenue could grow 14.2% a year and net margins might rise from 7.1% to 19.7% by about 2028.
The bearish Narrative pointed to a Fair Value of €14.5, which reflected worries about subscription based models and fintech competitors eroding leasing demand and pricing power. This camp still assumed earnings could eventually reach €129.9 million, but expected flat to slightly declining revenue, at a 0.4% annual rate, and much lower future P/E multiples around 5.6x.
What The Results Changed For Grenke
Revenue at Grenke reached €181.809 million and net income came in at €15.981 million, both slightly above Q2 2025, while the net margin slipped from 9.6% to 8.8%. That mix gave the cautious case more support than the bullish one, because higher sales and profit did not bring the cleaner margin expansion the optimistic story leaned on.
The key lesson is simple. When a thesis leans heavily on efficiency and digital gains, it is important to keep checking whether net margin improves alongside revenue rather than assuming scale will do the work.
What Grenke’s Current Price Already Assumes
Grenke now trades at €10.08 after a 34.8% loss over the past year from €16.32. The selected bullish Narrative places its Fair Value above that level, based on how digital tools and SME demand might shape the leasing book and earnings profile.
For that higher figure to be reached, a buyer today would need to assume sustained SME appetite for tech and sustainability leasing that supports recurring business on acceptable risk terms.
"Growing demand among SMEs for investments in digital technology and sustainability (such as IT upgrades and green equipment) is driving recurring leasing activity and supports an expanding leasing portfolio, positively impacting Grenke's revenue growth outlook."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
Go Straight To The Source
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 24% below our estimate - uses a tech enabled platform so senior lawyers keep higher fees with lower overheads.
- Company 2 - 36% below our estimate - expands multichannel electronics retail by ramping new-format stores and linked online services.
- Company 3 - 35% below our estimate - ramps new high speed networking and AI hardware programs for large cloud infrastructure buyers.
Those are three of them. See every one of the 204 solid balance sheet companies →
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com