


Why Cipher Digital’s new zero-coupon notes matter
Cipher Digital (CIFR) has shaken up its capital structure with a US$850 million private offering of zero-coupon, convertible senior notes due 2032, issued under Rule 144A to qualified institutional buyers.
The bond issue includes several features that matter for both equity holders and credit investors. The securities are unsecured, rank as senior obligations, carry no regular interest payments, and can be called by the issuer, with detailed conversion terms to be set at pricing.
The use of proceeds is central to the reaction. Management plans to fund capped call transactions linked to share buybacks, expand the high performance computing data center pipeline, support the Barber Lake development, and cover general corporate needs, but not bitcoin mining expansion.
Equity traders have already expressed a view on this mix of funding and potential dilution. Cipher Digital’s stock fell about 12% on the announcement day, and the shares are down 33% over the past month and 43% in the past 3 months.
The reaction is part of a wider reset around Cipher Digital, with the share price down sharply in recent weeks and the one year total shareholder return down 45.72%, even though the three year total shareholder return is still more than 3x. Recent pressure has built as investors weigh the zero coupon convertible financing, a weaker 7 day share price return of 26.84% and expectations for a steep earnings drop. These factors point to fading near term momentum and a higher perception of risk around execution on the high performance computing build out.
Scan how other high performance computing and digital infrastructure plays are setting up for the next leg by reviewing our hand picked 92 AI infrastructure stocks alongside Cipher Digital.
After a 43% slide in three months and a fresh US$850 million zero coupon overhang, Cipher Digital now trades against very different expectations. The key question is whether that reset skews the risk reward toward patient buyers or toward caution as valuation comes into focus next.
Most Popular Narrative: 63% Undervalued
Cipher Digital last closed at $11.34, while the most followed narrative pegs fair value at $30.93, so the zero coupon notes land in a story that already assumes a big gap between price and modeled worth.
The progression in project level financing, including the $2b Black Pearl notes, the $810m Stingray notes and a committed $200m revolver, shows creditors are willing to fund construction against contracted cash flows. This is expected to support continued build out of the pipeline and influence future earnings through interest expense and construction pacing.
See why 94 investors see Cipher Digital as 63% undervalued.
Result: Fair Value of $30.93 (UNDERVALUED)
Still, the narrative around Cipher Digital could crack if heavy project debt keeps quarterly interest near US$67m or if ERCOT delays restrict key Texas power approvals.
Find out about the key risks to this Cipher Digital narrative.
Another View: Cipher Digital’s rich sales multiple
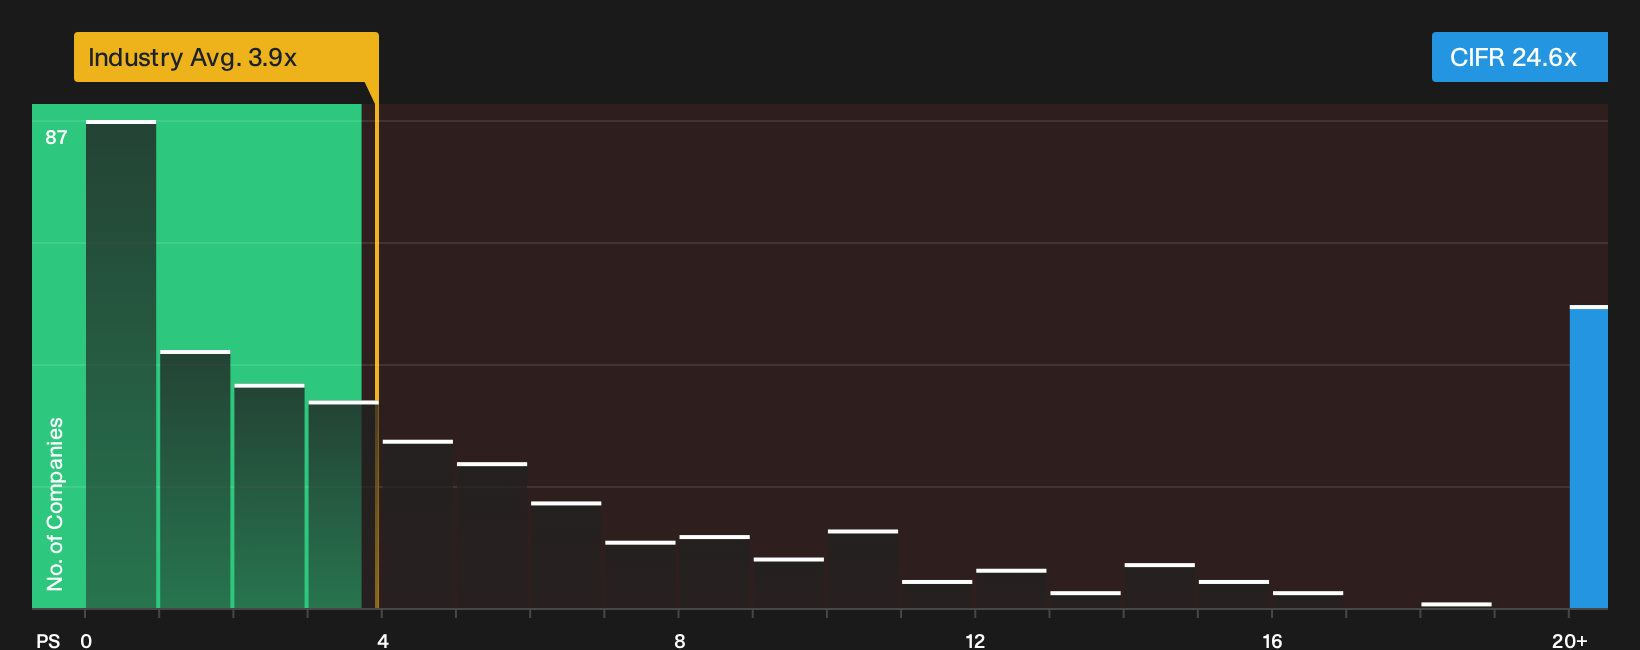
The fair value narrative around Cipher Digital leans on long term contracts and growth forecasts, yet the current P/S ratio of 24.6x is far higher than both the US Software industry at 3.9x and the estimated fair ratio of 3.2x. That kind of gap adds more valuation risk to any growth stumble or delay.
Investors weighing that disconnect can use our valuation breakdown as a cross check, then decide how comfortable they are with paying so far above the fair ratio for this story. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Cipher Digital’s setup has sent mixed messages so far. If that tension between risk and opportunity matters to you, take a closer look at the 1 key reward and 2 important warning signs.
Looking for more Cipher Digital sized ideas?
If Cipher Digital’s setup has your attention, do not stop here. Use a few focused stock lists to pressure test your next move and spot opportunities others overlook.
- Target potential mispricings by scanning a 32 high quality undervalued stocks that pairs quality fundamentals with compressed expectations.
- Prioritize resilience by reviewing a 32 resilient stocks with low risk scores that screens for sturdier balance sheets and lower risk scores.
- Hunt for future leaders early by checking a 20 high quality undiscovered gems that highlights under-the-radar businesses with strong underlying numbers.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com