


- Kyowa Kirin reported final data from the German MINT study of mogamulizumab in mycosis fungoides and Sézary Syndrome, showing a 14.9 month median time to next treatment, a 62.4% best overall response rate, 20.2 month median progression free survival, and quality of life gains in routine clinical practice.
- The study also found a safety profile consistent with earlier trials and meaningful responses across clinically relevant subgroups, which supports broader real world use of mogamulizumab in cutaneous T cell lymphomas and underlines Kyowa Kirin’s commitment to this niche oncology area.
- We will now look at how Kyowa Kirin’s investment narrative could be affected by mogamulizumab’s real world durability in cutaneous T cell lymphomas.
Scan Kyowa Kirin’s peers tackling complex oncology problems and see which ones land on our hand picked 9 healthcare AI stocks list for potential next ideas.
What Is Kyowa Kirin's Investment Narrative?
To own Kyowa Kirin, you have to believe in a focused specialty pharma story, not a broad high growth platform. This is a ¥1.18t enterprise with established products, moderate revenue growth of 1.9% a year forecast, and earnings expected to rise 3.7% annually. The MINT data on mogamulizumab speaks to execution in niche oncology and could help sustain demand and pricing in cutaneous T cell lymphomas, but on its own it does not change the near term earnings profile in a sweeping way.
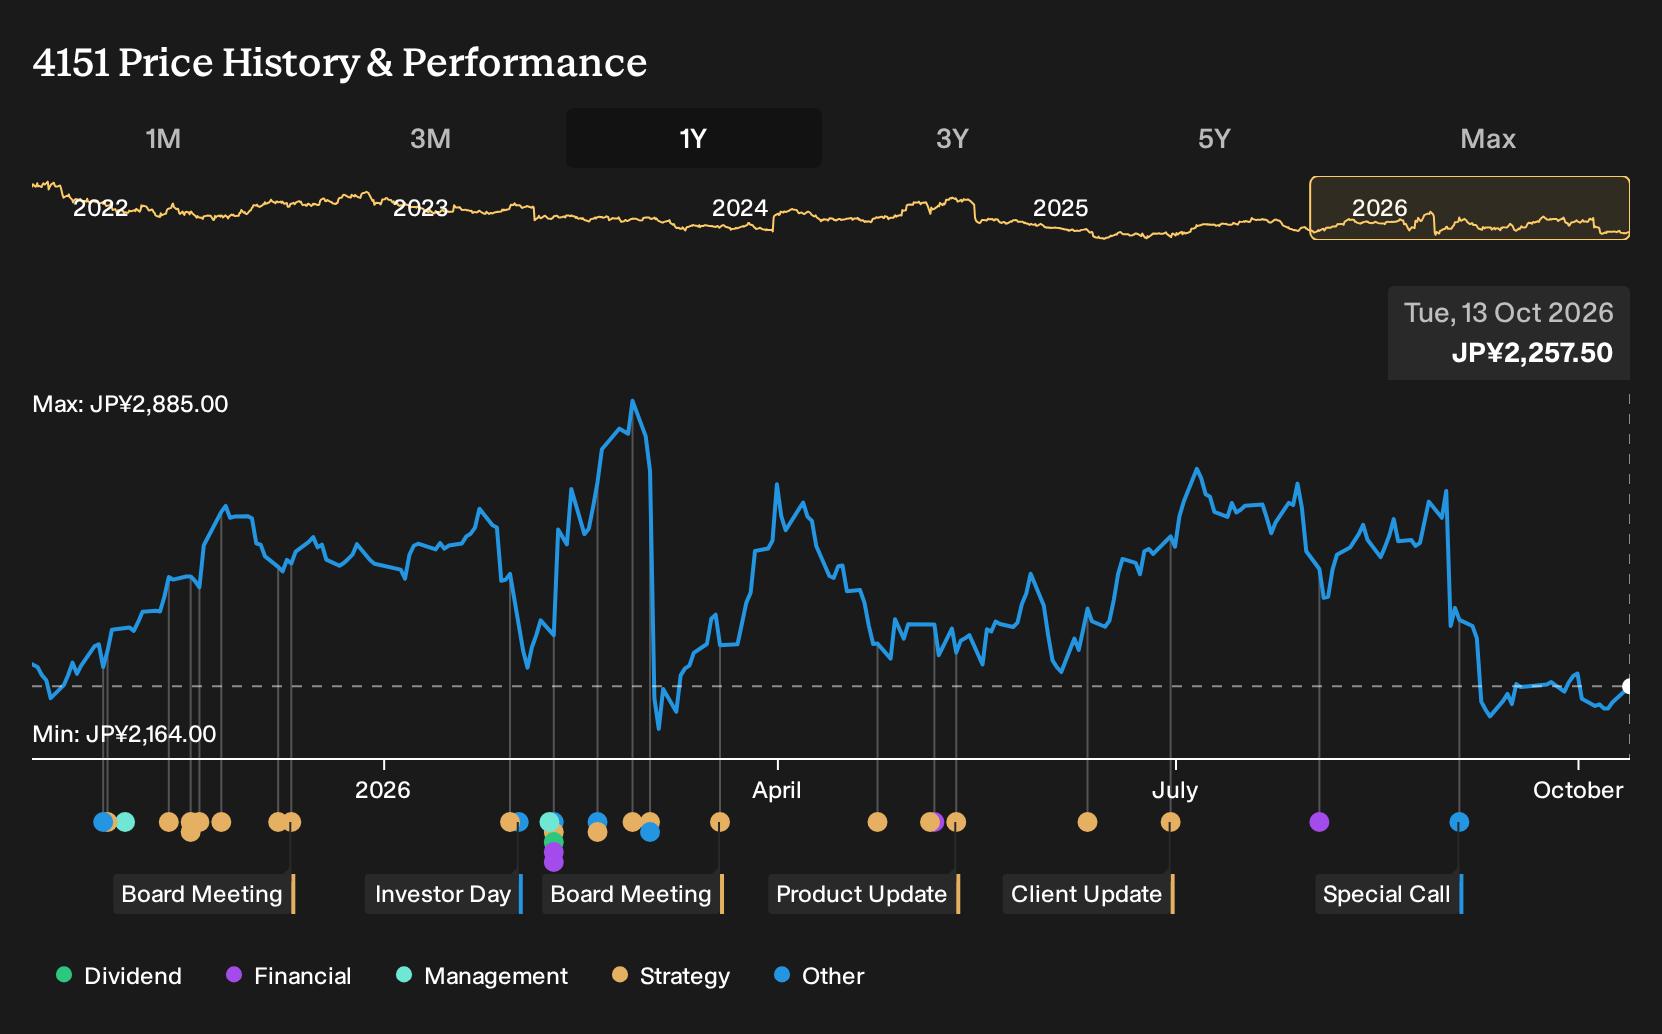
In the short term, the real questions are how efficiently Kyowa Kirin funds and advances its late stage pipeline while maintaining a 3.1% dividend, and whether management turns recent 111.7% earnings growth into something steadier, as the share price has still declined about 10% year to date. The stock screens as good value on several measures, including a P/E of 14.5x below a fair multiple estimate of 20.9x and a price below an internal cash flow value estimate. However, returns over 3 and 5 years have been weak, which keeps execution and capital allocation firmly in the spotlight.
Even so, there is a quieter issue in the Kyowa Kirin story that could matter more than mogamulizumab’s latest success...
There's only one way to know the right time to buy, sell or hold Kyowa Kirin. Head to Simply Wall St's company report for the latest analysis of Kyowa Kirin's Fair Value.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kyowa Kirin research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Kyowa Kirin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kyowa Kirin's overall financial health at a glance.
Looking For More Ideas Beyond Kyowa Kirin?
If you want to cross check Kyowa Kirin against other potential opportunities, it can help to scan groups of stocks that already match the kind of traits you are looking for.
The Simply Wall St Screener lets you jump straight to shortlists that fit specific themes and financial profiles. A few useful starting points are:
- If capital preservation sits high on your priority list, start with a group of 24 resilient stocks with low risk scores that may better fit a steadier temperament.
- If strong balance sheets appeal to you, focus on companies in the list of solid balance sheet and fundamentals (21 results) and compare their financial footing to Kyowa Kirin.
- If you like backing future potential before the wider market catches on, spend time with the 74 high quality undiscovered gems and see which stories you want to research next.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com