


AS ONE (TSE:7476) drew fresh attention after reporting preliminary August 2026 net sales of ¥8,777 million, compared with ¥8,423 million a year earlier, alongside a board meeting to consider cancelling treasury shares.
AS ONE’s latest trading update and move to consider cancelling treasury shares arrive after a steady build in momentum, with a 90-day share price return of 4.32% and a 1-year total shareholder return of 6.34%, even as the 5-year total shareholder return declined 28.42%.
Compare AS ONE’s latest update with a hand picked group of companies showing similar momentum and capital discipline using the 13 high quality undervalued stocks.
AS ONE now trades at ¥2,533 while analyst targets and intrinsic value estimates sit meaningfully higher. Is that gap a genuine margin of safety, or just optimistic modelling meeting a recovering share price?
Most Popular Narrative: 20% Overvalued
On the most followed valuation view, AS ONE screens at a fair value of ¥2,113.81 versus the latest close of ¥2,533, which puts the narrative in clear focus for anyone weighing that pricing gap.
FY3/27 expected to be a transitional year. AS ONE delivered full year operating profit growth ahead of revenue growth in FY3/26, demonstrating the operating leverage in its model. The FY3/27 financial guidance points to a year of growth investments, which should translate to profitability improvement in future years.
See why 1 investors see AS ONE as 20% overvalued.
Result: Fair Value of ¥2,113.81 (OVERVALUED)
Still, AS ONE’s heavy FY3/27 investment plans and the tender offer priced at ¥2,151 could both unsettle sentiment if execution or capital allocation disappoints.
Find out about the key risks to this AS ONE narrative.
Another View: AS ONE Through A Cash Flow Lens
A very different picture appears when AS ONE is run through the SWS DCF model. On this approach, the shares trade at ¥2,533 against an estimated future cash flow value of ¥3,905.73, which points to the stock being undervalued on this framework.
This gap contrasts with the overvaluation suggested by the earnings based fair value of ¥2,113.81 and leaves you asking which set of assumptions feels more realistic for the next stage of AS ONE’s journey.
Look into how the SWS DCF model arrives at its fair value.
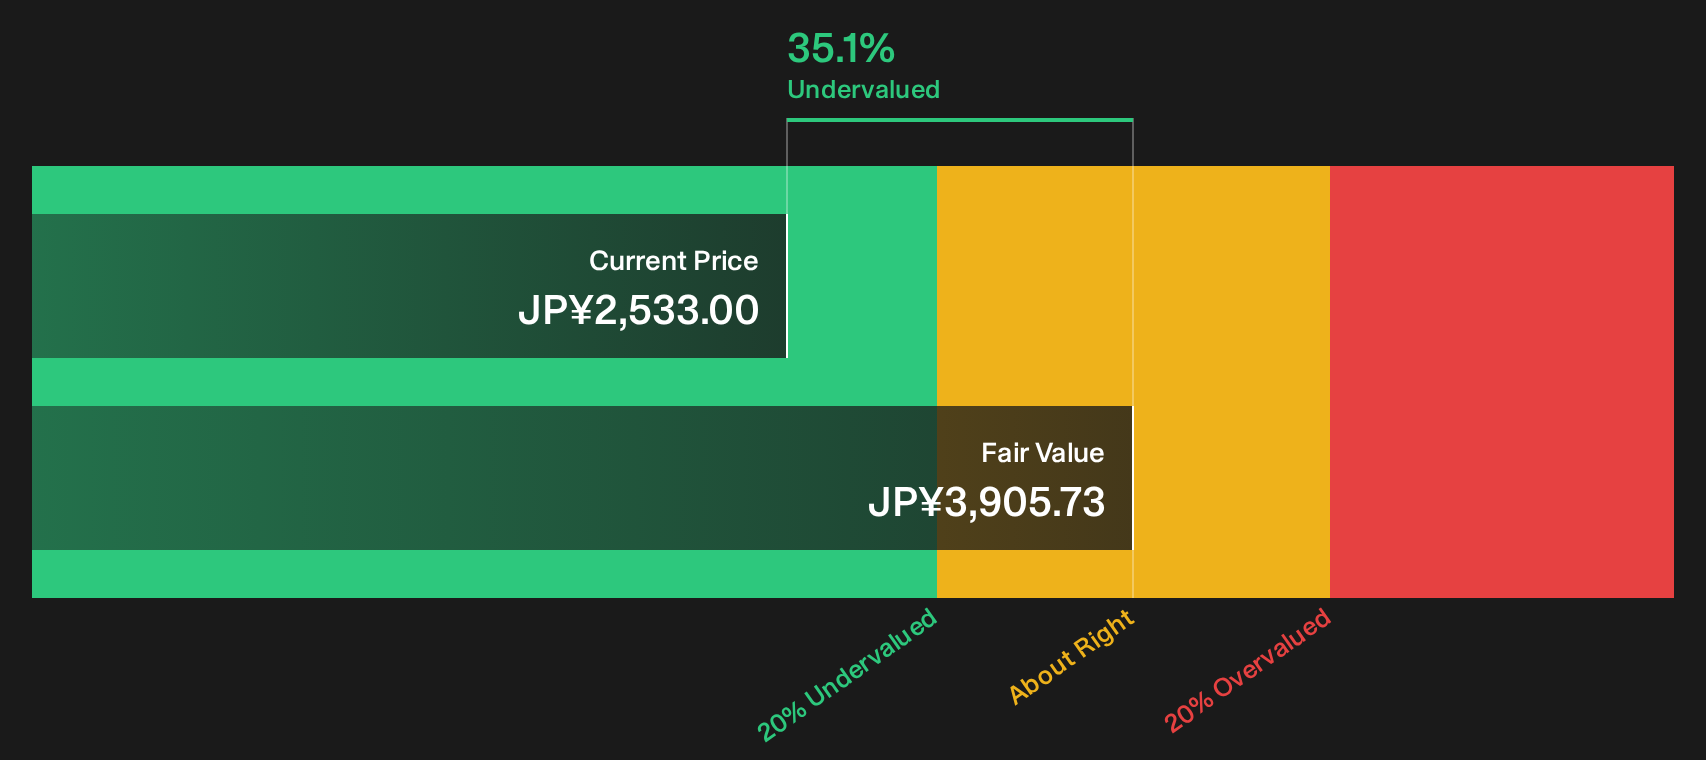
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out AS ONE for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 13 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on AS ONE’s valuation and outlook can feel confusing, so consider reviewing the underlying numbers yourself promptly and weighing both the upside and the downside in the 3 key rewards and 1 important warning sign.
Looking for more AS ONE investment ideas?
If AS ONE has sharpened your focus on valuation and risk, do not stop here. Broaden your watchlist now using targeted stock lists built from hard data.
- Target potential mispricings by reviewing the 13 high quality undervalued stocks that pair solid fundamentals with attractive entry points.
- Strengthen your income stream by scanning the 27 dividend fortresses that combine higher yields with an emphasis on resilience.
- Protect the downside first by filtering for the 24 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com