


Yingxi announced a net profit increase of more than 400%, but the stock price fell by 12.5%. The advantage “runs counter” to the stock price. Did the performance of Translink (01473) fall short of expectations or was it “realized”?
The Zhitong Finance App learned that on October 12, TransLink issued a positive profit forecast. It is expected that earnings will increase by more than 80% for the six months ending September 30, 2026, while the unaudited comprehensive profit for shareholders is not less than HK$80 million, an increase of more than 400% over the previous year. The increase in performance was mainly driven by an increase in sales orders for the company's fulfillment and delivery of a large number of 200Gb/s inphosphide photodiodes (PD) products.
Benefiting from continued growth in global demand related to artificial intelligence, as of July 2026, the total value of the company's on-hand sales contracts has further increased to about US$1.15 billion. Currently, it is delivering about 15 million PD products per month. This delivery volume is expected to increase further in the second half of this fiscal year and the next fiscal year. The company's revenue has been growing for five consecutive fiscal years, and profits have continued to grow for three consecutive fiscal years.
In the capital market, the stock price of Translink opened higher due to favorable performance, but was lower. The closing price fell by 12.5%. In fact, looking at the extended cycle, the company began a bull market in July 2025, and the stock price continued to rise sharply. On May 18, 2026, the stock price nearly tripled in just ten trading days, then fluctuated at a high level. Up to now, the range increase is still more than 10 times. How far can the company go when the benefits of the high position have been realized?
Strong performance growth, structural upgrades enhance profitability
The Zhitong Finance App learned that Translink supplies a comprehensive portfolio of optoelectronic and semiconductor components, including integrated circuits, lasers, photodiodes (PDs) and related devices. These devices can enable AI data center applications and electro-optical and photoelectric signal conversion within the 800G/1.6T/3.2T module for optical interconnection. The company sees opportunities in the AI industry and is increasing its emphasis on areas surrounding AI, such as AI data infrastructure optical components.
The company's performance grew strongly. From fiscal year 2024 to fiscal year 2026, revenue was expected to increase by 15.48%, 53.77% and 4.77%, respectively, and shareholders' net profit began to turn a loss into profit in fiscal year 2025. The forecast growth for the first half of fiscal year 2027 exceeds 419.5%, and the profit amount exceeds the net profit of the previous two full fiscal years. The inflection point of performance can be seen from this.
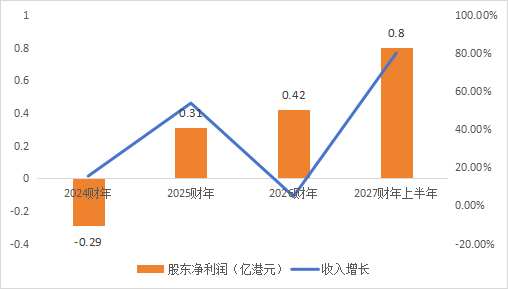
Data source: Company financial reports and announcements
There are two main reasons for this sharp increase in predicted performance: First, the product structure changed. The company closely followed the AI trend and accelerated supply upgrades to optoelectronic and semiconductor components in recent years. 200Gb/s indium phosphide PD used AI data center 800g/1.6T/3.2T optical modules (rate specifications for next-generation high-speed optical interconnection) to launch, increasing the proportion of high-value-added products, driving the gross margin center upward; second, the scale effect is showing. The volume of deliveries climbed to about 15 million units per month, optimizing the cost ratio under operating leverage, and adding a daily increase in high-power industrial laser business, overall profit margin Further improvement.
TransLink has seen a new growth variable. The company recently signed an exclusive supply agreement for high-power laser light source systems with a leading domestic and global manufacturer of printed circuit board (PCB) laser drilling equipment. The products are used in the production of high-rise digital high-density interconnect (HDI) and ultra-HDI boards. It has been delivered since October 2026. It is expected to deliver no less than 500 pieces and generate no less than 55 million US dollars this fiscal year.
This business is expected to create a new growth pole for the company. Demand for the bandwidth of large-scale artificial intelligence systems is increasing, and the industry is accelerating the transformation to 1.6T and 3.2T interconnect hardware. As the AI infrastructure investment cycle progresses, demand for high-speed and high-precision laser processing (including micro-drilling, fine line circuit structuring, and other precision manufacturing processes) is expected to grow along with it. Furthermore, the company's transimpedance amplifiers (TIA, amplification chips in the optical signal conversion process) are being certified by customers, and CW lasers (continuous wave lasers) are entering the sample testing phase.
Ongoing orders exceed US$1.1 billion, and the valuation trend has yet to be verified
As we all know, most Hong Kong stocks lack transactional liquidity, and “storytelling” has become an important strategy to increase trading activity and market value management for small and medium market capitalization with no volume or low volume.
TransLink entered the Hong Kong stock market in 2021, but the decline in performance led to a continuous decline in valuation. Until March 2025, the company began a reversal by turning losses and profits. In July of the same year, placement and fund-raising was invested in the AI sector. Driven by performance growth and new stories, the market also voted enthusiastically, and began an upward valuation cycle after increasing trading volume. The company's orders exploded in 2026, and the upward trend in valuation accelerated.
In January of this year, the company announced that it had received sales orders with a total value of more than 208 million US dollars. The market capitalization increased by more than 30% in the same month. In June, it announced that the total number of orders exceeded 1 billion US dollars. However, market foresight and foresight continued to rise sharply in May and June, with a total increase of 232.7%. It entered a high level of adjustment in July-August, and began moving north in September. Up to now, the company's stock price has increased 2.64 times this year, and has increased more than 10 times since July 2025.
In addition, the AI concept is being hyped up. GEM Zhongji Xuchuang's listing in Hong Kong made the AI optical interconnection concept popular. Chairman Feng Ruijiang revealed an increase in holdings twice in July and September, and some institutions also entered the market at about HK$1.15 at the end of August. The “real money” signal compounded the long-term lack of investment banking coverage, boosting market confidence.
However, performance is still the biggest core variable in valuation. TransLink is expected to maintain high growth in the second half of fiscal year 2027, mainly due to unfinished orders of about US$1.15 billion, guidance on a “further increase” in monthly PD deliveries, and revenue promises of not less than 55 million US dollars for laser light source systems, which together form the basic market for the second half of the year and the next fiscal year. Furthermore, if TIA certification is implemented and CW laser testing is converted to mass production, the product portfolio is expected to move from single-point PD emission to multi-point flowering and enter multiple driving modes.
It is worth noting that the company's profit margin is not high, but it is showing an upward trend, so there is plenty of room for improvement. From fiscal year 2024 to fiscal year 2026, gross margin and net shareholder margin were only 8.45%, 10.39%, 10.9%, and -2.1%, 1.16%, and 1.86% respectively, which is expected to exceed 4.22% in the first half of fiscal year 2027. The company did not have sufficient cash flow. The balance ratio for the 2026 fiscal year reached 69.3%, while the cash equivalent was HK$97 million.
Taken together, this sharp increase in interim results is contrary to market capitalization; in fact, it is a short-term pressure on profit markets caused by high short-term stock prices after the results were realized. The company's AI optical interconnection logic has moved from the storytelling stage to the “handover” stage. It has an order of 1.15 billion US dollars, which is equivalent to 4 times the revenue for the 2026 fiscal year, 5.7 times the current market value. Monthly orders continue to grow. Whether the valuation can be further revalued depends on the continuity of delivery and fulfillment.
On the one hand, there is a high degree of certainty that orders, revenue, and profits will rise, and on the other, the reality of short-term high levels and high volatility. Whether valuations can maintain an upward trend is left to be verified one by one with the complete interim results and the full year results for FY2027.