


If you had backed the upbeat October 2025 story on urban growth, e-commerce and leaner stores at Bata India, the outcome would have been jarring. Holding Bata India over the past year would have meant a 42.7% loss, including dividends. Yet recent results show higher quarterly revenue and a stronger net margin than a year earlier. If those original bullish and bearish cases framed your decision, which specific assumptions on growth, margins or future P/E proved too optimistic or simply too early?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
If the move has made Bata India harder to judge, start where the gap is still open and scan 184 high quality undervalued stocks.
The Two Stories Investors Had To Choose Between On Bata India
The shares cost ₹1,150 at the start of the period, and anyone looking at Bata India then had to pick between two very different but credible stories.
The optimistic camp saw a Fair Value of ₹1,394, anchored in assumptions that revenue could rise 9.2% a year and profit margin could reach 10.0%, helped by leaner stores, new brands and faster digital growth.
The cautious view put Fair Value at ₹850 and treated 6.3% annual revenue growth, an 8.2% margin and a 48.5x future P/E as still exposed to digital delays, intense competition and cost pressure.
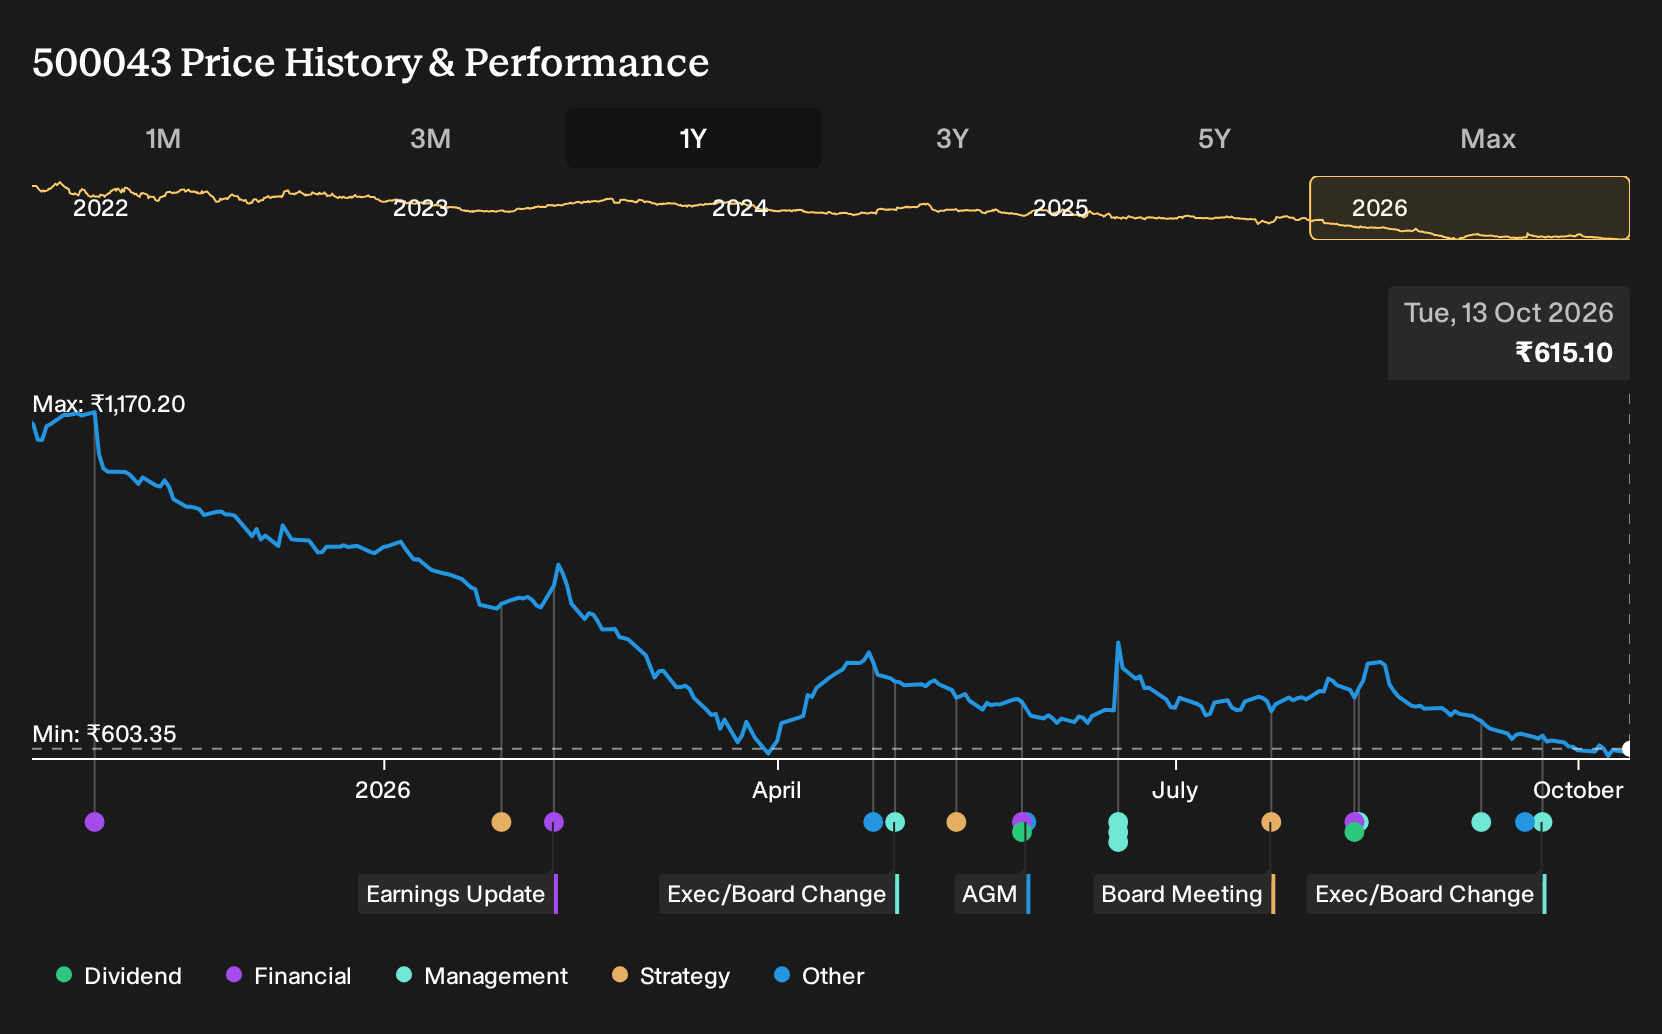
What The Results Changed For Bata India
The clearest new fact was profit quality. Bata India reported net income of ₹639.84m in Q1 2027 versus ₹519.99m in Q1 2026, with net margin moving from 5.5% to 6.5%. Revenue of ₹9,789.47m sat above ₹9,418.54m. Higher sales and a wider margin both leaned toward the optimistic case, although still short of a 10.0% target.
The key lesson is simple. When a thesis depends on a margin reset, track the reported net margin each year and compare it with the exact percentage baked into the original story.
What You Would Be Paying For In Bata India Today
Bata India trades at ₹615 after a 42.7% loss over the past year, while the selected Narrative’s Fair Value sits above the current price. That view leans on a leadership transition plus store, brand and digital changes that, in combination, aim to reshape earnings quality.
For that higher figure to be reached, a buyer today would need to see sustained margin improvement as leaner stores, franchises and digital channels scale.
"While analyst consensus expects Zero-Based Merchandising (ZBM) to deliver incremental revenue per square foot and net margin improvement, the pace of scaling ZBM to core, high-turnover stores is accelerating faster than anticipated, potentially allowing Bata to exceed analyst expectations for ROIC and drive a step-function increase in margins and earnings as more of the store network transitions to lean, high-efficiency formats."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
What Else Bata India Hints At
Watching Bata India means watching what customers quietly value in shoes.
Price, story and experience merge into something people feel rather than calculate.
Step one level out and the same instinct shapes other purchases too.
Shoppers pay for heritage, for reassurance, for products that feel like symbols.
Another global group builds on that emotional premium, turning craft and history into desire.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 95% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com