


- Smith & Nephew has filed a US$175.24m shelf registration for 6,500,000 American Depositary Shares linked to an ESOP offering and has redeemed its US$350m 5.150% notes due 2027, while also confirming that the CARTIHEAL AGILI-C Cartilage Repair Implant is now commercially available across multiple European markets.
- The European roll out of the aragonite based CARTIHEAL AGILI-C Implant, supported by long term randomized trial data on pain relief and daily function, signals Smith & Nephew’s efforts to convert advanced cartilage repair demand into a broader, procedure driven product ecosystem.
- We will now assess how Smith & Nephew’s European AGILI-C rollout could influence its investment narrative around product-led orthopaedic expansion.
Scan how Smith & Nephew’s cartilage push compares with other medical stocks by checking the hand picked 7 healthcare AI stocks that could benefit from similar procedure driven demand trends.
Smith & Nephew Investment Narrative Recap
To own Smith & Nephew, you need to believe that new products in orthopaedics, sports medicine, and wound care can keep benefiting from clinical adoption, while the 12 Point Plan keeps margins moving in the right direction. The European AGILI C rollout fits that thesis but does not overhaul it. In the near term, execution in U.S. knees and orthopaedics, plus operational delivery, still looks like the key swing factor.
The bigger risk for shareholders remains policy and pricing pressure. Medicare changes for skin substitutes, Chinese volume based procurement, and tariffs can all squeeze Advanced Wound Management and sports lines. The AGILI C launch and the debt redemption do not remove those pressures, so reimbursement outcomes and pricing discipline still matter most.
The most relevant move here is the European launch of the CARTIHEAL AGILI C Cartilage Repair Implant. This product supports Smith & Nephew’s positioning that newer implants and procedures, backed by controlled trial data, can deepen its orthopaedics footprint and connect with other tools such as CORI robotics over time. That is where many investors look for incremental growth.
Multiyear data on pain relief and daily function give surgeons reasons to consider switching procedures, which can support procedure volumes and associated kit pull through if adoption holds. The flip side is execution risk. Training, reimbursement decisions in each market, and competition in cartilage repair all influence how much this actually contributes to the broader new product catalyst investors are watching.
Smith & Nephew's current analyst narrative points to US$7.4b revenue and US$978.1m earnings by 2029, implying 5.4% yearly revenue growth and an earnings increase of about US$343m from US$635.0m today.
Uncover why Smith & Nephew's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
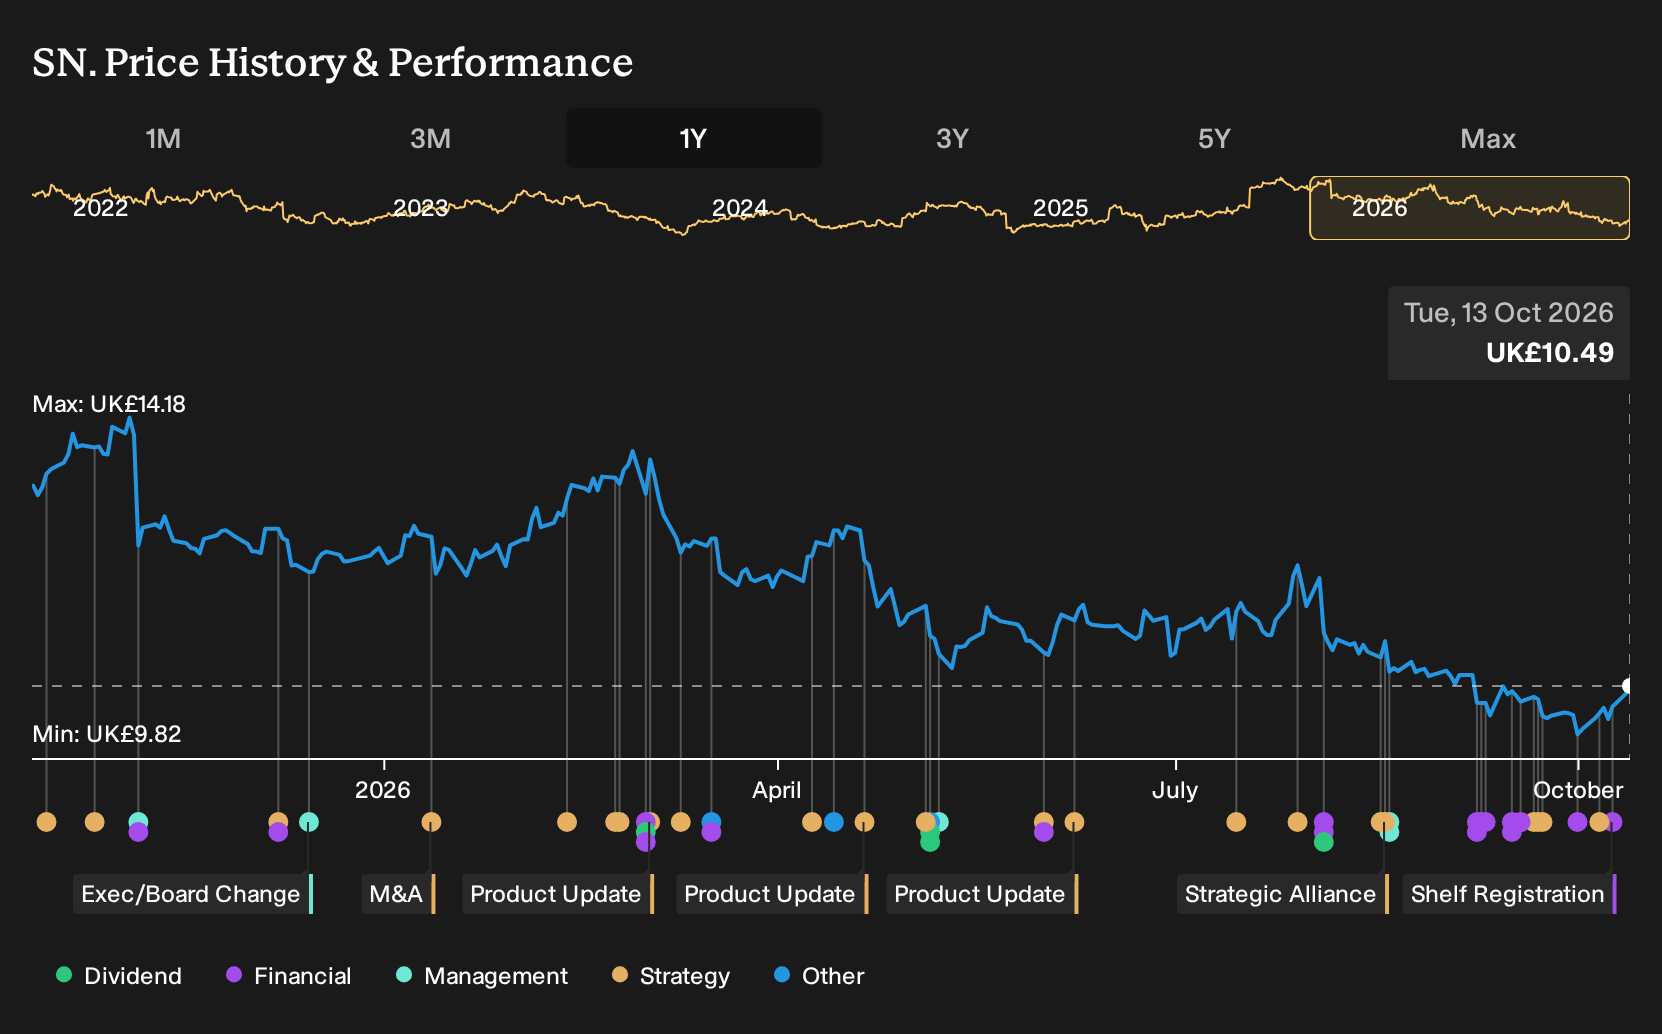
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$12.57 and US$17.45 per Smith & Nephew share, which leaves room for disagreement if Medicare changes, tariffs, or China pricing pressure become more significant than expected. Use that spread as a prompt to explore multiple viewpoints before committing fresh capital.
Explore another Smith & Nephew fair value estimate, including one that suggests potential upside of as much as 66% from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Smith & Nephew research is our analysis highlighting 6 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Smith & Nephew. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Smith & Nephew's overall financial health at a glance.
Looking for more investment ideas beyond Smith & Nephew?
If the Smith & Nephew story has sharpened your thinking, you can use that momentum to scan a wider field of opportunities with the Simply Wall St Screener. Different filters can help you focus on the kind of businesses that best suit your risk tolerance and income goals.
- If capital preservation sits high on your priority list, you could start with a group of companies screened for resilience and lower risk profiles through the 4 resilient stocks with low risk scores.
- For readers interested in strong fundamentals at reasonable prices, you can review a curated pool of potentially mispriced quality stocks using the 8 high quality undervalued stocks.
- Income focused investors can look at stocks with higher yields and longer payout records by scanning the 2 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com