


Danaher (DHR) has moved deeper into AI-enabled science, unveiling a collaboration with NVIDIA that aims to plug accelerated computing directly into its instruments, software and lab automation workflows.
Recent trading shows interest building around Danaher. The 30-day share price return of 11.34% and 90-day gain of 10.98% suggest momentum has picked up, even though the year to date share price is down 3.28% and the 5-year total shareholder return has declined 16.40%.
Scan how Danaher’s AI push compares with other lab and biotech players by reviewing a curated set of 33 healthcare AI stocks moving on similar catalysts.
After an 11.34% 30 day jump, Danaher still trades at a small intrinsic discount and a wider gap to analyst targets. Is that a cautious market misread, or a fair response to margin and earnings pressure?
Most Popular Narrative: 6% Undervalued
At a last close of $222.84 against a widely followed fair value estimate of $236.32, the current narrative frames Danaher as modestly undervalued while still pricing in a meaningful recovery across its core franchises.
Accelerating demand for biologics and single use bioprocessing equipment, reflected in more than 30% year over year growth in bioprocessing equipment orders in early 2026 and mid teens order growth for consumables and equipment in Q2 2026, supports expectations for a multiyear capacity investment and onshoring cycle that can lift Biotechnology segment revenue and operating leverage.
See why 80 investors see Danaher as 6% undervalued.
Result: Fair Value of $236.32 (UNDERVALUED)
Still, the story can break if bioprocessing order volatility persists or if China pricing and reimbursement pressure deepen and drag on Danaher’s Diagnostics trajectory.
Find out about the key risks to this Danaher narrative.
Another View: What Danaher’s P/E Is Really Saying
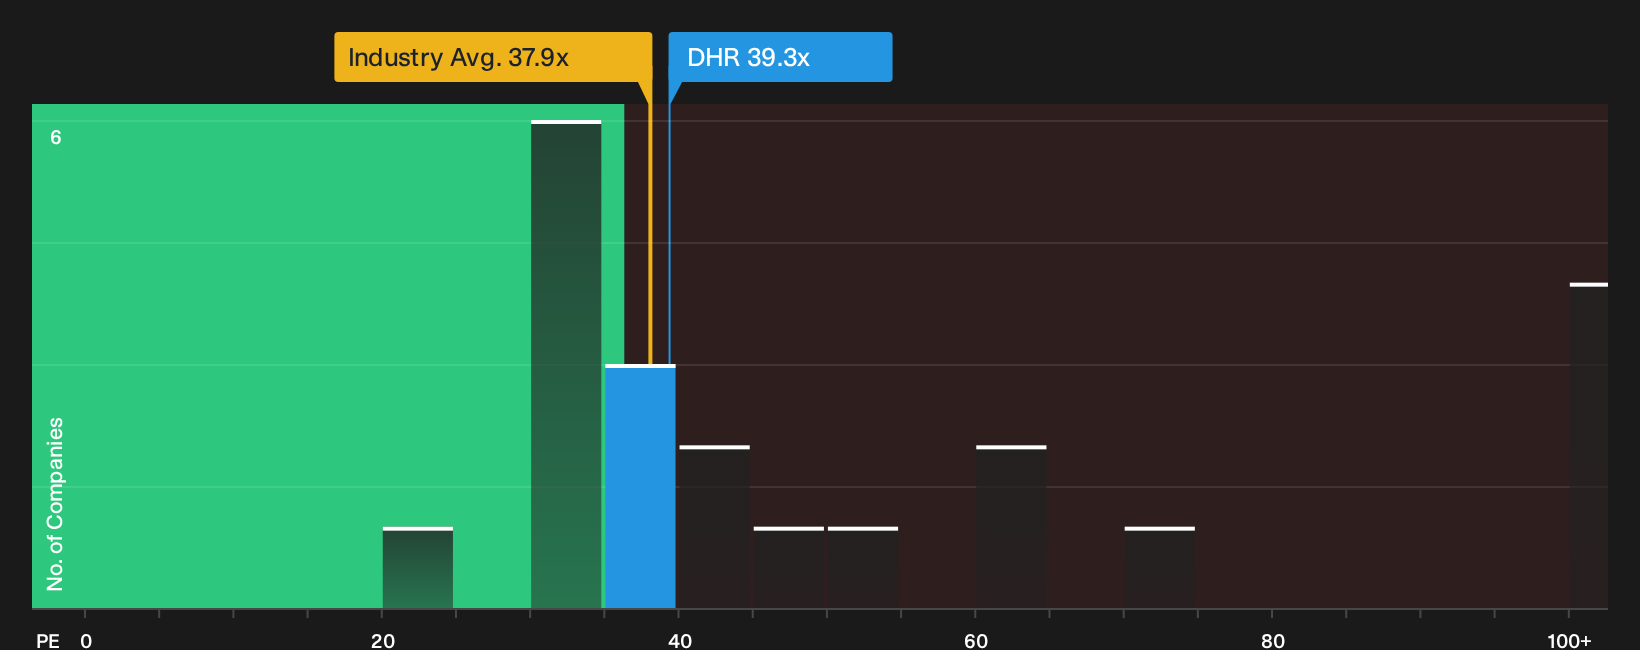
On the DCF screen, Danaher looks modestly undervalued, trading about 1.4% below an estimated future cash flow value of $226.05. The picture shifts when pricing is compared with earnings. The current P/E of 39.3x sits above the 33.4x fair ratio, the 37.9x global Life Sciences average, and the 37.4x peer group figure, which points to a richer tag if earnings stumble or sentiment cools.
That mix of a small DCF discount and a premium P/E multiple leaves a simple question for investors: Which signal matters more for Danaher at $222.84, cash flow math or what the market already pays for each dollar of profit?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Danaher often come down to how you weigh its risks against its potential rewards, so move quickly, review the underlying data, and decide whether the balance of 3 key rewards and 2 important warning signs aligns with your own view.
Looking for more investment ideas beyond Danaher?
You have a clear view on Danaher now, so use that momentum and widen your watchlist with a few targeted stock ideas that fit your style.
- Target resilient compounding potential by scanning 32 high quality undervalued stocks, which pair quality fundamentals with prices that lag their underlying strength.
- Hunt for steady income by reviewing 8 dividend fortresses, which aim to combine higher yields with balance sheets built to handle stress.
- Sharpen your risk control by focusing on 32 resilient stocks with low risk scores, so you are not relying on just one story to shape your portfolio.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com