


Mastercard has delivered strong returns in recent years, and with the stock last closing at US$604.80 the live question is whether that price is supported by the returns the business earns on its capital. Recent deals in areas like stablecoin infrastructure and AI driven payments add new storylines, but they also raise a practical issue for you as a shareholder, which is how these moves may feed into long term profitability on each dollar invested in the business.
- Over the past 5 years, Mastercard shares have returned 72.1%, which puts real weight on whether the underlying return on capital is strong enough to justify that kind of compounding.
- The US$1.8b acquisition of BVNK and the push into AI powered trust and intelligence services can reshape how much Mastercard needs to invest and how much profit it may eventually earn on those added assets.
- What if you looked at Mastercard through its earnings instead? See why Mastercard's 32.6x P/E tells a different valuation story.
The issue now is whether Mastercard's current share price is properly aligned with the returns it earns on its capital and the reinvestment opportunities those returns support.
If you want more ideas built around similar themes of returns on capital and real earning power, consider a focused stock screen of 32 high quality undervalued stocks.
Is Mastercard Still Cheap on Excess Returns?
The Excess Returns model looks at how much profit Mastercard can earn above its cost of equity on each dollar of shareholder capital. Here that spread is wide. Against book value of $6.40 per share and a cost of equity of $1.11 per share, the model uses a stable earnings figure of $33.94 per share, implying an excess return of $32.83 per share on a stable basis. An average return on equity that is a very large multiple of the cost of equity points to a business that, in this framework, can create substantial value from a relatively small equity base.
Stable book value is set at $14.98 per share, which keeps the focus on quality of reinvestment rather than aggressive balance sheet growth. Because the Excess Returns projections put Mastercard's estimated intrinsic value substantially above the current share price of $604.80, the market price implies a meaningful discount to what this model suggests those future surplus profits are worth. Because the US$1.8b BVNK deal channels more investment into stablecoin infrastructure, the acquisition sits right in the area this framework cares about, which is how new projects might earn above the cost of equity. Find out what Mastercard could be worth using our Excess Returns estimate.
The Mastercard Narrative: What Would Justify Today's Price?
Narratives pick up where the excess returns puzzle for Mastercard leaves off. They spell out which future paths for growth, margins and earnings would need to play out for Mastercard to be worth meaningfully more or less than the current price, and each one treats fair value as a specific thesis about the business that you can watch over time rather than a single frozen snapshot on the Community page.
Community views on Mastercard are split between those who see a quality compounder at a discount and those who think the price already reflects that story.
Bull case: 19% undervalued
"Mastercard isn''t standing still while stablecoins reshape payments, it''s building settlement infrastructure and tools for "agentic commerce" around them instead…"
Discover why this Narrative puts Mastercard at 19% undervalued.
Bear case: 16% overvalued
"Valuation premium: Mastercard trades around 30× forward earnings, above industry average (~22×), leaving little margin for error…"
Explore why this Narrative puts Mastercard at 16% overvalued.
One more Mastercard check that belongs beside the valuation work
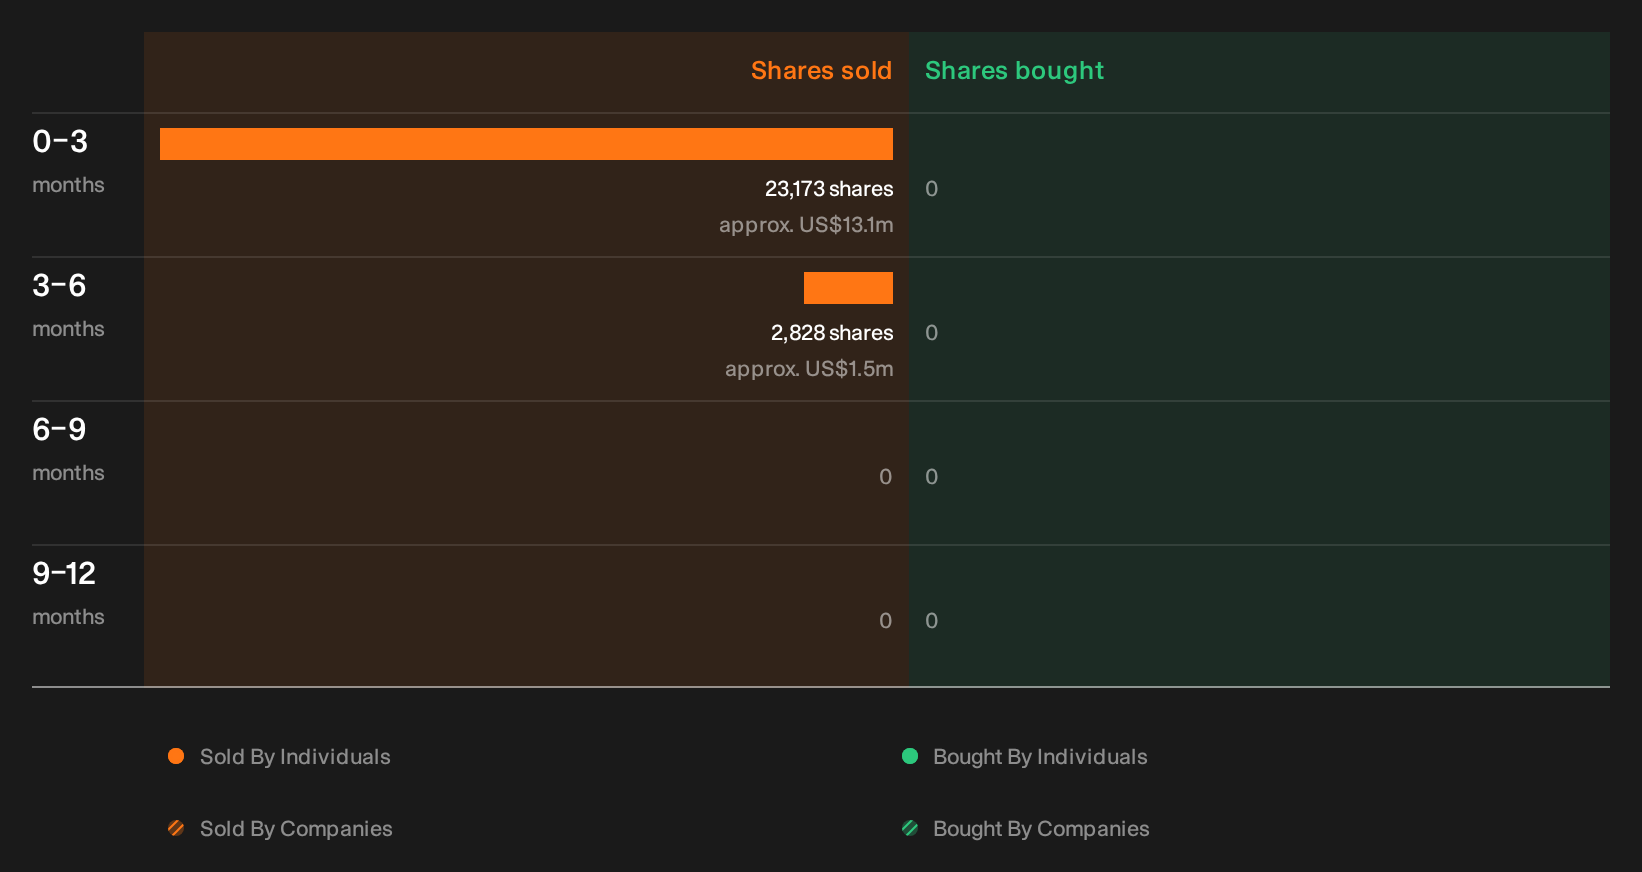
All the ratios and narratives sit alongside one quieter signal that our checks have recently picked up: trading activity from people inside Mastercard whose decisions you rarely see in the headlines. See the recent insider selling flagged for Mastercard.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com