


Global Ship Lease has delivered a powerful multi‑year share price run, and the question now is whether the current valuation can be explained by what the business actually earns.
- Over the past 3 years the stock has gained 210.2%, which puts real pressure on investors to check if those returns line up with the underlying profit power of the company.
- A newly announced US$1b syndicated loan facility tied to 15 future containership deliveries may support earnings visibility by spreading funding over time and anchoring the fleet expansion to contracted capital.
- The analysts covering Global Ship Lease have run their own numbers. See what analysts think Global Ship Lease's shares could be worth.
The issue now is whether Global Ship Lease's current share price is justified by its earnings profile after this run and the latest funding and orderbook moves.
If you are weighing whether Global Ship Lease's 210.2% three year gain and US$1b orderbook financing align with what it actually earns, it can help to benchmark that question against 32 high quality undervalued stocks.
Is Global Ship Lease Still Cheap on Earnings?
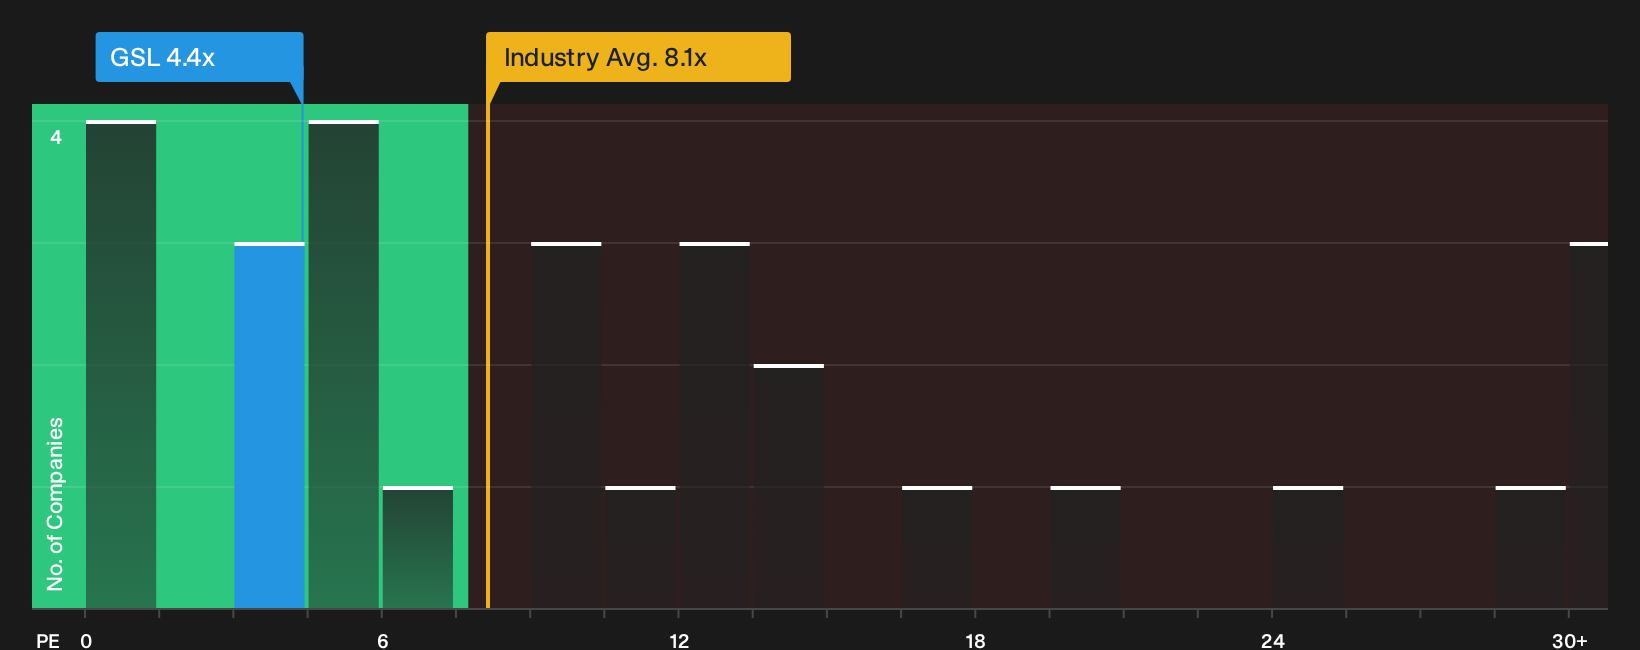
A P/E ratio is a useful shorthand for Global Ship Lease because earnings power and fleet deployment sit at the center of the story. On this metric, the stock trades at about 4.4x, which is well below both the wider shipping sector on roughly 8.1x and the broader peer group near 13.4x. That gap means the market is pricing each dollar of Global Ship Lease earnings at a sizable discount to many listed shipping businesses and to similar companies followed in the peer set.
Compared with the tailored fair P/E level implied by its own profile, Global Ship Lease also screens on the low side. The current multiple therefore points toward the shares being undervalued on this earnings yardstick. Because the newly arranged US$1b syndicated loan facility ties funding to future vessel deliveries, some investors may see that structure as support for earnings visibility, even as the P/E still trades below this more customised benchmark. Explore the numbers behind Global Ship Lease's P/E valuation.
The Global Ship Lease Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Global Ship Lease pick up exactly where this valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to play out for the shares to look meaningfully higher or lower than today. Where a single ratio or model outputs one clean number, these narratives unpack the future conditions that number relies on so you can watch how those assumptions hold up over time on the Community page.
One of the top community narratives on Global Ship Lease: 11% undervalued
"The company’s contracted revenue base has expanded to more than US$3.2b with multi year cover, while leverage has fallen sharply…"
Discover why this Narrative puts Global Ship Lease at 11% undervalued.
Global Ship Lease: the price is only one part of your decision
Valuation tells you what Global Ship Lease costs today, but the analyst view on where earnings and cash flows might sit a few years from now offers a separate reference point that can sharpen your judgment. Explore where analysts expect Global Ship Lease to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com