


nLIGHT (LASR) is back in focus after reporting record Q2 2026 revenue and securing a Joint Laser Weapon System contract with a ceiling above US$600 million. This combination is attracting close attention from investors.
After this contract announcement, nLIGHT’s 1-day share price return of 0.86% contrasts with a 90-day share price decline of 43.11%. At the same time, the 1-year total shareholder return of 25.59% and the very large 3-year total shareholder return suggest momentum has been built over a longer horizon.
Scan beyond nLIGHT and see how other defense focused laser and advanced manufacturing plays stack up in our hand picked 90 robotics and automation stocks.
Given nLIGHT’s sharp pullback and fresh contract win, the question now is whether most of the easy upside already played out earlier, or if the recent move still leaves meaningful value on the table as the numbers are priced in.
Most Popular Narrative: 53% Undervalued
At a last close of $38.58 against a most followed fair value estimate of $82.13, the current price for nLIGHT sits well below what that narrative assumes. This perspective places significant emphasis on long term defense and manufacturing demand.
The rapid growth and expanding pipeline in aerospace and defense, particularly around high-power laser solutions (e.g., HELSI-2 program, DE M-SHORAD, Golden Dome initiative, and increased directed energy orders internationally), positions nLIGHT to benefit from rising global defense spending and modernization, supporting strong multi-year revenue growth.
Increasing adoption of advanced laser technologies for automation, smart manufacturing, and additive manufacturing (especially in high-growth EV, clean energy, and microfabrication segments) underpins long-term demand for nLIGHT's differentiated products, providing a runway for sustained top-line expansion.
See why 16 investors see nLIGHT as 53% undervalued.
Result: Fair Value of $82.13 (UNDERVALUED)
Still, nLIGHT’s heavy tilt toward aerospace and defense contracts, along with weaker performance in the commercial segment, could both unsettle the bullish narrative if conditions tighten.
Find out about the key risks to this nLIGHT narrative.
Another View: Market Ratios Paint a Different Picture
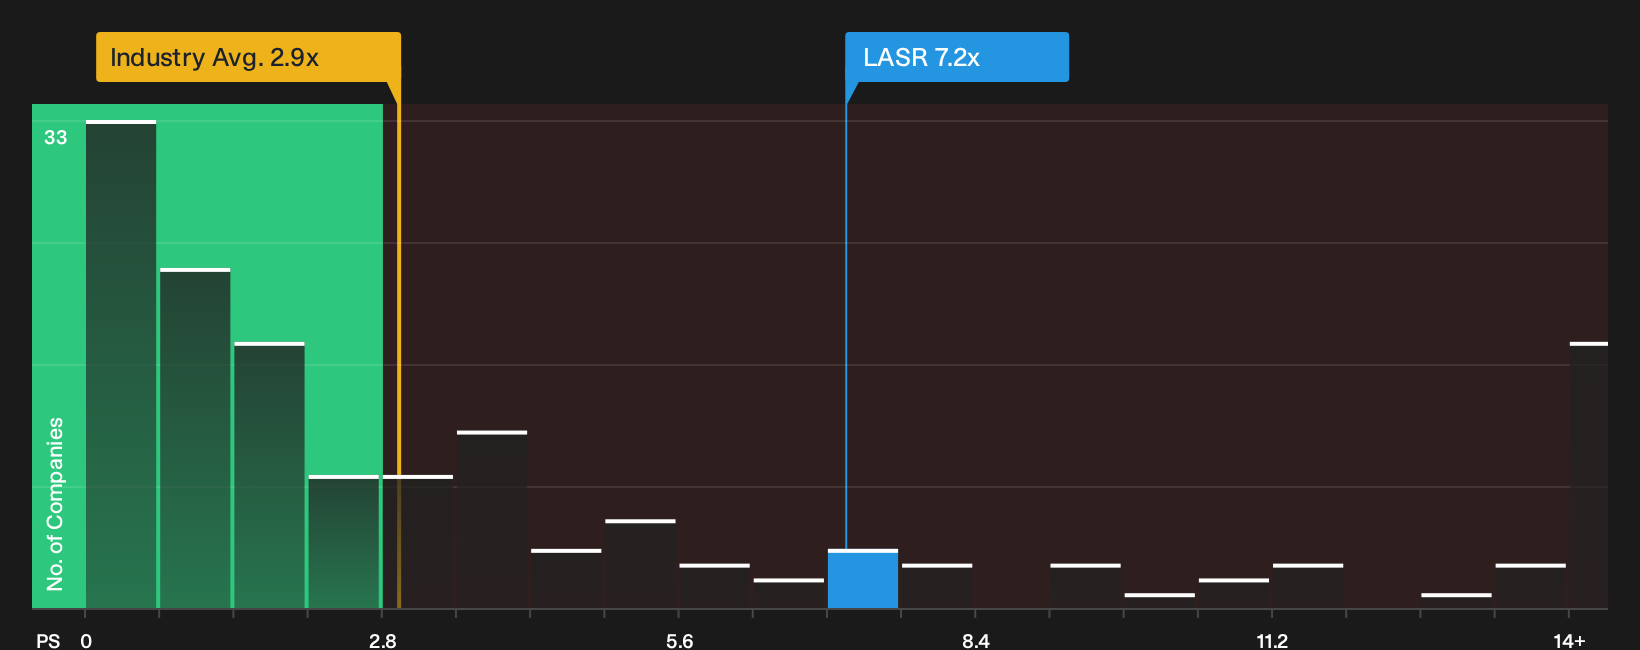
The analyst fair value for nLIGHT leans on long range earnings forecasts. Market pricing today tells a different story. The stock trades on a P/S of 7.2x versus a US Electronic industry average of 2.9x and a fair ratio of 1.8x, which points to rich expectations and limited room for disappointment. Does that premium match your own conviction on the story?
For a closer look at how this pricing compares to peers and how the fair ratio indicates where the market could drift over time, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages across nLIGHT’s valuation and contract pipeline can create plenty of noise. Move quickly, check the underlying data, and weigh the 1 key reward and 3 important warning signs.
Looking For More Ideas Beyond nLIGHT?
If nLIGHT has sharpened your interest, do not stop at a single ticker. Use the Simply Wall Street Screener to uncover ideas that match your risk, income, and value preferences before others move first.
- Target potential mispricing by scanning a curated 32 high quality undervalued stocks that combines quality fundamentals with pricing that may not fully reflect underlying business strength.
- Strengthen portfolio resilience by focusing on companies with robust finances through a list of solid balance sheet and fundamentals (25 results) that can help you avoid fragile balance sheets.
- Prioritise stability and downside protection by reviewing a 32 resilient stocks with low risk scores that filters for businesses with more measured risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com