


Safestore Holdings has seen its share price fall sharply in recent years, which naturally puts the focus on whether the current valuation can still be explained by its earnings power. With the stock now trading around £4.97, the question is how well that price lines up with the profits the business is generating today.
- The share price has declined 50.3% over the past 5 years, which puts real weight on the question of whether the earnings profile now justifies where the stock trades.
- Safestore’s storage model relies heavily on converting operating profit into steady cash flows, so the durability and quality of those earnings can matter as much as headline growth when considering what a fair multiple might be.
- There is a second opinion on Safestore Holdings worth weighing. See what analysts think Safestore Holdings's shares could be worth.
The stock’s next move may depend on whether the current price can be fully explained by Safestore’s earnings under the Fair Ratio lens.
If you are weighing whether Safestore Holdings at £4.97 truly reflects its earnings, it can help to compare that question across a wider field using a focused screen like 8 high quality undervalued stocks
Where Does Safestore Holdings Sit on Earnings?
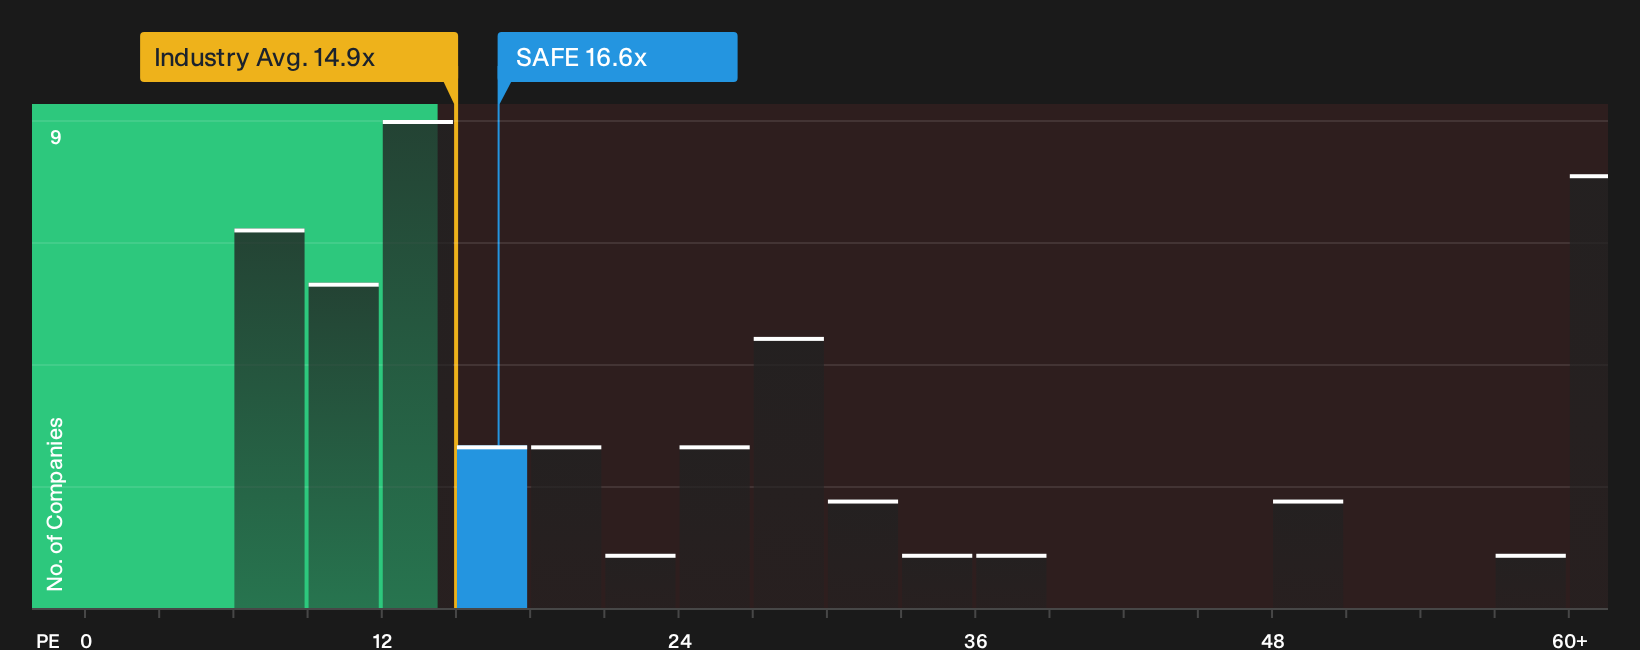
The P/E ratio suits Safestore Holdings because storage earnings tend to be relatively steady and investors often anchor on what they are paying for each pound of profit. At a P/E of 16.6x, buyers are paying a higher multiple than both the Specialized REITs industry average of 14.9x and the peer group on 10.7x, which points to a richer price tag for those earnings today.
The Fair Ratio model, which looks at the multiple you might expect given Safestore Holdings’ margins, size, sector and risk profile, lands slightly below where the shares trade now. That suggests the stock is priced a little above what this earnings framework would indicate, rather than screening clearly cheap, so investors would need to be comfortable that the quality and resilience of Safestore’s profits justify paying up on this measure before buying into the current valuation. Explore the numbers behind Safestore Holdings's P/E valuation.
The Safestore Holdings Narrative: What Would Justify Today's Price?
Narratives pick up where the Fair Ratio leaves off for Safestore Holdings by explaining which paths for growth, margins and earnings would need to occur for the current share price to appear high or low. Each scenario links a possible fair value to a clear story about Safestore Holdings' potential catalysts and key risks, so you can monitor over time which version of events comes closest to reality on Simply Wall St's Community page.
A clear, number-driven narrative on Safestore Holdings gives you a reference point for what assumptions on growth, margins and execution actually sit behind the current P/E, so you are not relying on vague sentiment when judging the price. It also creates a roadmap you can revisit as fresh results arrive, which helps you see quickly whether Safestore Holdings' real-world performance is tracking those expectations or challenging them.
Share your own Narrative for Safestore Holdings and set out the assumptions behind your valuation.
One more factor to weigh for Safestore Holdings before you act
Safestore Holdings may look straightforward on earnings, yet internal checks have flagged specific areas of concern that deserve your attention before you place too much weight on the current valuation. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com