


NICE has staged a sharp share price recovery over the past month, which raises a straightforward question for investors who follow the stock closely. Is the current price tag really in step with what the business earns today and what those profits may look like over time.
- The share price has declined 58.9% over the past 5 years, so the recent bounce puts a lot of weight on whether NICE's current earnings profile can carry the valuation from here.
- NICE's role in the new Personal Agent Protocol alongside Meta, Sierra and Genesys ties its contact center software more closely to personal AI agents, which can influence how investors think about the durability of its earnings power and the timing of any future profit growth.
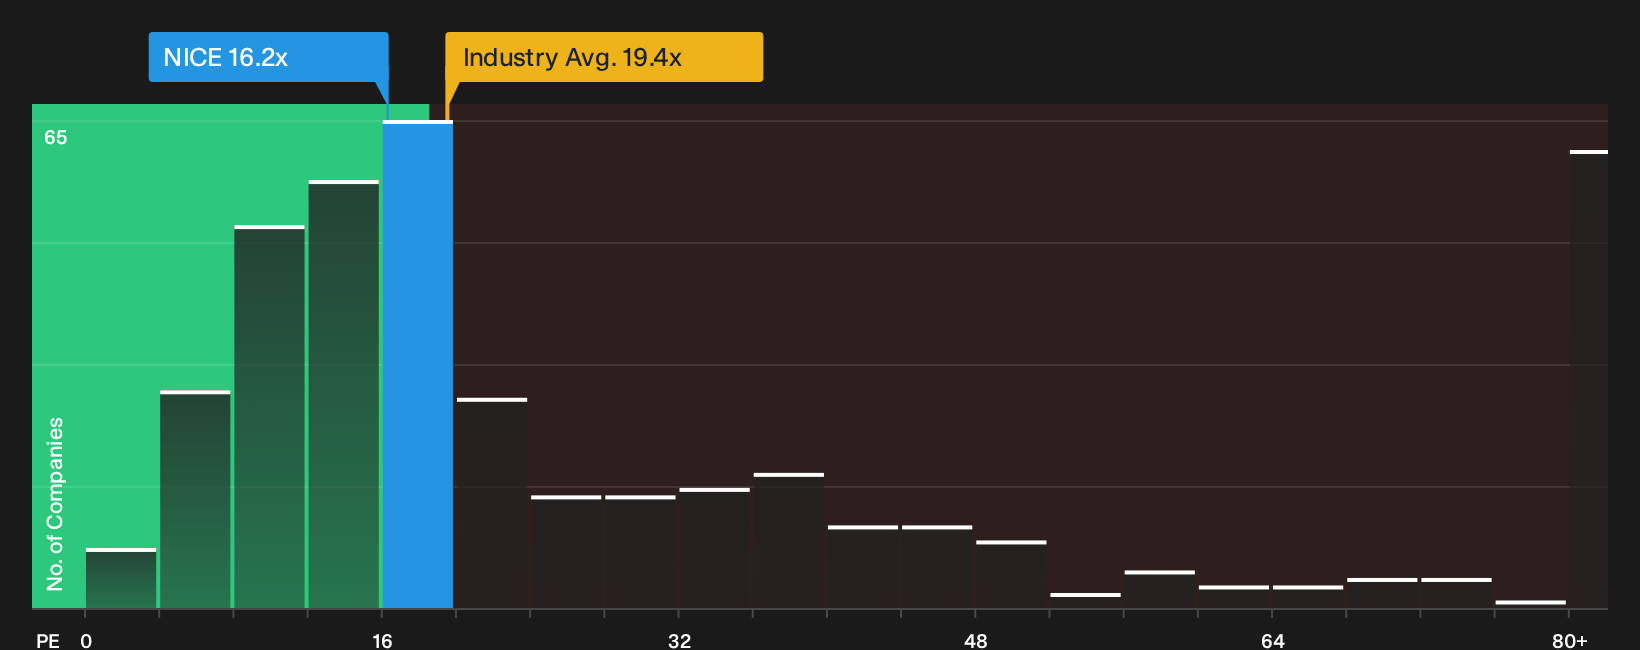
- Before you settle on a price for NICE, see what its peers cost. See how NICE's 16.2x P/E compares with its peers.
The issue now is whether NICE's recent share price level is adequately grounded in the earnings it generates relative to the industry average.
If you want a wider set of ideas built around similar earnings questions, a focused stock screen is a useful next step. You can start with 185 high quality undervalued stocks.
Does NICE Look Undervalued on Earnings?
The P/E ratio fits NICE because earnings remain the main anchor for how investors frame its value. On that yardstick, NICE trades on roughly 16.2x earnings, compared with about 22.5x for the wider Software sector and around 26.4x for its peer group. That gap means the shares change hands at a clear discount to both the industry average and closer peers on this earnings measure.
Because NICE is helping shape the new Personal Agent Protocol with Meta, Sierra and Genesys, many investors may have expected a richer valuation multiple already. Despite that AI related exposure lifting interest in the story, the P/E still prices NICE below typical software rivals on this metric. This leaves room for readers to judge whether the lower tag reflects caution on its earnings profile or an opportunity. Explore the numbers behind NICE's P/E valuation.
The NICE Narrative: What Would Justify Today's Price?
NICE Narratives on Simply Wall St link the valuation puzzle to the underlying expectations that would need to hold on growth, margins and earnings for the stock to be worth materially more or less than today’s price, and they sit within the Community page. Each scenario anchors a fair value estimate to a single, coherent storyline about NICE's potential catalysts and key risks so you can later see which version of events the actual results most closely resemble.
One of the top community narratives on NICE: 42% undervalued
"Expansion of strategic partnerships with ServiceNow, AWS, Salesforce, Snowflake, and RingCentral is expected to create durable go to market advantages…"
Discover why this Narrative puts NICE at 42% undervalued.
One last check for NICE before you move on
Price multiples only tell part of the story, because professional models project where this business could be a few years from now and give you a second lens to compare with today’s valuation. Explore where analysts expect NICE to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com