


Edison International has delivered a 22.7% share price gain over the past 5 years, yet with fresh headlines around wildfire risk and income-heavy dividends, the key question is whether its current valuation stacks up against the earnings that support it. For anyone considering the stock today, the focus is less on short-term price moves and more on what those profits truly justify.
- Over 5 years, Edison International has returned 22.7%, which places greater emphasis on whether the underlying earnings profile can support that level of performance.
- Recent coverage highlights a high dividend yield and ongoing wildfire-related obligations, which can both draw on the same pool of earnings that equity holders rely on.
- Your read on Edison International is one view; the desks covering it have another. See what analysts think Edison International's shares could be worth.
The stock's next move may depend on whether Edison International's current share price is fully supported by its earnings power today.
If you want a broader watchlist alongside Edison International while you assess income and risk trade-offs, a focused screen of 8 dividend fortresses is a useful next step.
Is Edison International Still Cheap on Earnings?
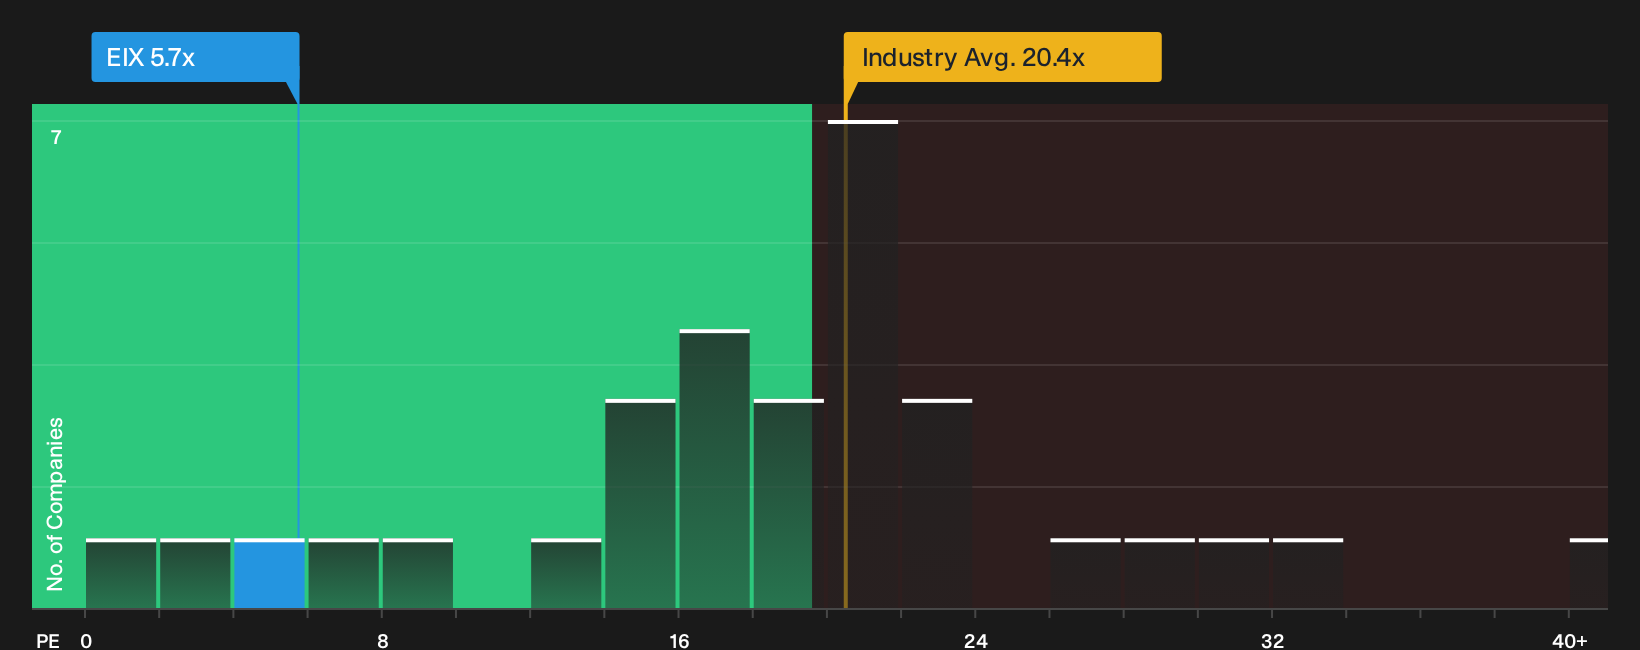
The P/E ratio is a useful anchor for Edison International because earnings remain the main pool that has to cover both dividends and wildfire related obligations. On this measure, the stock trades on a P/E of 5.7x, compared with an Electric Utilities sector average of about 20.4x and a peer group level closer to 21.7x. The current multiple also sits below a tailored fair multiple, which reflects factors like Edison International’s margins, scale and risk profile.
Because the market is pricing in wildfire liabilities and regulatory risk despite recent confirmation of core earnings guidance through 2030, Edison International’s low P/E still screens as undervalued relative to what that framework implies. For anyone weighing the income on offer against those risks, the gap between today’s P/E and the level suggested by the company’s fundamentals is the key figure to scrutinize next. Explore the numbers behind Edison International's P/E valuation.
The Edison International Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Edison International's valuation puzzle leaves off by spelling out which paths for future growth, profitability and earnings would need to hold for the stock to be worth materially more or less than today's price, and each one treats fair value as a thesis about the business that you can revisit over time, rather than a single static snapshot. These sit on Simply Wall St's Community page for investors who want to track how that story develops.
Bulls and bears on Edison International are working from the same wildfire headlines but draw very different conclusions about what the current price already reflects.
Bull case: 16% undervalued
"Policy driven increases in electrification, together with climate goals, continue to require large scale grid upgrades in Southern California that Edison International plans to address through a US$38b to US$41b capital program from 2026 to 2030…"
Discover why this Narrative puts Edison International at 16% undervalued.
Bear case: 11% overvalued
"Although Edison International is using the Wildfire Recovery Compensation Program to settle Eaton Fire claims and has already made thousands of payments totaling close to US$450 million, the strong ongoing participation with more than US$775 million in offers indicates that ultimate cash costs could run higher than many models assume…"
Explore why this Narrative puts Edison International at 11% overvalued.
One more Edison International check that belongs beside the valuation work
Price multiples and wildfire obligations tell only part of the story for Edison International, because analyst projections for profits a few years from now give you a separate benchmark to compare with today's earnings based view. Explore where analysts expect Edison International to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com