


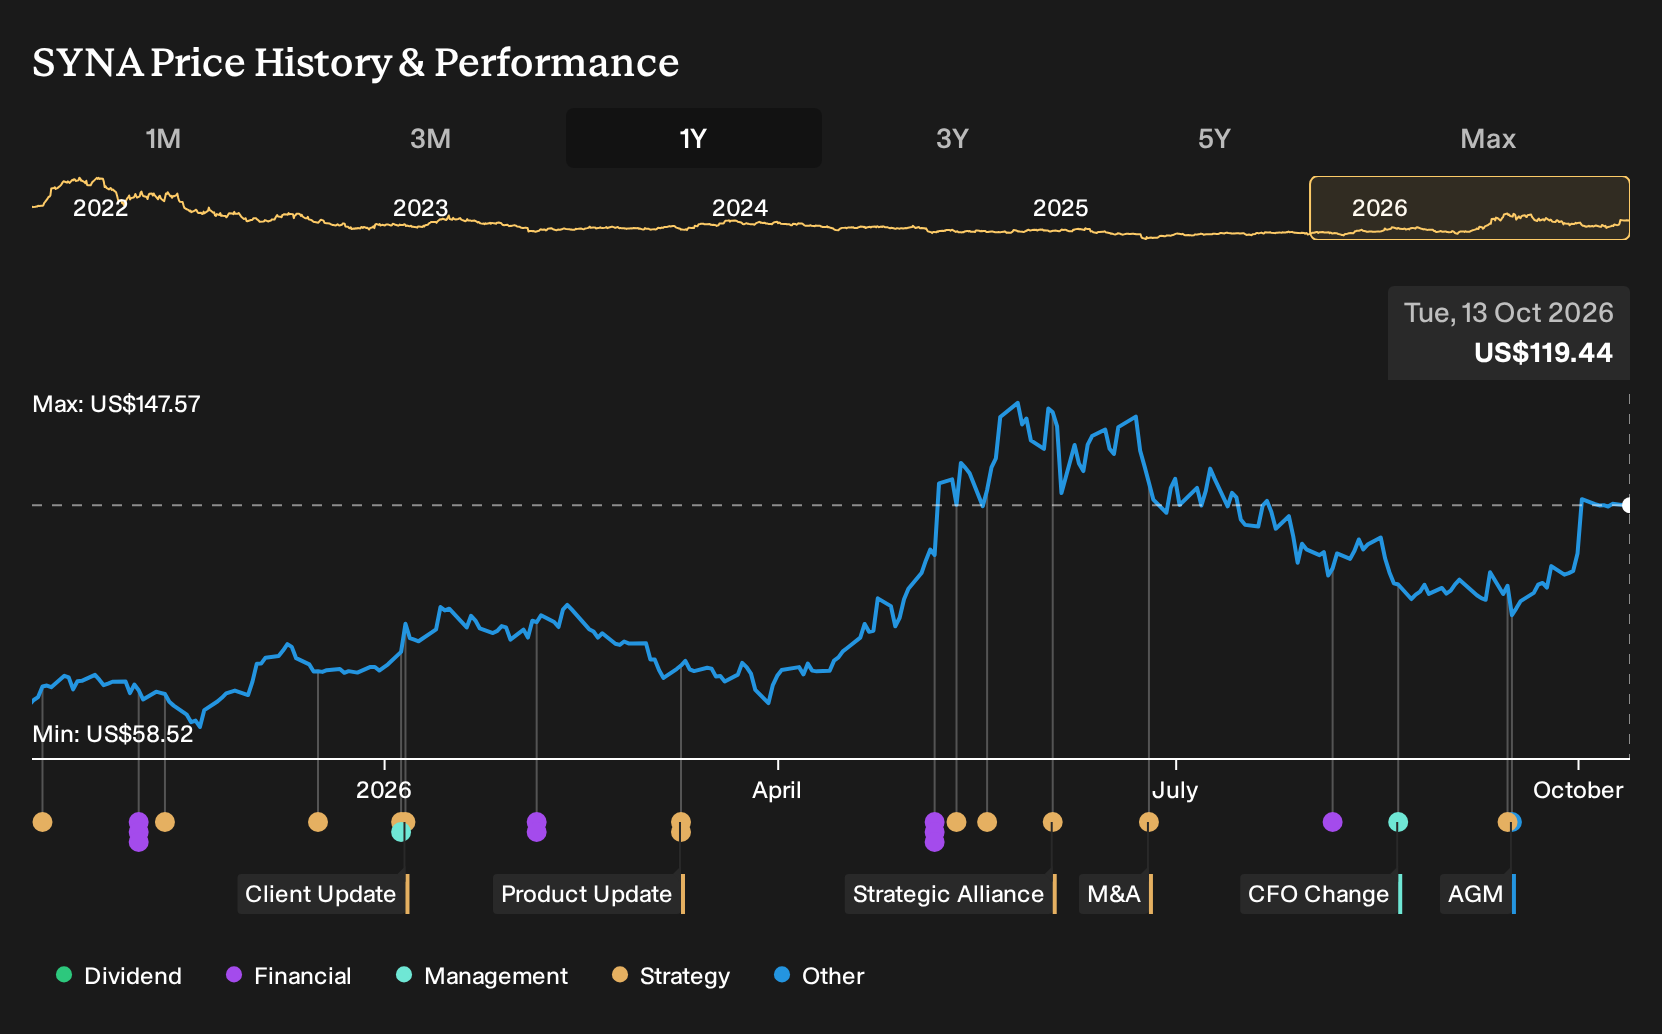
- Flip Electronics announced an authorized distribution partnership with Synaptics to supply embedded compute, wireless connectivity, and sensing solutions for aged, end-of-life, and obsolete parts serving automotive and IoT customers.
- The focus on obsolescence management highlights how Synaptics is trying to keep legacy devices supported, while Core IoT and Edge AI remain longer term priorities.
- We will look at how Synaptics' investment narrative could be influenced by this Flip Electronics obsolescence focused distribution partnership.
Scan beyond Synaptics and this obsolescence deal by reviewing a curated set of resilient hardware and connectivity players in our list of solid balance sheet and fundamentals (25 results).
Synaptics Investment Narrative Recap
To own Synaptics, you need to buy into a shift toward Core IoT, Edge AI and higher value bundled solutions, while the firm is still unprofitable and reported a net loss of US$490.8 million on US$1.2b of revenue. The Flip Electronics deal fits that story only at the margin, giving aging products a longer commercial tail but not changing the core thesis.
The key near term swing factor remains execution in scaling IoT and Edge AI design wins into meaningful revenue, with analysts expecting earnings to improve from very weak levels. The biggest risk is that operating cash flow and channel reach do not keep up with investment and debt obligations, which could squeeze flexibility if growth underwhelms.
The new Flip Electronics partnership is tightly linked to one major operational challenge. Management has talked about pruning and refocusing the product portfolio, and this agreement effectively creates a specialist outlet for aged, end of life and obsolete Synaptics parts in automotive and IoT markets.
This type of obsolescence channel can support Core IoT and Edge AI as catalysts in two ways. It can keep long tail customers supplied while internal resources move toward higher ROI segments, and it may soften execution risk around channel scale by letting a focused distributor handle complex lifecycle and supply issues for legacy devices.
Synaptics' current revenue path is framed around analyst expectations that annual sales will grow by 9.4% over the next few years, reaching US$1.6b of revenue and US$21.2 million of earnings by 2029. This implies a turn from a reported net loss of US$490.8 million today to positive earnings in 2029, an earnings swing of roughly US$512 million over that period.
Uncover why Synaptics' fair value points to a 9% potential upside to its current price, which could narrow quickly if sentiment shifts.
Exploring Other Perspectives
One optimistic twist on this Flip Electronics deal centers on Synaptics as a physical AI and robotics supplier. The most bullish analysts were already penciling in revenue of about US$1.7b and earnings near US$190.4 million by 2029, far above consensus. Those projections came before this announcement, so views may shift and differ widely.
Explore 4 other Synaptics fair value estimates, including one that suggests up to 41% potential upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Synaptics research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Synaptics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Synaptics' overall financial health at a glance.
Looking for more Synaptics style investment ideas?
If the Synaptics story has you thinking about where else solid fundamentals or different types of opportunities might be hiding, it can help to widen the lens and run the same kind of checks across a broader watchlist using the Simply Wall St screener.
- For investors who want potential upside without ignoring balance sheet strength, start with a curated set of 20 high quality undiscovered gems that already show solid fundamentals.
- If preserving capital is a priority and you want fewer unpleasant surprises, focus your research on 32 resilient stocks with low risk scores that score well on financial stability and business risk.
- Income focused portfolios can lean on dependable cash returns, so it may be worth scanning through 8 dividend fortresses that pair higher yields with durable business models.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com