


Adobe has seen a long slide in its share price, and that slump now puts a spotlight on a simple question for investors who care about fundamentals. Is the current US$236.28 price tag adequately backed by the earnings the software group is generating today and is expected to produce over time?
- Over the past 5 years, Adobe shares have fallen 62.9%, which puts the focus squarely on whether the market has reset expectations on its earnings too far or not far enough.
- Fresh scrutiny of the business, from federal investigations into its use of foreign workers to questions about growth in its core software lines and AI products, can influence how durable investors think Adobe's profit engine will be and how much they are willing to pay for each dollar of earnings.
- Your read on Adobe is one view; the desks covering it have another. See what analysts think Adobe's shares could be worth.
The issue now is whether Adobe's current market valuation is meaningfully supported by its earnings power or whether the price has drifted away from what its profit profile can justify.
If you are reassessing Adobe in light of earnings pressure and AI exposure, it can be helpful to compare it with other software names facing similar dynamics by scanning 38 AI small caps.
Is Adobe Still Cheap on Earnings?
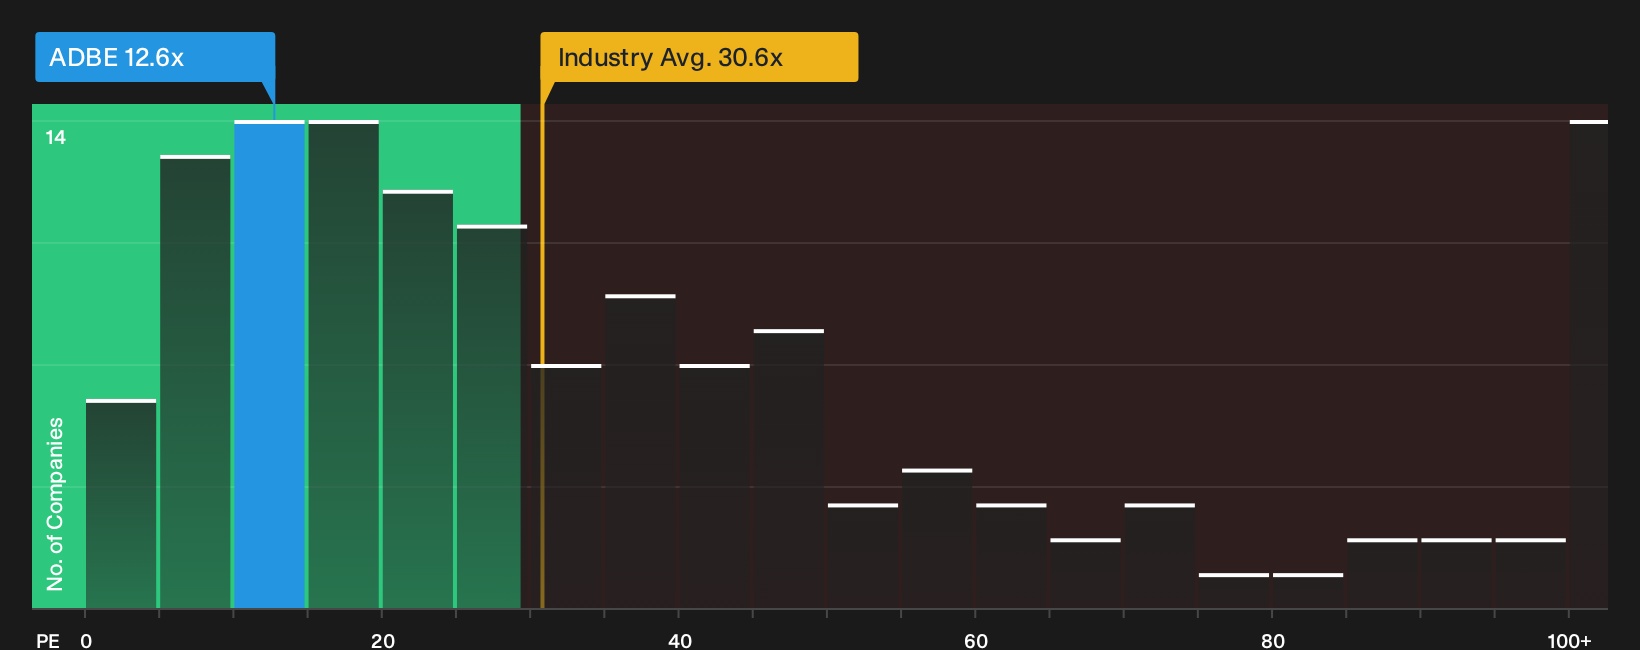
The P/E ratio fits Adobe because investors tend to anchor software valuations on the earnings power of recurring subscriptions. At a P/E of about 12.6x, Adobe trades far below the broader Software industry average of roughly 30.6x and well under a peer group closer to 50.4x. That is a steep gap for a large, established platform with global reach.
Fresh concerns about Adobe's growth profile and the federal investigation into its use of foreign workers help explain why the multiple has compressed, yet the current figure still sits below what a tailored fair multiple model suggests for this business. The fair benchmark, which blends Adobe's margins, expected earnings trajectory, sector risk and size, points to a higher P/E than where the stock trades today, implying the market price is undervalued on this yardstick. For an investor weighing AI product adoption, subscription durability and execution through the talent restrictions, that disconnect is the key question to test. Explore the numbers behind Adobe's P/E valuation.
The Adobe Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Adobe pick up where the P/E puzzle leaves off and spell out the concrete earnings, growth and margin paths that would need to play out for Adobe's share price to be worth materially more or materially less than it is today on the Community page. Instead of a single ratio or model output, Narratives set out the future that figure rests on so you can watch over time whether those assumptions still hold.
Community views on Adobe split sharply between those who see a reset opportunity and those who see a classic value trap in progress.
Bull case: 49% undervalued
"The current valuation of Adobe reflects a market that is pricing in a structural obsolescence that is not supported by the company’s underlying financial performance or its aggressive technological pivots..."
Discover why this Narrative puts Adobe at 49% undervalued.
Bear case: 45% overvalued
"Adobe's investment in Firefly has caused great harm in the user community, it cannibalizes the user base, it devalues the work of original content creators and it's driving the independent users to products like Canva and DaVinci..."
Explore why this Narrative puts Adobe at 45% overvalued.
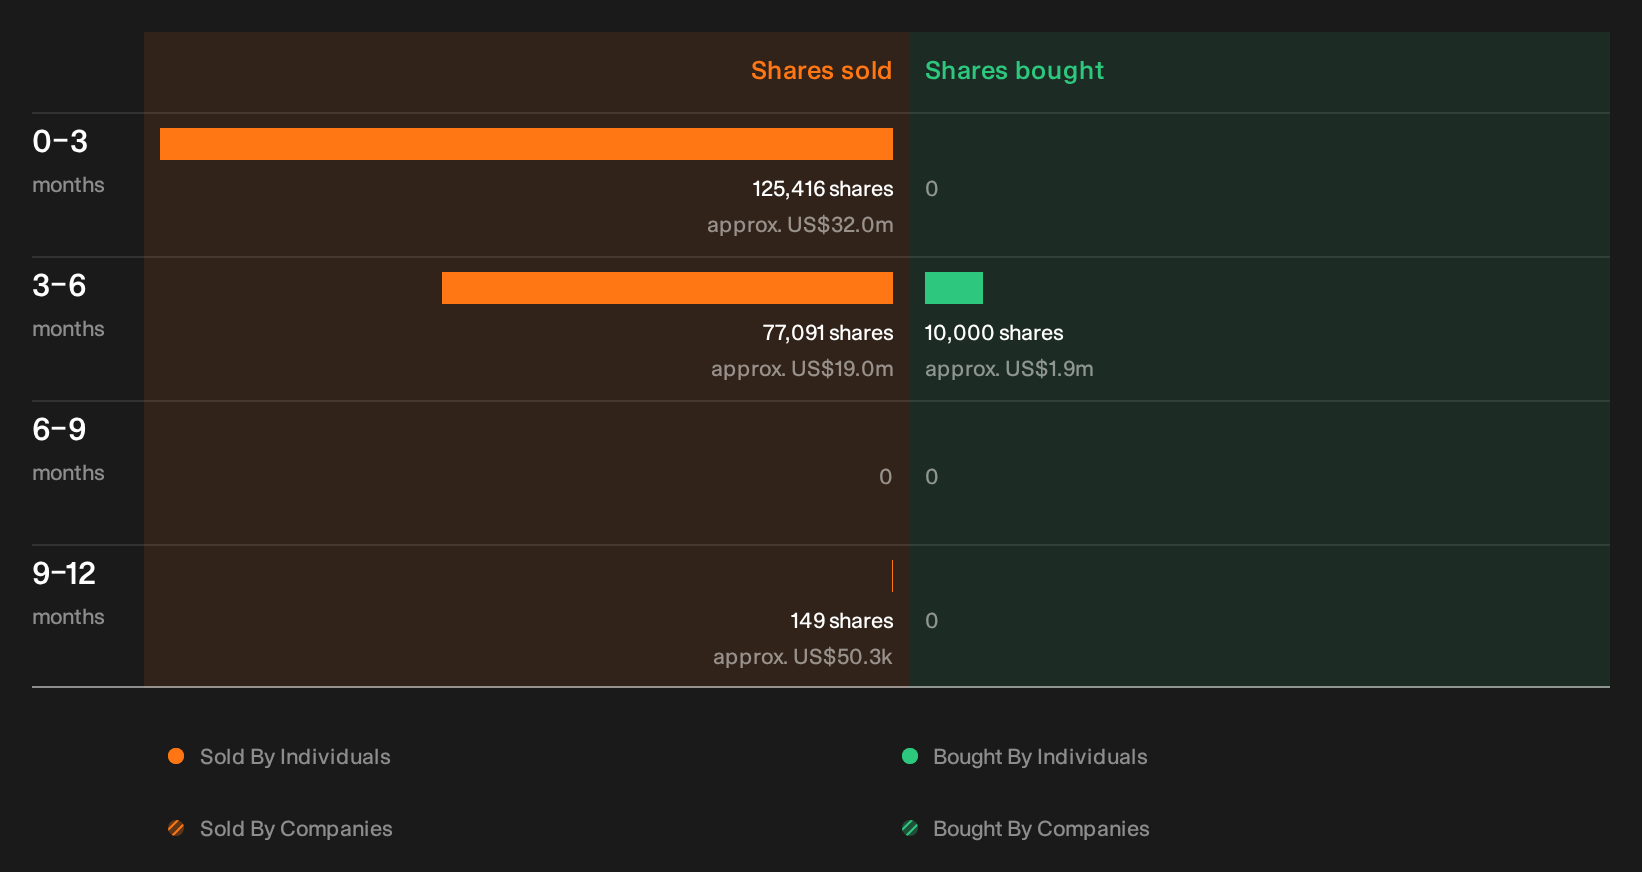
Adobe's insider moves could matter more than the headline price
Price and earnings only tell part of the Adobe story, because recent trading by people inside the business can offer a very different signal for you to unpack. See the recent insider selling flagged for Adobe.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com