


JetBlue Airways has seen its share price slide in recent years, and that kind of drawdown naturally raises a blunt question for investors who still follow the stock. Is the current market value really supported by the airline's ability to generate sales over time, or has sentiment moved further than the underlying business?
- Over the past 5 years, JetBlue Airways stock has fallen 77.5%, which puts the focus firmly on whether the revenue base justifies where the shares trade today.
- The business model still leans heavily on filling seats efficiently and managing costs against ticket and ancillary income, so any shift in route economics or unit revenue can strongly influence how much investors are prepared to pay for each dollar of sales.
- Your read on JetBlue Airways is one view; the desks covering it have another. See what analysts think JetBlue Airways's shares could be worth.
The issue now is whether JetBlue Airways' current share price can be explained by the scale and quality of its sales relative to what investors typically accept as a fair ratio.
If you are weighing whether JetBlue Airways' share price fairly reflects its sales, you might want to compare that question across 32 high quality undervalued stocks
Is JetBlue Airways a Bargain on Sales?
Price to sales fits JetBlue Airways because the airline is still heavily defined by ticket and ancillary revenue rather than consistent earnings.
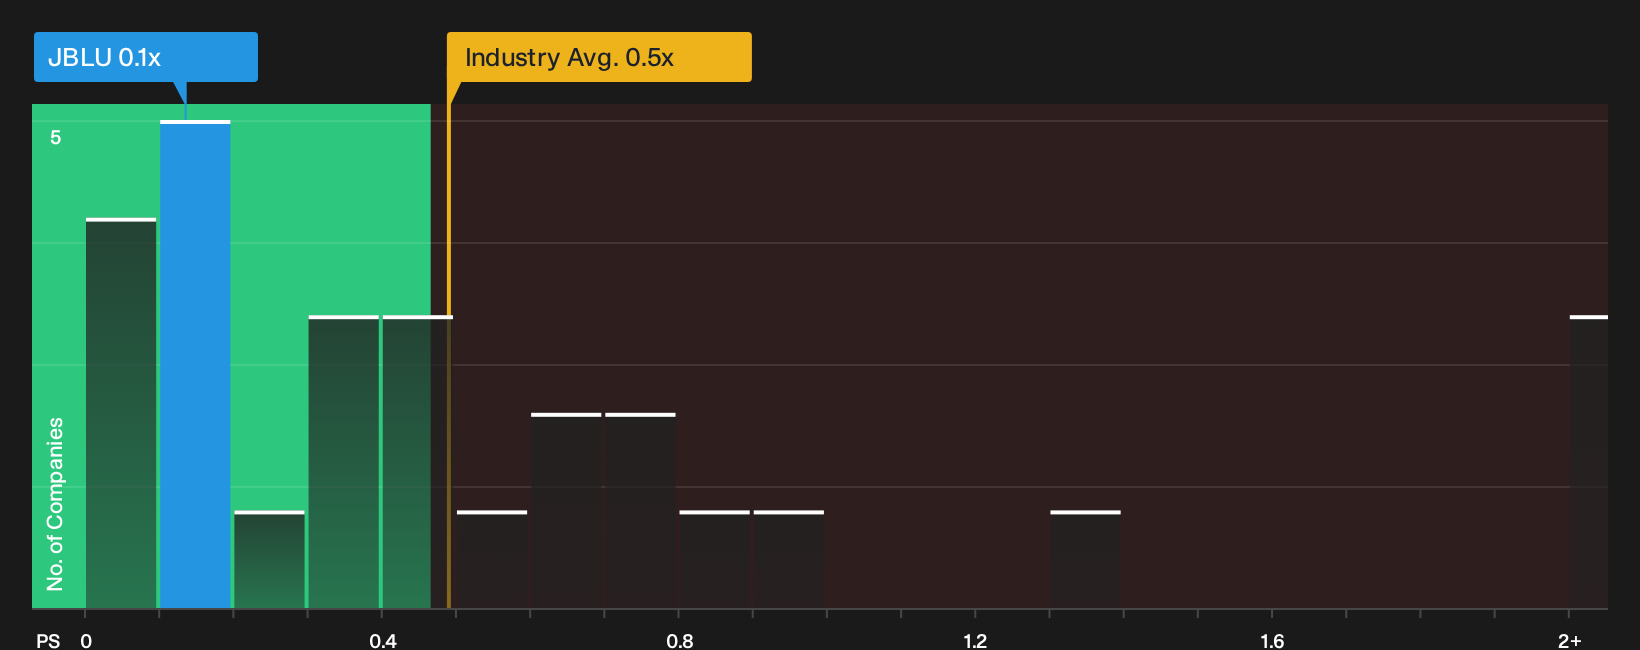
On this measure, JetBlue trades on a P/S of 0.1x, while the wider airlines industry sits closer to 0.5x and the peer group average is around 0.4x. The tailored fair multiple for the stock is higher than where the shares change hands, which points to JetBlue being undervalued on this sales based yardstick once its size, margins and risk profile are taken into account. For an investor, that kind of gap suggests the market is placing a low value on each dollar of JetBlue Airways revenue relative to what is implied by these fundamentals. Explore the numbers behind JetBlue Airways's P/S valuation.
The JetBlue Airways Narrative: What Would Justify Today's Price?
Narratives for JetBlue Airways pick up where the P/S puzzle leaves off, by spelling out the specific paths for growth, profitability and earnings that would need to play out for the stock to be worth much more or much less than it is today. Instead of a single ratio or valuation output, they lay out the future business conditions that number assumes, so you can watch how JetBlue Airways' actual performance lines up with that story on Simply Wall St's Community page.
Community views on JetBlue Airways split between a discounted recovery story and a cautious stance that still sees more risk in the price.
Bull case: 27% undervalued
"Major operational improvements, including leading on-time performance, network optimization, and elevated customer satisfaction, are expected to support better load factors and boost both revenue and net earnings..."
Discover why this Narrative puts JetBlue Airways at 27% undervalued.
Bear case: 12% overvalued
"Persistent challenges in controlling high fixed operating costs, including wage inflation, maintenance, and the risk of further fuel cost volatility, will restrict JetBlue's ability to expand net margins..."
Explore why this Narrative puts JetBlue Airways at 12% overvalued.
JetBlue Airways: why the checklist still matters beyond the share price
Price tags and sales multiples only tell part of JetBlue Airways' story, because the broader risk checks are flagging issues that deserve attention before any decision. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com