


United Fire Group has seen its stock price climb sharply in recent years, which puts fresh attention on whether that move lines up with the insurer's earnings power. With a long run already behind it, the question now is how much of that strength is already reflected in today’s valuation.
- Over the past 5 years, United Fire Group has returned 184.3%, which puts a lot of weight on whether its profits can support a materially higher share price than in the past.
- The business still turns on a traditional insurance model where underwriting results and investment income drive profit. Any shift in claim trends, pricing discipline or portfolio yields can feed directly into the earnings that underpin the current market value.
- The analysts covering United Fire Group have run their own numbers. See what analysts think United Fire Group's shares could be worth.
The stock's next move may depend on whether United Fire Group's current earnings are strong and durable enough to make today's price look reasonable.
If you are weighing whether United Fire Group's recent run is justified by its earnings, it can help to compare that story with other 32 high quality undervalued stocks.
Does United Fire Group Look Pricey on Earnings?
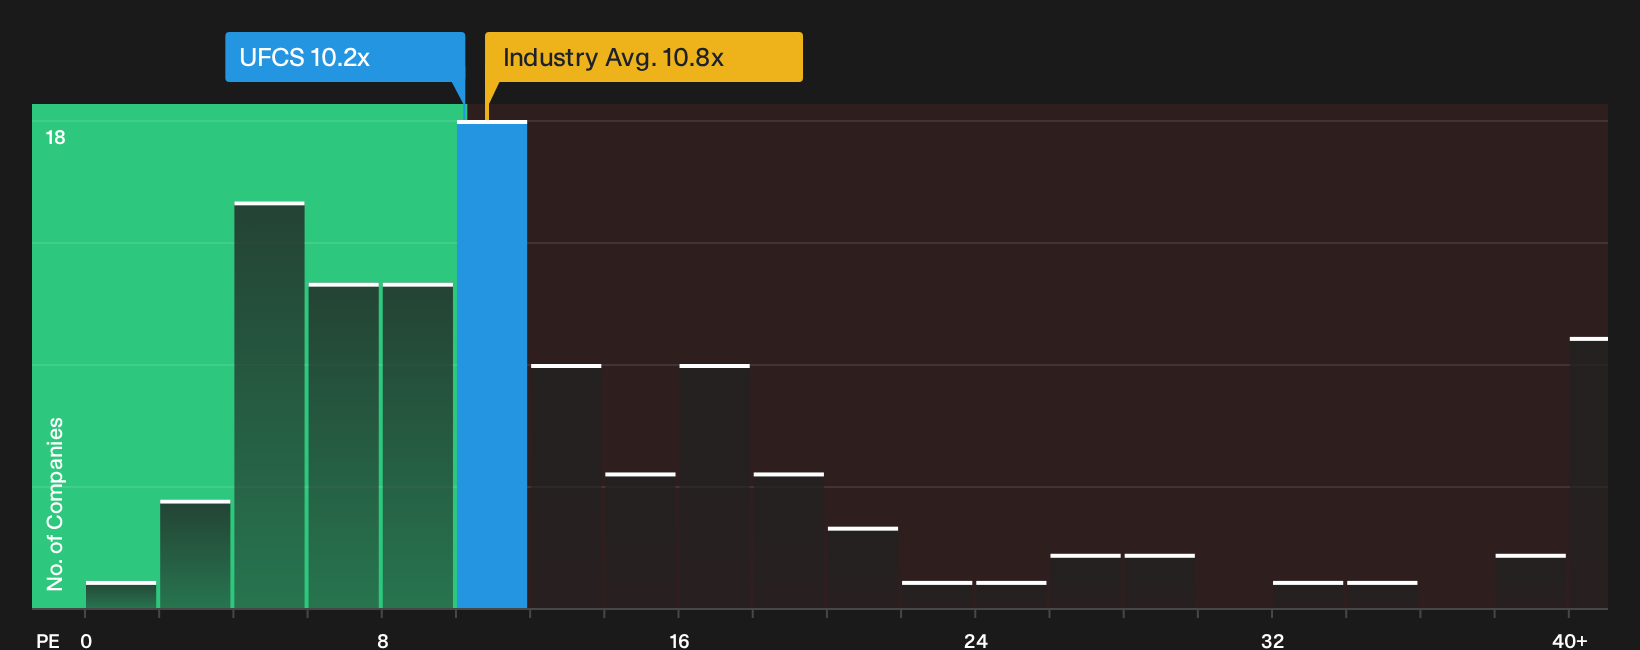
The P/E multiple fits United Fire Group because earnings are a direct output of its underwriting and investing decisions. On this measure, United Fire Group trades on a P/E of 10.2x, which is a small discount to the broader Insurance sector on 10.8x and a steeper gap to the peer group average around 22.4x. For an insurer with a traditional model, that places a lot of weight on how reliable you think those reported profits are and how cyclical the underlying book might be.
The valuation framework that blends United Fire Group's recent profitability, capital base, size and risk profile suggests a lower P/E would better match its fundamentals. As a result, the current 10.2x screens as overvalued against that more tailored yardstick rather than the raw sector averages. For anyone assessing the stock, the key question is whether the quality and consistency of future earnings justify paying a premium to that model implied level. Explore the numbers behind United Fire Group's P/E valuation.
The United Fire Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle for United Fire Group leaves off by spelling out which combinations of future growth, profitability and earnings power would need to occur for the shares to be worth materially more or less than today’s level on the numbers discussed above. Each narrative frames United Fire Group's implied worth as a thesis about how the business might progress over time that you can track as fresh results come through, and they sit on Simply Wall St's Community page.
One of the top community narratives on United Fire Group: roughly fairly valued
"UFG's ongoing investments in underwriting technology and analytics, coupled with improved risk selection and pricing measures, are generating lower loss ratios and underwriting profits..."
Discover why this Narrative puts United Fire Group at roughly fairly valued.
One more side to United Fire Group that deserves a closer look
Valuation only tells part of the story for United Fire Group, because recent checks have highlighted specific business risks that could change how you view the whole investment case. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com