


Liberty Energy has delivered a 58.3% gain over the past year, yet its recent pullback has many investors asking whether the current share price still lines up with what the business earns. After a move like that, the real question is how much of the company’s earnings power is already reflected in the stock.
- The 58.3% return over the last 12 months puts real pressure on the valuation question because it changes what investors are implicitly paying for each dollar of earnings.
- A business like Liberty Energy, which depends heavily on how efficiently it can convert drilling and completion work into consistent profits, can see its earnings based valuation shift quickly if margins or capital intensity move even a little.
- Your read on Liberty Energy is one view; the desks covering it have another. See what analysts think Liberty Energy's shares could be worth.
The issue now is whether Liberty Energy's current price is adequately explained by its earnings profile or if expectations have moved ahead of the underlying business performance.
If you want to test the same earnings question that Liberty Energy now faces across a broader set of opportunities, take a look at 32 high quality undervalued stocks.
Does Liberty Energy Look Pricey on Earnings?
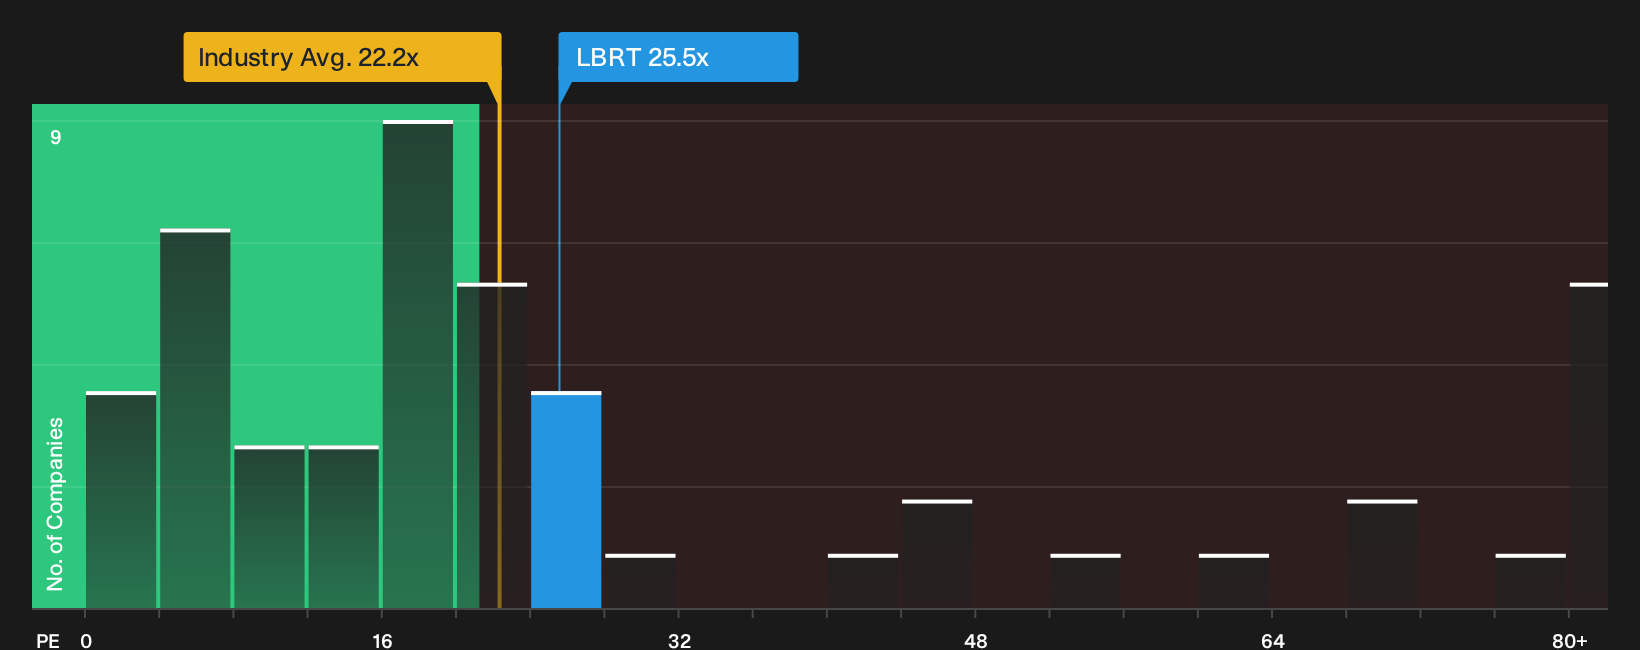
P/E fits Liberty Energy because profits are a central yardstick for an equipment and services business. The stock trades on about 25.5x earnings, compared with an Energy Services sector average of roughly 22.2x and a wider peer group closer to 72.1x. That leaves Liberty Energy priced above the broader industry, yet well below some comparable operators that carry much richer earnings tags.
The fair-value model, which sets an expected P/E based on Liberty Energy's own growth profile, profitability, size and risk, points to a lower multiple than the current one. That gap suggests the shares screen as overvalued on this earnings measure, and it raises the bar for how much cash flow the business needs to sustain over time to fully back up today’s price. For investors weighing an entry point, the key question is whether Liberty Energy’s earnings quality and resilience justify paying this premium over the model’s implied level. Explore the numbers behind Liberty Energy's P/E valuation.
The Liberty Energy Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Liberty Energy's valuation puzzle leaves off and explain what kind of future growth, profitability and earnings profile would need to occur for the current share price to appear either stretched or conservative. Each scenario links Liberty Energy's potential fair value to a clear set of possible catalysts and risks, so you can track over time which storyline is most consistent with how the business is actually evolving on the Community page.
One of the top community narratives on Liberty Energy: 33% undervalued
"The main thing that has to go right is Liberty Energy successfully executing its capital intensive pivot toward a 3 GW distributed power platform..."
Discover why this Narrative puts Liberty Energy at 33% undervalued.
One more angle on Liberty Energy that could change the story
Price tags and profit multiples only tell part of the story for Liberty Energy, because the people setting priorities, incentives and trade offs can push outcomes in very different directions. See who runs Liberty Energy and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com