


- Universal Vapor Jet Corporation, a subsidiary of Universal Display, has launched NovaJet, a commercial Universal Vapor Jet Printing system that deposits functional materials onto substrates such as silicon, glass and polymers for semiconductor, electronics and advanced manufacturing uses.
- The NovaJet platform brings multiple thin film process stages onto a single dry, solvent free tool. This integration can reshape how Universal Display participates in materials development from early research through manufacturing scale up across sectors such as semiconductors, solar and biomedical devices.
- We will look at how Universal Display's investment narrative is affected by NovaJet's solvent free, maskless deposition platform for advanced manufacturing.
Universal Display Investment Narrative Recap
For Universal Display, the central view is that OLED materials and related technologies could extend further into IT and automotive if the core handset exposure stabilizes. The launch of NovaJet adds a second leg to that story in advanced manufacturing. However, in the near term, the main swing factor still appears tied to material volumes and license activity rather than this new tool.
The most important short term catalyst is how quickly customer ordering patterns for OLED materials settle following the revenue guidance cut and handset softness. The biggest risk is that erratic purchasing and weaker smartphones continue. NovaJet appears incremental for now and does not clearly change those nearer term pressures.
The NovaJet commercial launch is the key announcement in this context. It moves Universal Display's vapor jet printing platform from concept work into a product that can be ordered and deployed at customer sites. The initial focus is on semiconductor, electronics and other advanced manufacturing users that require precise, solvent free material deposition.
On catalysts, NovaJet sits alongside ongoing Gen 8.6 OLED fab investments, early OLED adoption in IT and automotive, and work on phosphorescent blue emitters. Taken together, these efforts broaden the range of applications where Universal Display can earn material and licensing income, while still leaving the business exposed to the risk that end market demand or device adoption may remain slower than anticipated.
Universal Display's current analyst narrative points to revenues of US$807.3 million and earnings of US$269.5 million by 2029. This setup assumes revenue growth of 10.0% a year and an earnings increase of about US$73.9 million from US$195.6 million.
Uncover how Universal Display's fair value indicates a 52% potential upside to its current price that could narrow quickly.
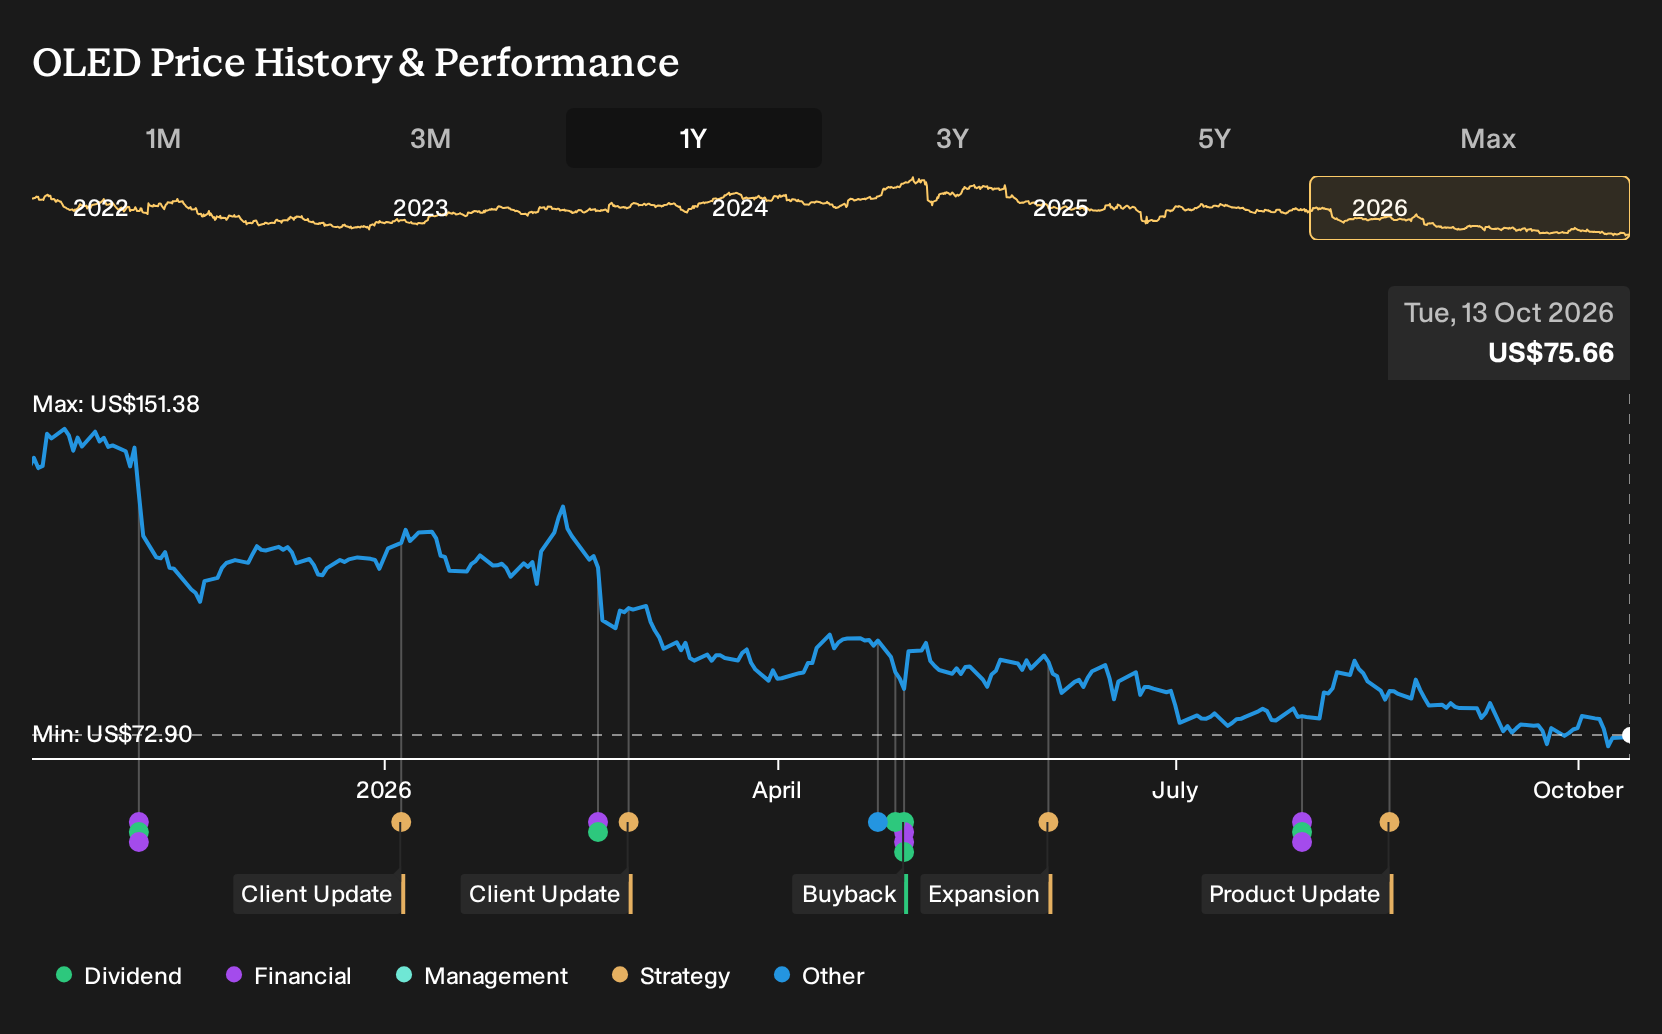
Exploring Other Perspectives
One alternate view puts more weight on execution risk around Universal Display's phosphorescent blue and AI driven materials work than on NovaJet. Those more cautious analysts still model revenue of about US$811.3 million and earnings near US$295.2 million by 2029, yet apply a much lower 13.8x P/E. Their forecasts all pre date this NovaJet launch, so it may be useful to monitor how opinions and models change as more information becomes available and to compare several perspectives before considering how this news fits your own thesis.
Explore 4 other Universal Display fair value estimates, including one that suggests as much as 49% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Universal Display research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Universal Display. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Universal Display's overall financial health at a glance.
Looking for more Universal Display style investment ideas?
If the NovaJet story has you thinking more broadly about where to put fresh capital to work, it can help to widen the lens beyond Universal Display and scan for other businesses with characteristics that fit your approach.
- For investors who want quality at a sensible entry point, start with a curated pool of 32 high quality undervalued stocks that marry strong fundamentals with more modest pricing.
- If capital preservation matters just as much as upside, focus on companies in our 32 resilient stocks with low risk scores that pair sturdier balance sheets with more predictable profiles.
- When you are hunting for future leaders that are not yet crowded trades, cast a wider net across 20 high quality undiscovered gems that combine solid metrics with lower headline attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com