


- Nestlé has expanded its global marketing reach through a multi year NBA partnership covering 21 markets and announced an additional US$1b investment in Mexico operations through 2030, focused on modernizing production and improving efficiency.
- The NBA alliance makes Milo, Nescau and Nesquik Official Partners across key basketball markets, while the Mexico outlay signals continued capital commitment to manufacturing scale, technology and more sustainable processes.
- We will look at how Nestlé's investment narrative is shaped by the expanded NBA partnership and the renewed US$1b Mexico commitment.
Scan beyond Nestlé and explore this NBA plus Mexico investment story by lining up peers that match its scale and balance sheet focus through our curated list of solid balance sheet and fundamentals (204 results).
Nestlé Investment Narrative Recap
Nestlé appeals to shareholders who want a large, diversified food business that leans into branded beverages, pet care and nutrition, supported by global marketing platforms. To stay comfortable, you need to believe management can translate this reach into steady cash generation despite slower forecast revenue growth and category headwinds in areas like prepared dishes.
The NBA alliance and extra Mexico capex feel incremental to the near term story rather than a major catalyst. In the short term, focus still sits on margin repair after weaker profit trends, cash flow discipline given debt levels, and how efficiently Nestlé reallocates marketing and R&D toward higher return segments.
The fresh US$1b investment plan in Mexico through 2030 is the operational announcement that matters most here. It links directly to manufacturing scale for coffee, dairy and related categories in one of Nestlé’s larger markets, where it already reports CHF 3.8b of revenue, and to the broader efficiency efforts investors are tracking.
For you as a shareholder, that extra Mexico outlay feeds into two watchpoints. The first is execution quality on plant modernization and technology adoption, which can support margin resilience. The second is the strain on free cash flow and leverage while dividend coverage is already tight and one off items have recently affected earnings quality.
Nestlé's analyst narrative points to CHF 94.7b in revenue and CHF 12.0b in earnings by 2029, built on 1.7% yearly revenue growth and an earnings increase of CHF 3.0b from current earnings of CHF 9.0b.
Uncover why Nestlé's fair value indicates a 14% potential upside to its current price that could narrow quickly.
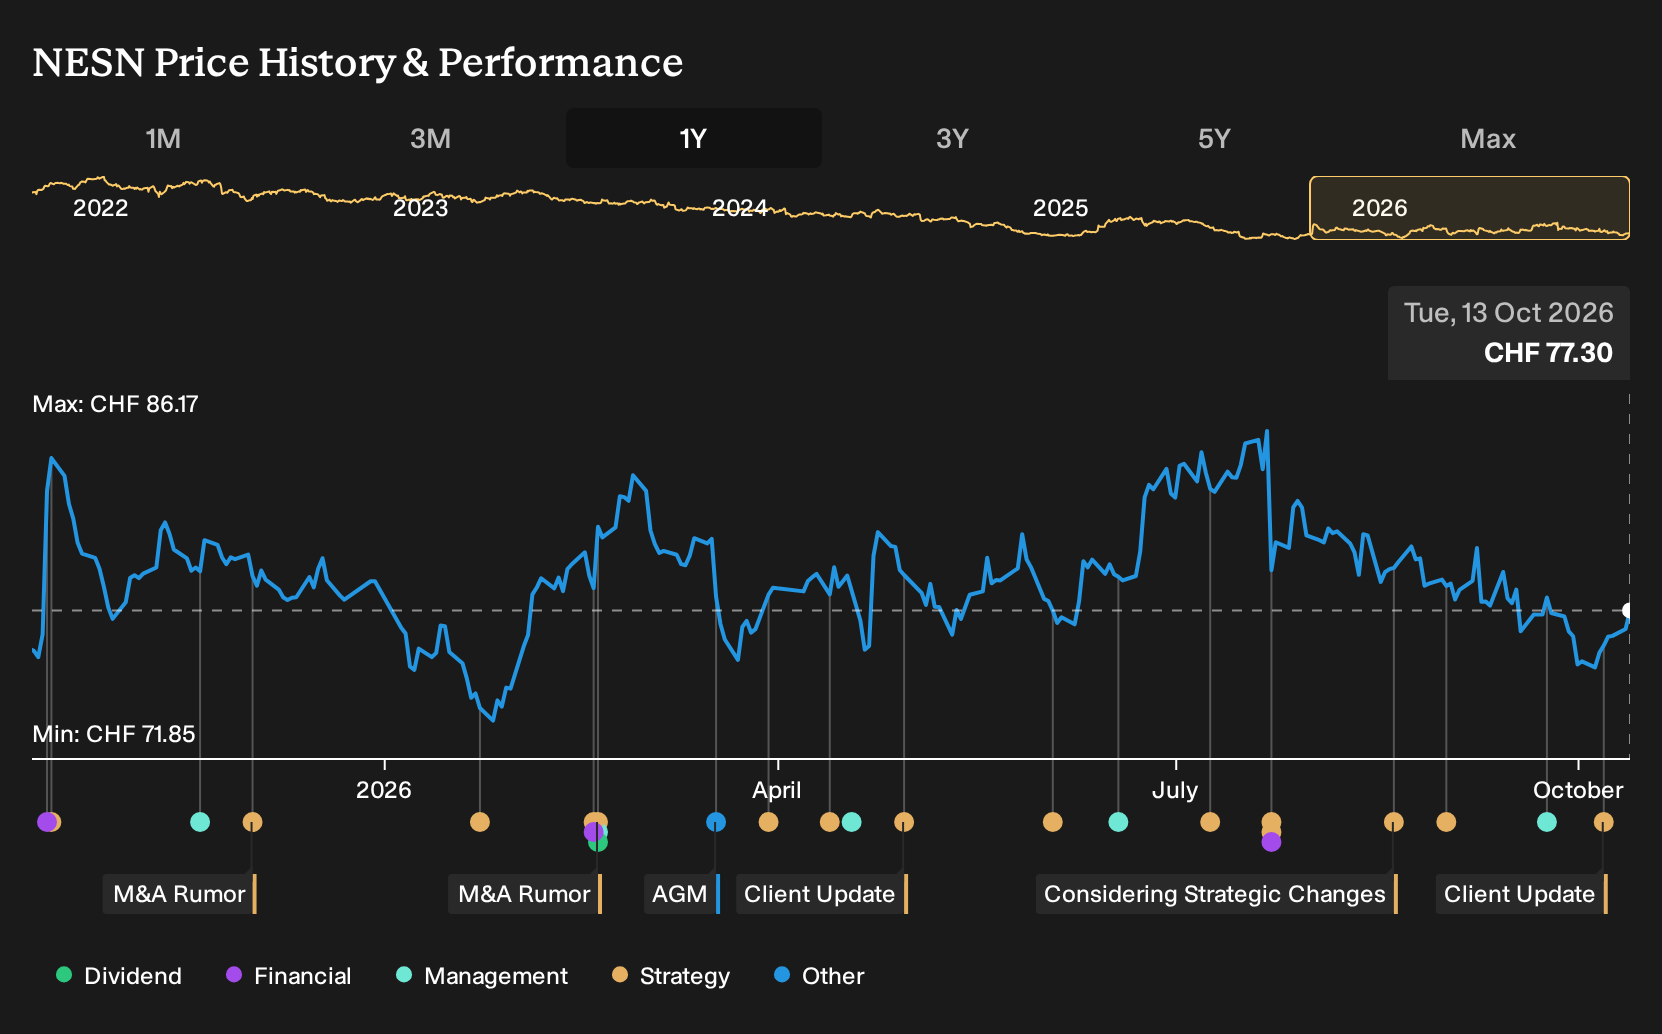
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span roughly CHF 88 to CHF 138, so some retail investors see Nestlé as heavily undervalued while others price in a premium. Set that against risks like sustained margin pressure from commodity costs and tariffs, and you get sharply different conclusions about future resilience.
Explore 3 other Nestlé fair value estimates, including one that suggests as much as 79% potential increase from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Nestlé research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Nestlé. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nestlé's overall financial health at a glance.
Looking For More Nestlé Sized Ideas?
If Nestlé has you thinking about scale, resilience and steady balance sheets, it can help to line it up against a wider field of potential opportunities before committing fresh capital.
- For investors who care most about capital preservation and calmer drawdowns, start with a group of 223 resilient stocks with low risk scores that score well on resilience metrics and risk checks.
- If value is the priority and you want quality businesses trading below many fair value estimates, scan through 184 high quality undervalued stocks that combine solid fundamentals with more modest pricing.
- When the goal is to back underfollowed stories rather than crowded trades, focus on 619 high quality undiscovered gems that pair strong financial footing with limited current attention from the broader market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com