


In the last week, the United States market has remained flat, though it has experienced a 14% rise over the past year with forecasts suggesting annual earnings growth of 17%. In this context, identifying good stocks often involves finding those that are undervalued yet poised to benefit from insider confidence and broader market trends.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.8x | 0.5x | 28.23% | ★★★★★★ |
| Financial Institutions | 9.4x | 3.1x | 26.67% | ★★★★★☆ |
| Enovis | NA | 0.5x | 41.61% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.0x | 34.91% | ★★★★☆☆ |
| Union Bankshares | 9.4x | 2.0x | 45.63% | ★★★★☆☆ |
| Bank of the James Financial Group | 10.7x | 2.4x | 27.93% | ★★★★☆☆ |
| Shore Bancshares | 11.3x | 3.3x | 36.64% | ★★★★☆☆ |
| German American Bancorp | 12.9x | 4.8x | 26.93% | ★★★☆☆☆ |
| New Peoples Bankshares | 9.5x | 2.6x | 8.02% | ★★★☆☆☆ |
| Orion Group Holdings | 102.8x | 0.4x | 45.31% | ★★★☆☆☆ |
Let's dive into some prime choices out of from the screener.
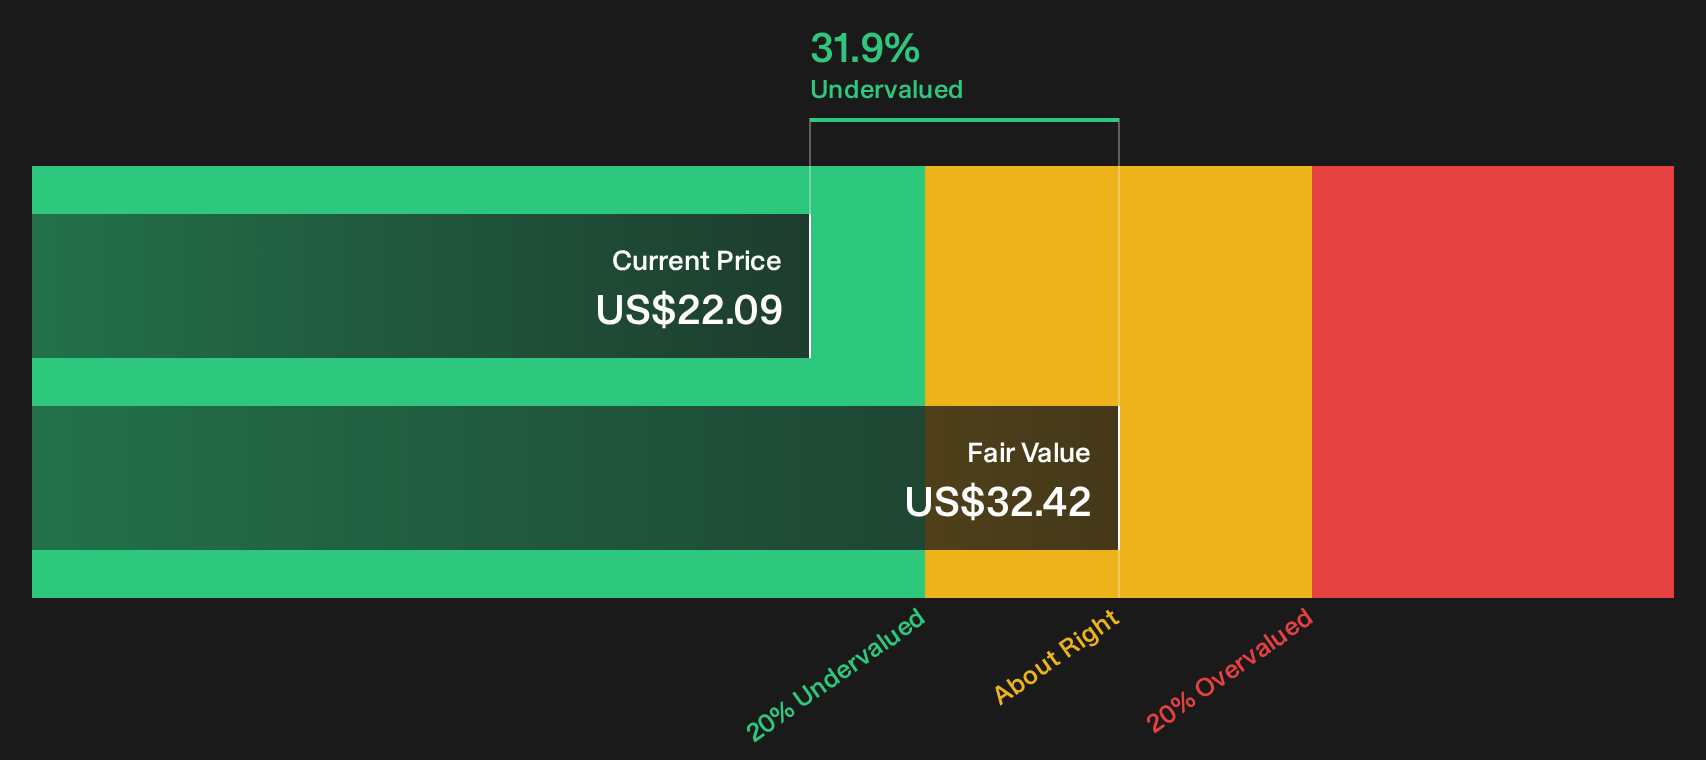
California BanCorp (BCAL)
Simply Wall St Value Rating: ★★★★☆☆
Overview: California BanCorp operates as a commercial banking institution, focusing on providing a range of financial services and products, with a market capitalization of approximately $0.20 billion.
Operations: The company generates its revenue primarily from commercial banking activities, with recent figures showing $184.29 million in revenue. Operating expenses are a significant cost component, reaching $93.16 million in the latest period, largely driven by general and administrative expenses amounting to $84.13 million. The net income margin has shown a notable trend with the most recent figure at 32.66%.
PE: 11.4x
California BanCorp, a smaller player in the financial sector, shows potential for value with recent insider confidence through share purchases. Their second-quarter results revealed net interest income of US$43.35 million, up from US$41.42 million last year, and a slight increase in net income to US$14.3 million. The company repurchased 102,594 shares for US$2 million between April and June 2026, signaling strategic capital management. A dividend increase to $0.12 per share underscores their commitment to returning value to shareholders amidst modest growth prospects.
- Get an in-depth perspective on California BanCorp's performance by reading our valuation report here.
Assess California BanCorp's past performance with our detailed historical performance reports.
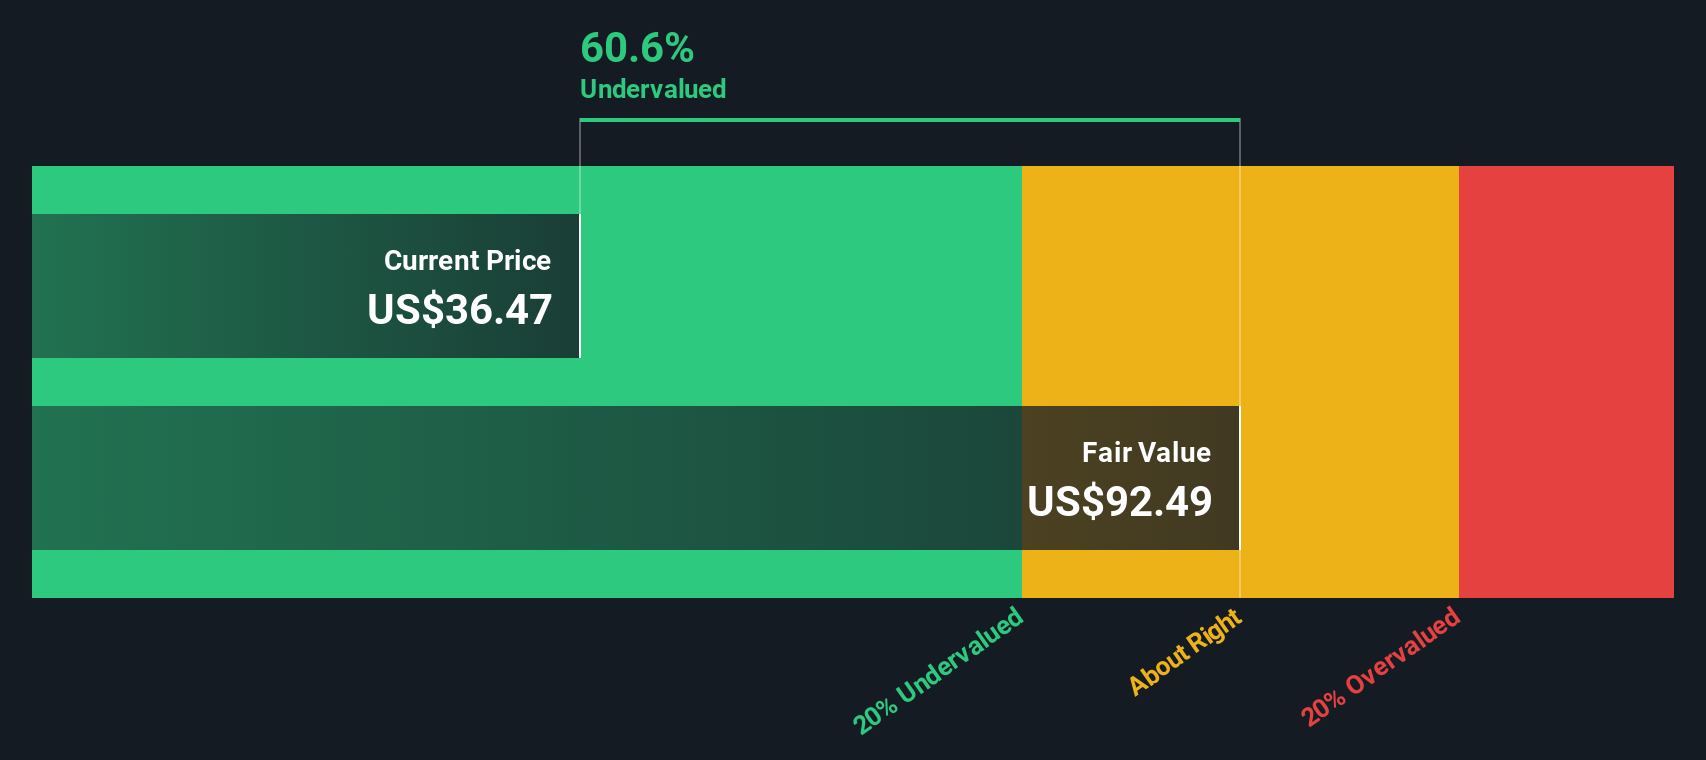
Kemper (KMPR)
Simply Wall St Value Rating: ★★★★★☆
Overview: Kemper is an insurance company primarily engaged in providing specialty property and casualty insurance, along with life insurance services, with a market capitalization of approximately $3.5 billion.
Operations: The company's primary revenue stream is from Specialty Property & Casualty Insurance, generating $3.96 billion, with Life Insurance contributing $591.1 million and Non-Core Operations adding $65.5 million. Over recent periods, the gross profit margin has shown fluctuations, reaching 35.50% in late 2024 before declining to 25.40% by mid-2026, indicating variability in cost management or pricing strategies over time.
PE: -3.3x
Kemper's recent leadership overhaul aims to streamline operations across its P&C and Life divisions, potentially enhancing strategic focus. Despite a challenging financial period marked by a US$464.8 million net loss in Q2 2026, the company maintains its dividend at US$0.32 per share, signaling commitment to shareholder returns. Insider confidence is evident with recent purchases indicating belief in future prospects despite current earnings pressures and reliance on external borrowing for funding.
- Click here and access our complete valuation analysis report to understand the dynamics of Kemper.
Gain insights into Kemper's historical performance by reviewing our past performance report.
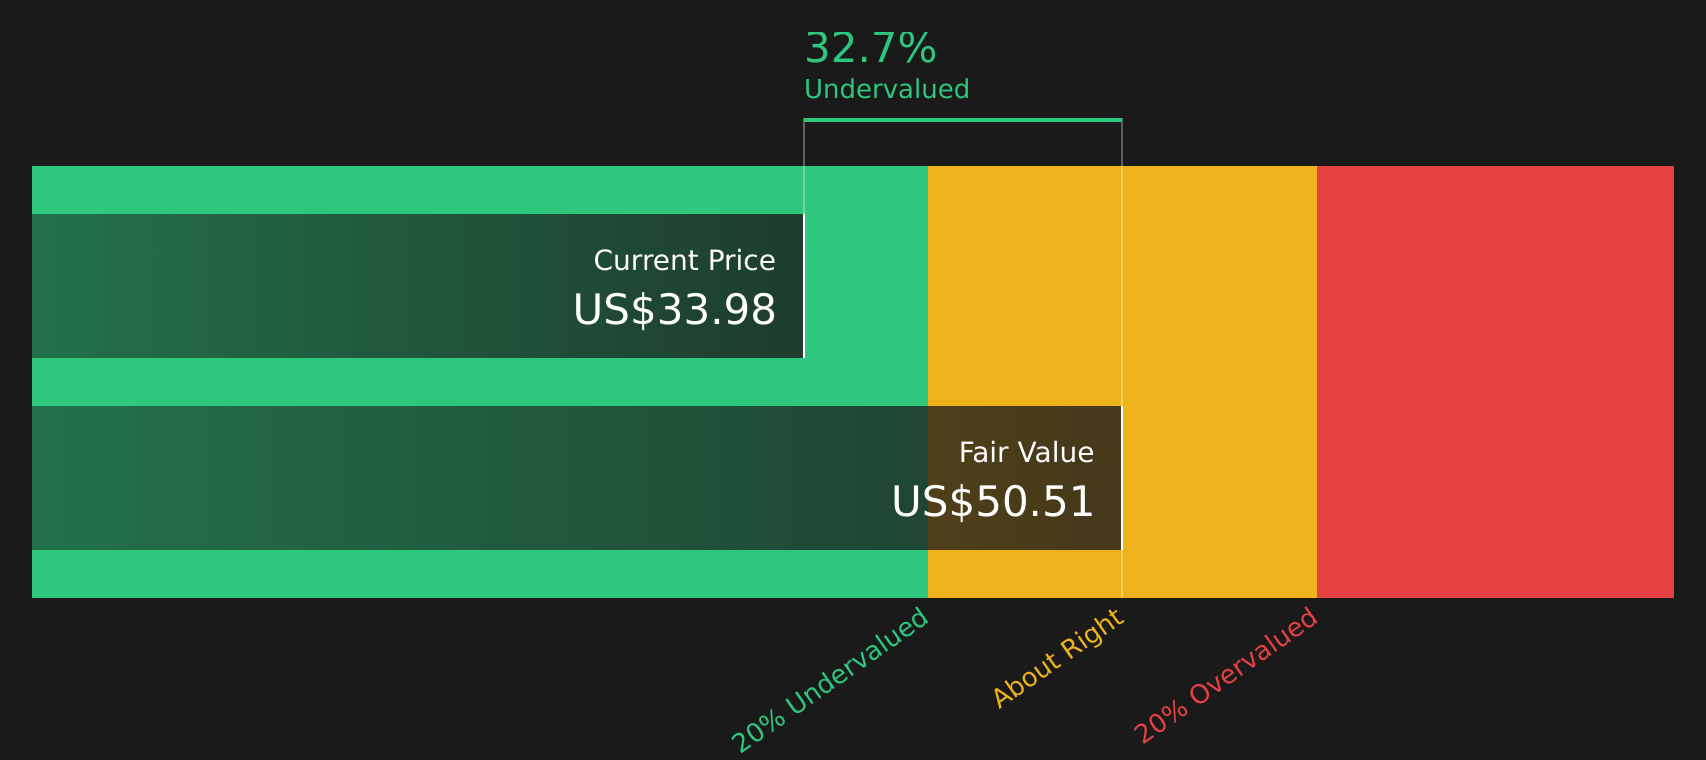
Regional Management (RM)
Simply Wall St Value Rating: ★★★★★★
Overview: Regional Management is a consumer finance company that provides personal loans primarily to customers with limited access to credit, and it has a market capitalization of approximately $0.22 billion.
Operations: The company generates revenue primarily through its consumer finance segment, with recent figures reaching $647.84 million. The gross profit margin has shown variability, recently recorded at 59.75%. Operating expenses have consistently been a significant cost component, totaling $236.05 million in the latest period. Net income was reported at $46.82 million, reflecting a net income margin of 7.23%.
PE: 6.8x
Regional Management, a smaller U.S. firm, has seen insider confidence through recent share purchases, indicating potential value recognition within the company. Despite relying solely on external borrowing for funding, which carries higher risk compared to customer deposits, the company forecasts earnings growth of 15% annually. Recent guidance anticipates net income increases in upcoming quarters and full-year diluted earnings per share growth between 10% and 13%. The firm repurchased 136,325 shares for US$5 million recently.
- Delve into the full analysis valuation report here for a deeper understanding of Regional Management.
Explore historical data to track Regional Management's performance over time in our Past section.
Make It Happen
- Embark on your investment journey to our 63 Undervalued US Small Caps With Insider Buying selection here.
- Are any of these part of your asset mix? Tap into the analytical power of Simply Wall St's portfolio to get a 360-degree view on how they're shaping up.
- Streamline your investment strategy with Simply Wall St's app for free and benefit from extensive research on stocks across all corners of the world.
Curious About Other Options?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com