


Red Rock Resorts has pulled back over recent months after a solid multi year run, which puts fresh attention on whether the current share price still lines up with what the casino operator is earning. With the stock changing hands at US$50.83 at the last close, the key issue now is how those earnings stack up against that price tag.
- Over the past 3 years the stock has returned 33.6%, so anyone looking at Red Rock Resorts today is effectively asking whether that kind of share price journey still matches the earning power of the business.
- The company leans heavily on cash generation from its regional casino portfolio, which can influence how comfortably its earnings cover ongoing investment needs and shareholder returns.
- There is a second opinion on Red Rock Resorts worth weighing. See what analysts think Red Rock Resorts's shares could be worth.
For investors, the debate is whether Red Rock Resorts' current valuation is properly supported by the level and quality of its earnings today.
If you want to see how Red Rock Resorts' earnings story compares with other opportunities, it can help to line it up against 32 high quality undervalued stocks.
Is Red Rock Resorts a Bargain on Earnings?
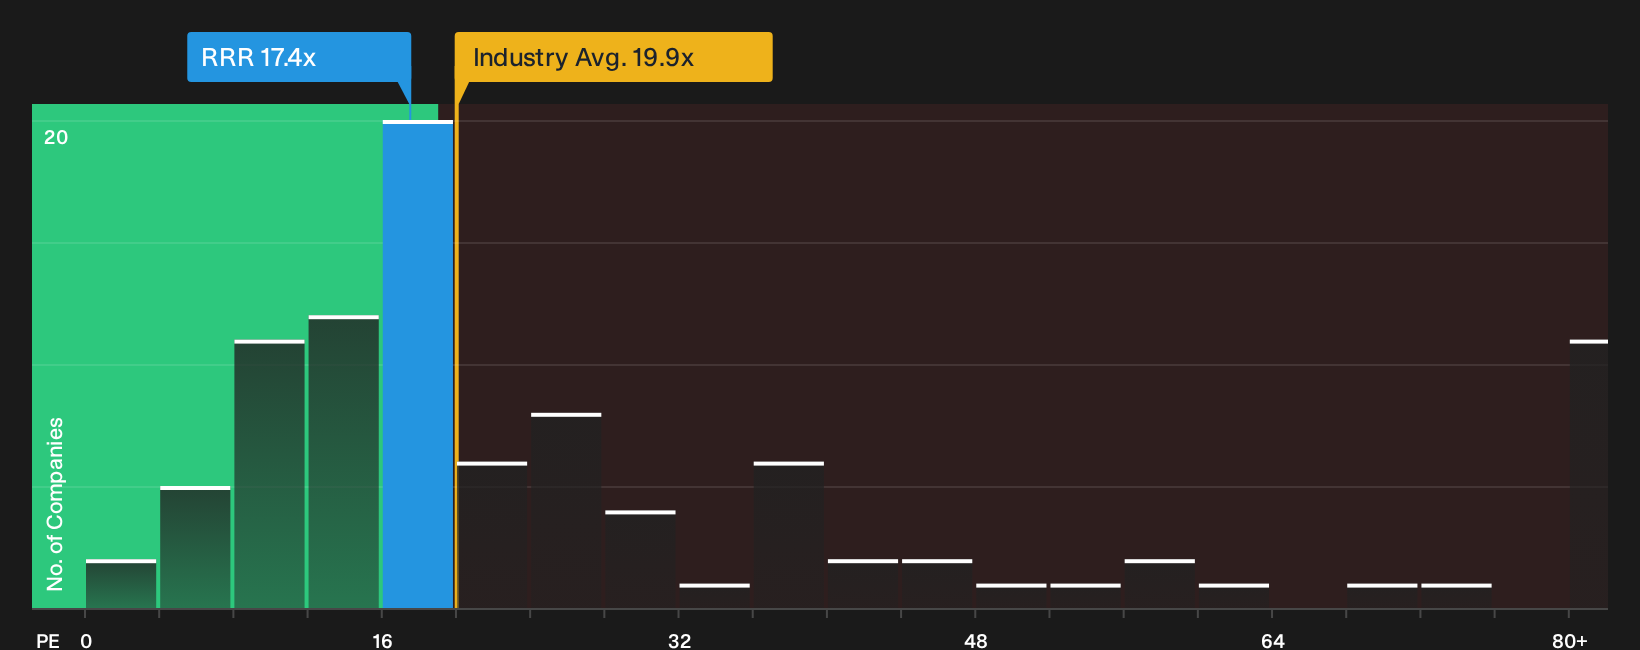
The P/E ratio suits Red Rock Resorts because earnings are central to how investors tend to judge casino operators with meaningful free cash flow. At the current price, the shares trade on a P/E of 17.4x, which is below the hospitality industry average of 19.9x and above the peer group average of 12.4x. That mix signals the market is giving the business some credit for its regional casino cash flows, but not pricing it as highly as the broader hospitality sector.
The fair value framework, which adjusts the P/E multiple for Red Rock Resorts' growth profile, profitability, scale and risk, points to a higher ratio than the one implied by the share price today. That places the current 17.4x earnings multiple below the level the model would usually expect for this type of earnings stream, suggesting the stock screens as undervalued on this specific measure for now. Explore the numbers behind Red Rock Resorts's P/E valuation.
The Red Rock Resorts Narrative: What Would Justify Today's Price?
Red Rock Resorts' valuation question naturally feeds into Simply Wall St Narratives, which clearly outline what kind of future growth, margins and earnings power would need to materialise for the stock to trade meaningfully higher or lower than it does today. Each Narrative treats fair value as a thesis about how Red Rock Resorts' business might unfold over time, so you can compare those expectations with real world results side by side on the Community page.
One of the top community narratives on Red Rock Resorts: 31% undervalued
"The key issue is whether heavy renovation and construction spending, along with higher utilities and disruption at properties like Green Valley Ranch, Durango and Sunset Station, results in sustained guest demand and supports the current level of cash generation…"
Discover why this Narrative puts Red Rock Resorts at 31% undervalued.
Before focusing on Red Rock Resorts’ price tag, weigh the risk checks
Valuation only tells part of the Red Rock Resorts story, because Simply Wall St’s broader research has flagged specific risk checks that deserve your attention before you go any further. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com