


Inflation worries are flaring again as higher gasoline prices lift the latest US CPI reading, and that kind of sticky cost pressure tends to reward companies that generate solid cash and trade at a discount. Investors who focus on businesses priced below what their future cash flows suggest they could be worth may find mispriced opportunity. This article highlights three such stocks that screen as undervalued on cash flow.
The three stocks below are just a sample, as the full screen surfaced 454 more companies with equally cash focused narratives that do not fit into this article.
If you want to identify and analyze those additional opportunities right now, head straight to the Undervalued Stocks Based On Cash Flows screener.
Wells Fargo (WFC)
Wells Fargo is a large US-focused bank whose consumer banking and lending arm, including mortgages and everyday loans, generates recurring cash flows that feed directly into the cash-based valuation work behind this screener.
Those activities sit alongside Commercial Banking at about US$11.9b in revenue, Corporate and Investment Banking at roughly US$20.2b, and Wealth and Investment Management at about US$17.3b. This gives the group a diversified mix on top of its cash-flow-rich consumer operations and a market value of roughly US$252b.
For value-focused investors, Wells Fargo’s appeal in this list comes from how its everyday lending engine, fee pools and capital position link through to discounted cash flow estimates rather than just headline earnings or short-term share moves.
"The removal of the asset cap and resolution of regulatory orders has already allowed Wells Fargo to grow average loans 12% year over year and average deposits 10% in 2Q26. Continued deployment of this larger balance sheet alongside a targeted CET1 range of 10% to 10.5% with potential 7% lower risk weighted assets is set up to influence revenue and earnings."
What happens if one quiet pressure on those cash-rich loan and deposit flows shifts direction will matter a lot for margins and valuation.
As that margin pressure shifts, read the full narrative for Wells Fargo to see how Wells Fargo’s cash engine could decouple from headline noise and where risks really sit.
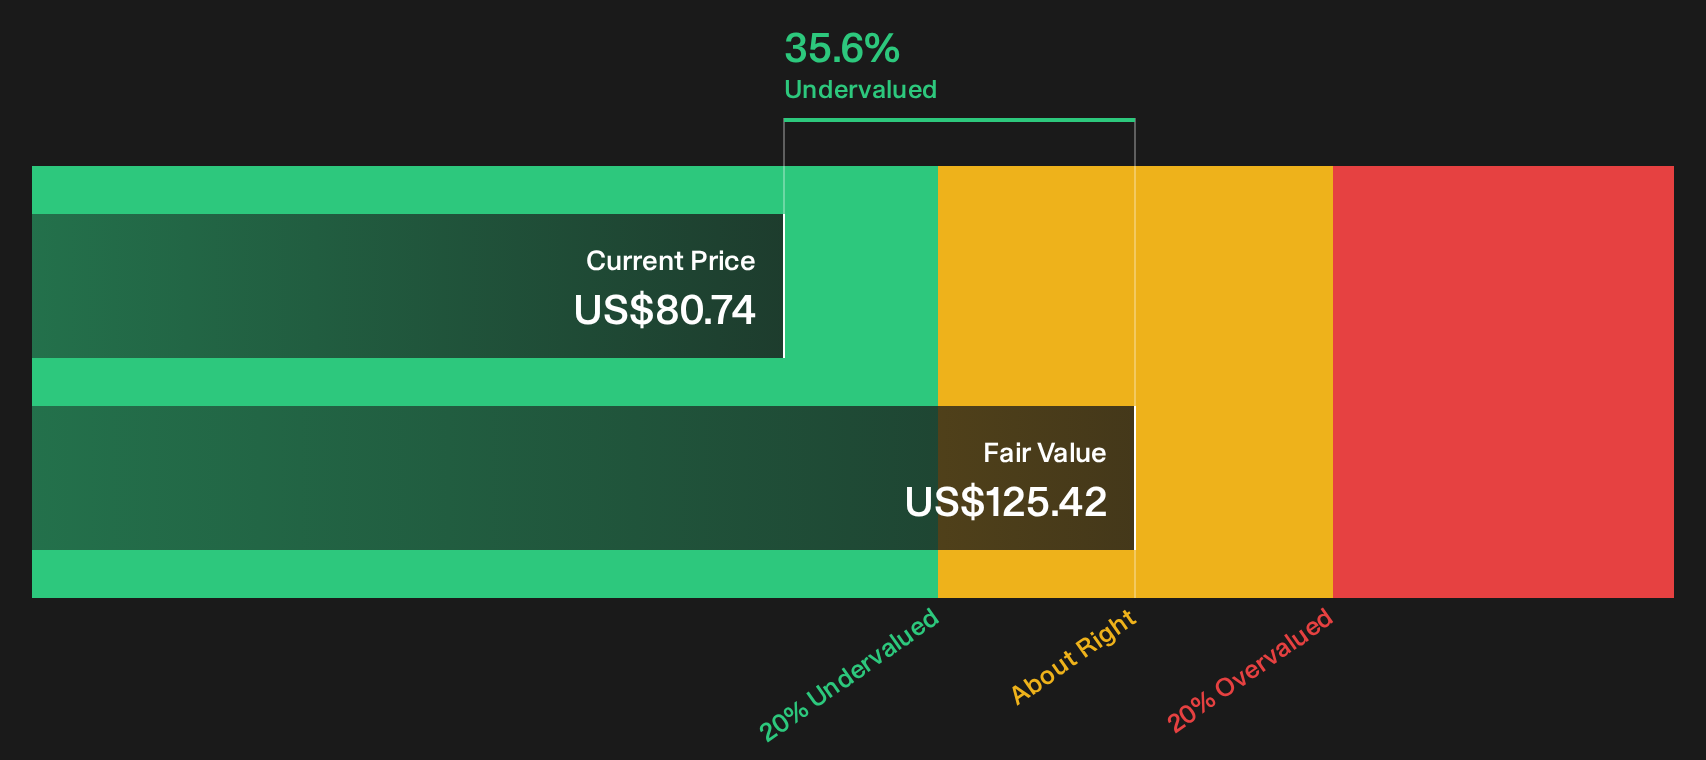
Signet Jewelers (SIG)
Signet Jewelers is a global jeweler whose core store and online chains like Kay, Zales, Jared, James Allen and Blue Nile generate the retail cash flows that anchor its place in this cash-flow-focused undervaluation screen.
Signet earns most of its revenue from North America at about US$6.4b, with the International segment contributing roughly US$423 million and the Other segment, which includes diamond polishing, adding around US$18 million, and the business carries a market value near US$4.1b.
For investors watching how discounted cash flow signals line up with real-world trading levels, Signet Jewelers brings together a cash generative retail engine, improving profitability and active capital returns in a way that directly speaks to this screen’s focus on free cash flow value.
"Significant growth in lab-grown diamond (LGD) fashion assortment (penetration doubled from last year to 14%) and focus on accessible price points (in the US$200 to US$500 range) position Signet to expand market share and increase revenue, while higher margin LGD products boost gross margins."
What happens if one unresolved pressure on those higher margin jewelry lines shifts will matter a lot for how far cash flows reach fair value.
If that pressure point is on your radar, read the full narrative for Signet Jewelers to learn how Signet Jewelers’ cash engine and LGD mix could be getting mispriced.

Yadea Group Holdings (SEHK:1585)
Yadea Group Holdings designs and sells electric scooters, e-bikes and related parts that drive its cash flows, with electric two-wheeled vehicles and accessories contributing about CN¥34.1b and batteries and electric drives around CN¥7.7b. This China-focused manufacturer has a market value near HK$28.1b.
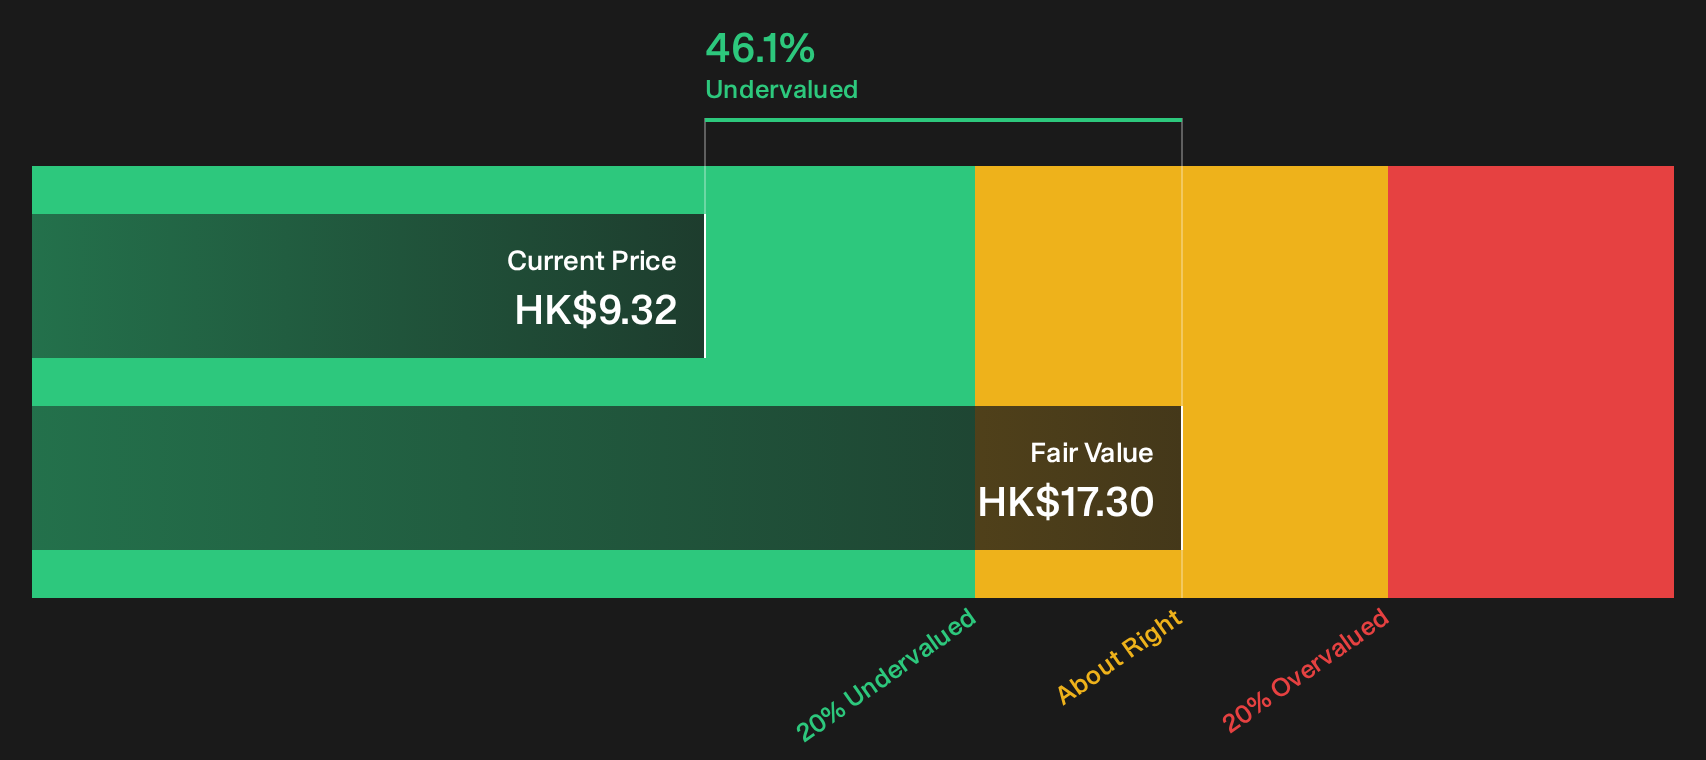
Yadea Group Holdings aligns closely with this cash-flow-based screen because nearly all of its value comes from selling electric two-wheelers and batteries that are directly modeled in a DCF. Earnings growth of 30.5% and a P/E of 9.9x are cited to help explain why the identified 46.1% discount to fair value may matter if a single pressure on margins shifts direction.
That potential margin reset could be pivotal. Check the DCF valuation analysis for Yadea Group Holdings to see how Yadea Group Holdings’ cash engine compares with its current pricing.
Seeking Alternatives Before The Crowd
Fresh opportunities can move from quiet to flying once cash flows, momentum and sentiment line up. Spot potential breakouts under the radar for now and get in early.
- Target steady income hunters by scanning 8 dividend fortresses that aim to keep payouts coming even when share prices feel choppy.
- Hunt for resilient operators using the 32 resilient stocks with low risk scores that filters for businesses with sturdier balance sheets and calmer risk profiles.
- Track the next infrastructure wave through the 43 power grid technology and infrastructure stocks and see which enablers of electricity upgrades might be building quiet momentum.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com