


Stifel Nicolaus recently reaffirmed its positive rating on Align Technology (ALGN) while trimming its price expectation, a move that highlights how some analysts are reassessing valuations across healthcare stocks without abandoning growth-oriented ideas.
Recent trading tells a mixed story for Align Technology. The share price closed at US$143.54 with a 1-day share price return of 2.22% and a 7-day share price return of 1.48%. However, the 30-day and 90-day share price returns are down 4.83% and 20.81% respectively. The 1-year total shareholder return is positive at 10.59%, but the 3-year and 5-year total shareholder returns show deep declines. This suggests that short term sentiment has weakened even as longer term holders are still working through a reset in expectations.
Scan beyond Align Technology and review a hand picked 32 high quality undervalued stocks that analysts are watching as sentiment and price targets reset across growth driven healthcare names.
Bulls point to Align Technology’s revenue and profit growth, plus a wide analyst target gap, while bears focus on multi year share price declines. The next question is which side current valuation actually supports.
Most Popular Narrative: 30.4% Undervalued
On Simply Wall St’s most followed narrative, Align Technology’s fair value of $206.36 sits well above the last close at $143.54. This frames the stock as meaningfully discounted while analysts still anchor on measured growth and margin improvement assumptions.
The plan to expand operating margin by about 100 basis points in 2026 and at least another 100 basis points in 2027, supported by higher gross margins from mix shift toward fewer refinement products and operational efficiencies, points to potential upside for net margins and earnings if executed as outlined.
See why 29 investors see Align Technology as 30% undervalued.
Result: Fair Value of $206.36 (UNDERVALUED)
Still, the narrative around Align Technology could be knocked off course if North America Invisalign demand stays weak or if scanner revenue pressure drags on margins.
Find out about the key risks to this Align Technology narrative.
Another View: What Multiples Say About Align Technology
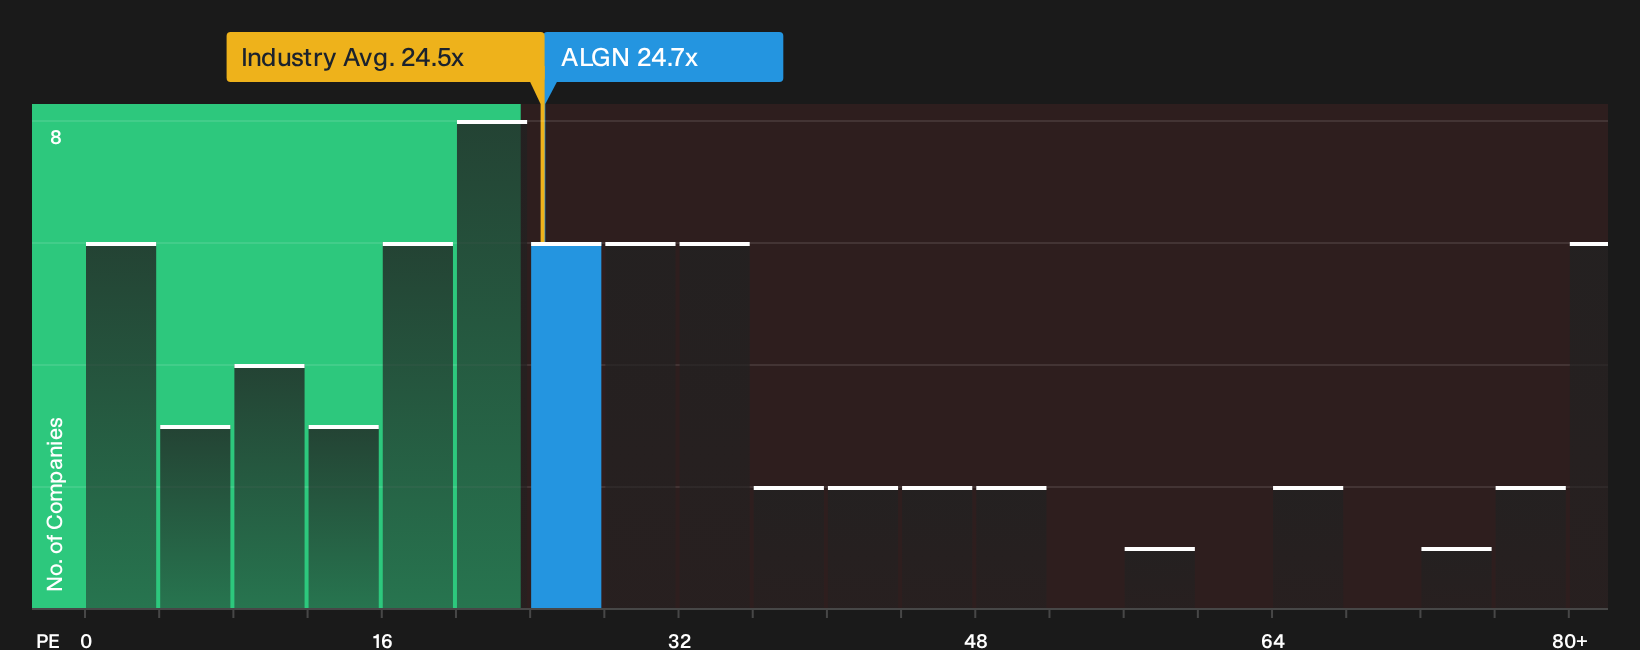
Our narrative based fair value sees Align Technology as meaningfully undervalued, yet the market is not giving the shares away on earnings. The stock trades on a P/E of 24.7x, slightly above the US Medical Equipment industry on 24.3x, although below peers on 27.4x and the fair ratio of 28.8x. That mix of a small premium to the sector and a discount to both peers and the fair ratio suggests limited margin of safety if growth underwhelms, but room for rerating if analyst forecasts prove realistic. Which side of that trade-off are you more comfortable with?
For a closer look at how that earnings based view stacks up against a cash flow driven approach, review the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Align Technology is split, which is exactly why it helps to move fast, pull up the key charts, and pressure test the bull and bear cases against your own risk tolerance before acting on anything you read, starting with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Align Technology?
If you only stop at Align Technology, you miss out on other setups that may better fit your goals, risk appetite, and time horizon.
- Target potential mispricings by scanning a curated 32 high quality undervalued stocks that combine solid fundamentals with more attractive entry points.
- Strengthen your income plan by reviewing a focused 8 dividend fortresses that aim to pair higher yields with durable payout histories.
- Sleep easier in choppy markets by filtering for a 32 resilient stocks with low risk scores that score well on balance sheet strength and volatility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com