


Medpace Holdings (MEDP) has become a talking point for investors after its recent share price moves, with the stock last closing at US$609.89 and posting double digit total returns over the past 3 years.
Over the past quarter Medpace Holdings has built steady momentum, with a 90 day share price return of 15.24% and a year to date gain of 6.81%. The 1 year total shareholder return of 17.98% and 3 year total shareholder return of 152.80% show how strongly longer term holders have been rewarded, even after occasional single day pullbacks like the recent 1.64% decline.
Scan for other contract research groups showing similar momentum to Medpace Holdings by focusing on 20 high quality undiscovered gems in the current market.
After such strong recent gains, investors looking at Medpace Holdings now face a familiar crossroads: pay up at today’s price, or wait and risk missing the next leg if the valuation already holds up.
Most Popular Narrative: 14% Overvalued
The current Medpace Holdings share price of $609.89 sits above the narrative fair value estimate of $536.00, which puts today’s enthusiasm in tension with that valuation gap.
Medpace appears to be a high-quality CRO because it combines a differentiated small-biotech focus, strong therapeutic expertise, a global full-service platform, operating margins above 20%, low capital requirements, substantial cash and no funded debt.
The balanced conclusion is less promotional than “dominates a profitable niche”. Medpace has built a strong position in a difficult-to-replicate part of the CRO market, but its revenue is not locked in, its customers can be financially fragile, and founder control brings related-party governance considerations. At around 35 times management’s 2026 earnings guidance, the business quality is evident; the margin of safety in the share price is less obvious.
See why 7 investors see Medpace Holdings as 14% overvalued.
Result: Fair Value of $536 (OVERVALUED)
Still, the Medpace Holdings story can be knocked off course if small and mid-sized biotech clients struggle for funding or if cancellations start to hit that backlog.
Find out about the key risks to this Medpace Holdings narrative.
Another View: Medpace Valuation Through The P/E Lens
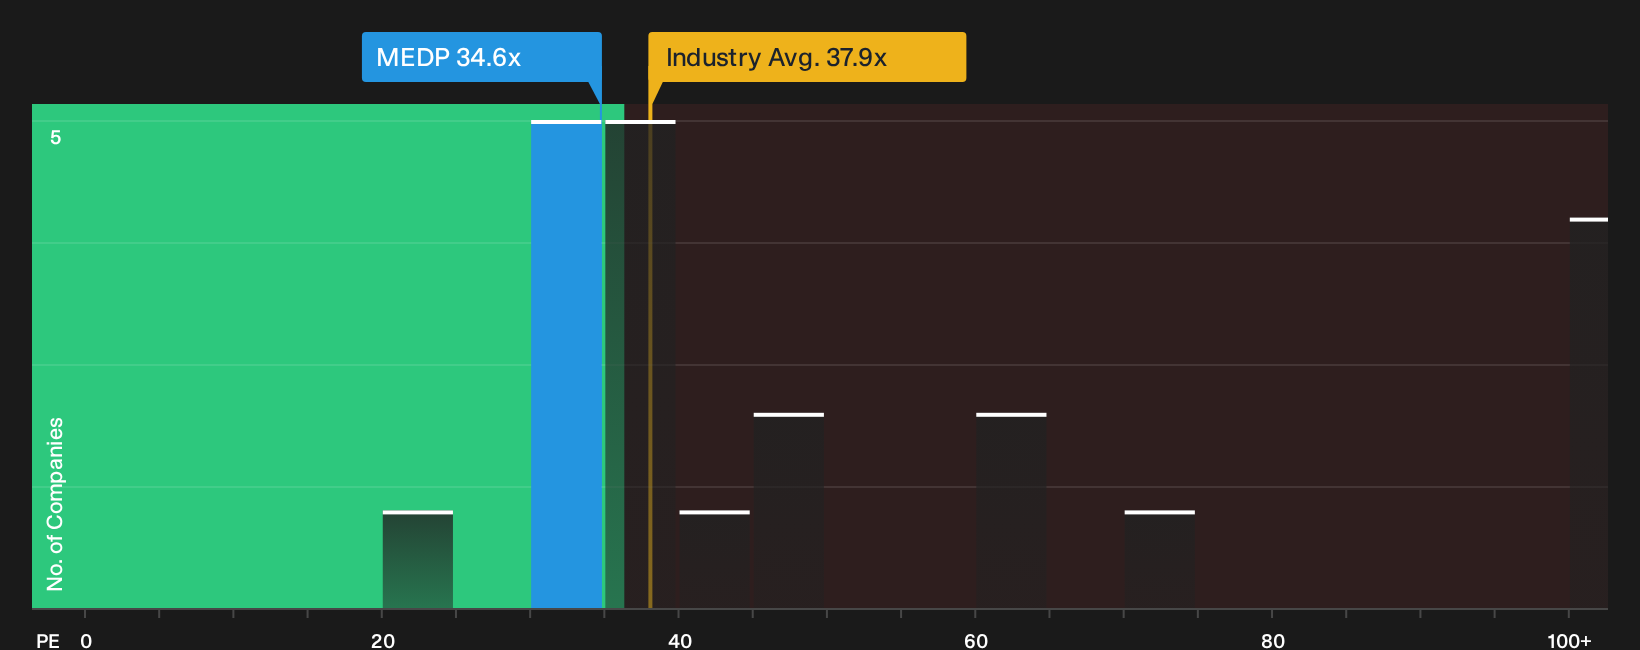
Looking at Medpace Holdings through the P/E ratio gives a different perspective. The stock trades on 34.6x earnings, which is lower than the peer average of 51.2x and below the Global Life Sciences group on 38.4x, yet above an estimated fair ratio of 22.2x that the market could eventually lean toward.
This mix means investors are paying a premium to the fair ratio, while still getting a discount to both direct peers and the wider industry. The gap can work either way for investors if sentiment or earnings expectations reset.
To see what the numbers indicate about this price in more detail, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Medpace Holdings can feel uncomfortable, yet this is usually when closer analysis matters most and quick decisions leave the biggest imprint. For a more complete picture, weigh both sides of the story by checking the 3 key rewards and 1 important warning sign.
Looking for more Medpace Holdings style ideas?
If you stop with Medpace Holdings, you may miss other compelling setups. Use the Screener to surface fresh ideas tailored to the way you like to invest.
- Target resilient balance sheets and steady fundamentals by running a tightly filtered list of solid balance sheet and fundamentals (25 results) that screens out weaker financial profiles.
- Hunt for potential value opportunities by focusing on companies trading below intrinsic estimates through the 32 high quality undervalued stocks that already applies strict quality checks.
- Prioritise capital preservation by filtering for stocks with relatively lower risk markers, using the 32 resilient stocks with low risk scores that narrows the field to sturdier candidates.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com