


Investor attention around Ovintiv (OVV) is building ahead of its 4 November third quarter call, as recent buyback activity and expectations for solid free cash flow put capital allocation choices in sharper focus.
At a share price of $66.66, Ovintiv has logged a 90 day share price return of 18.93% and a year to date share price return of 64.63%. Its 1 year total shareholder return of 85.26% and 5 year total shareholder return of 92.03% suggest that recent buyback activity and expectations for steady free cash flow are contributing to stronger momentum rather than fading enthusiasm.
Scan for other energy producers pairing shareholder returns with disciplined balance sheets by reviewing the hand picked list of solid balance sheet and fundamentals (25 results), which echoes parts of the Ovintiv playbook.
That kind of move in Ovintiv could signal that investors are simply paying up for steadier execution rather than chasing a mood shift. Do the current valuation markers support that view, or are they getting ahead of the business?
Most Popular Narrative: 12.9% Undervalued
Ovintiv's most followed narrative pegs fair value at $76.50, noticeably above the recent $66.66 close. This framing pushes investors to focus on whether efficiency gains and inventory depth can carry that gap.
Ongoing efficiency gains in Ovintiv's Permian and Montney programs, including cube development, real time frac optimization, Simul frac, AI driven drilling control, and wet sand, are supporting more than a 10% improvement in oil productivity per foot since 2023 and D&C costs below $600 per foot in the Permian and $500 per foot in the Montney. These gains can feed into stronger net margins and earnings over time.
See why 12 investors see Ovintiv as 13% undervalued.
Result: Fair Value of $76.50 (UNDERVALUED)
Still, that narrative can crack if Ovintiv records another large impairment that hits earnings, or if the current premium to some intrinsic models leads to a sharp de rating.
Find out about the key risks to this Ovintiv narrative.
Another View: Ovintiv Through The Earnings Lens
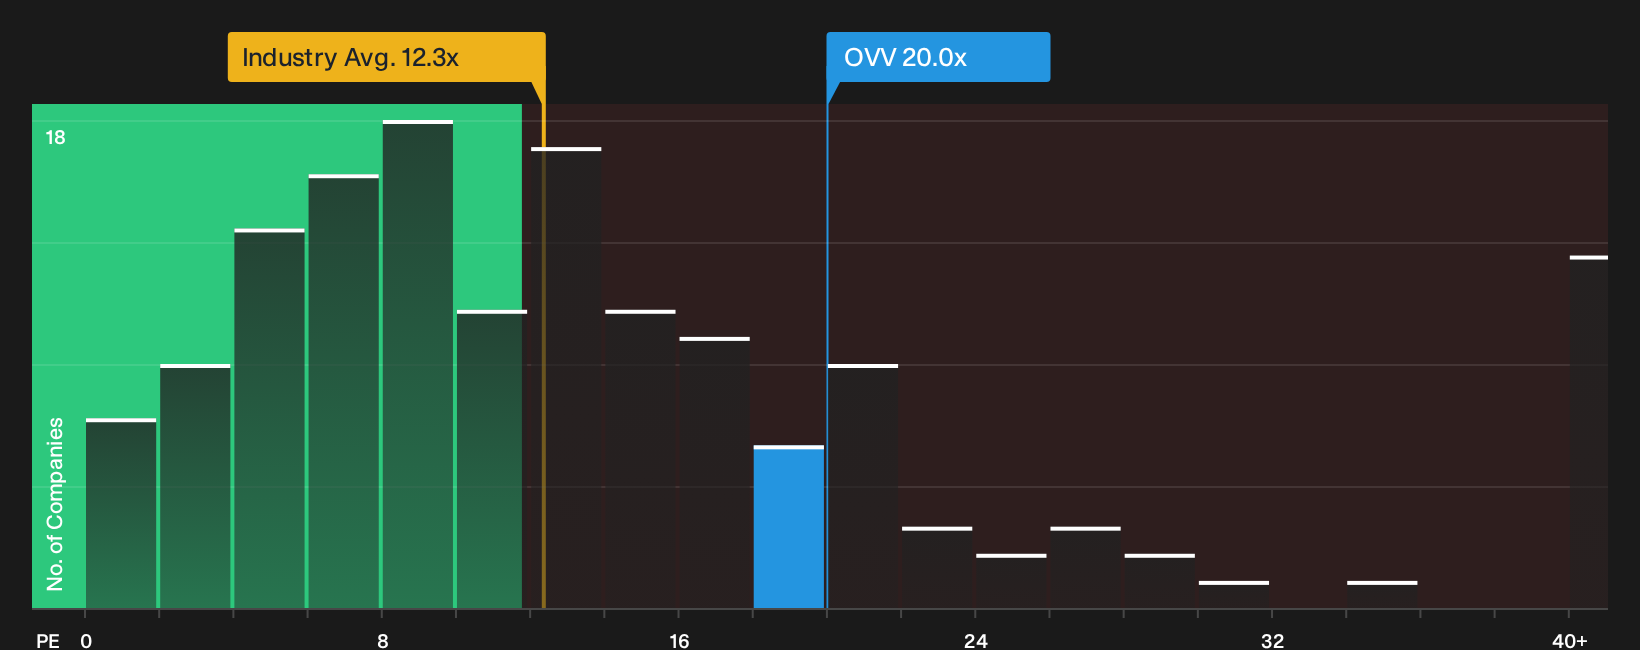
That 12.9% discount to a $76.50 fair value leans on cash flows and efficiency. The earnings multiple tells a different story. Ovintiv trades at about 20x P/E versus roughly 12x for both the US Oil and Gas industry and its peer set, while the fair ratio points nearer to 22x. That gap suggests investors are already paying a premium, even if the model argues there is still room for upside. How comfortable are you with paying above sector norms for this earnings profile?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ovintiv's valuation and sentiment can feel messy, so move quickly, review the underlying data, and weigh both the potential upside and the embedded risks by checking the 3 key rewards and 2 important warning signs.
Looking for more Ovintiv-like investment ideas?
If the Ovintiv story has your attention, do not stop here. Use the Simply Wall Street Screener to surface other opportunities before they move without you.
- Target resilient value by reviewing the 32 high quality undervalued stocks that blend strong fundamentals with pricing that still looks reasonable.
- Strengthen portfolio stability by focusing on the 32 resilient stocks with low risk scores designed to highlight companies with more measured risk profiles.
- Spot early-stage potential by scanning the 11 elite penny stocks with strong financials that pair smaller market caps with financial traits you can actually scrutinize.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com