


The Estée Lauder Companies Inc. (EL), based in New York, is a global prestige beauty company that develops, manufactures, markets, and sells skincare, makeup, fragrance, and haircare products. It has a market capitalization of approximately $36.2 billion. Its portfolio includes over 20 luxury brands, serving consumers across approximately 150 countries and territories worldwide.
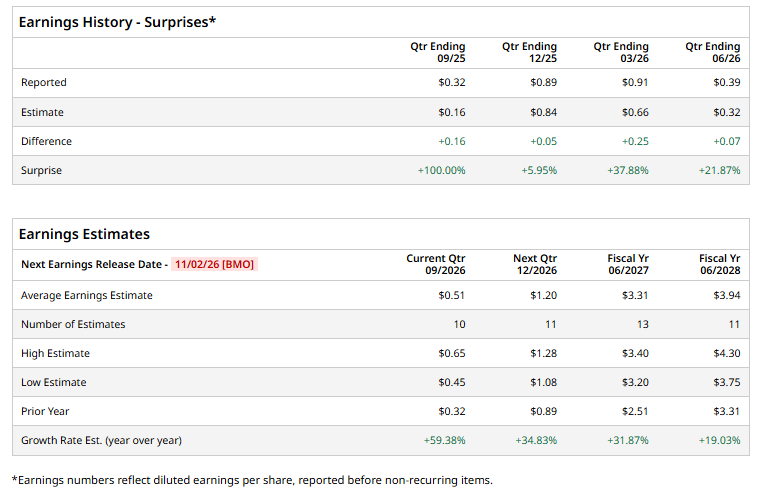
EL is set to report its Q1 earnings on Monday, November 2, 2026, before the market opens. Ahead of the release, analysts expect the company to report diluted EPS of 51 cents, up 59.4% from 32 cents in the year-ago quarter. Likewise, EL has exceeded Wall Street’s EPS estimates in each of the past four quarters, highlighting its consistent earnings performance.
For fiscal 2027, analysts expect EL to report EPS of $3.31, up 31.9% from $2.51 in fiscal 2025. EL’s EPS is projected to grow further to $3.94 in fiscal 2028, representing year-over-year growth of 19%.
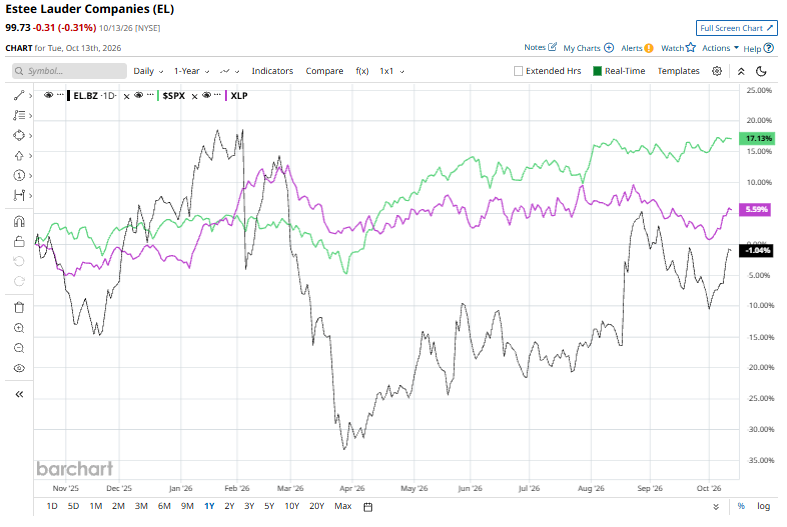
EL stock has risen 7.5% over the past 52 weeks, trailing both the S&P 500 Index ($SPX), which gained 17.3%, and the State Street Consumer Staples Select Sector SPDR ETF (XLP), which gained 8.2% over the same period.
EL’s struggles over the past year reflect persistent challenges in sales growth, profitability, and earnings performance. Weak organic sales growth, an operating margin of just 0%, and share issuance contributed to a 10.1% annual decline in EPS over the past three years, weighing on the company’s ability to sustain earnings growth.
However, signs of a potential recovery have emerged. On Oct. 5, Barclays upgraded EL from “Equalweight” to “Overweight” and raised its price target from $97 to $108 after the company’s fiscal Q4 2026 results exceeded market expectations for revenue, earnings, and margins. Still, uncertainty surrounding sales growth in China and travel retail remains a key risk, with analysts divided over the durability of the recovery. EL’s upcoming fiscal Q1 2027 results could offer further insight into whether the turnaround is sustainable.
Analysts remain cautiously bullish on EL, with the stock holding a consensus “Moderate Buy” rating. Of the 27 analysts covering the stock, 11 recommend a “Strong Buy,” one assigns a “Moderate Buy,” 14 rate it a “Hold,” and one gives it a “Strong Sell.” The average analyst price target of $160.19 suggests a potential 60.6% upside from the current share price.
On the date of publication, Kritika Sarmah did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.